Tax-Loss Harvesting 2026: Optimize Your Investment Portfolio
Anúncios
Tax-Loss Harvesting 2026: A Strategy for Your Investment Portfolio
As we look ahead to 2026, savvy investors are already considering strategies to optimize their portfolios and minimize their tax burden. Among the most powerful tools available is tax-loss harvesting 2026. This sophisticated yet accessible technique allows investors to sell investments at a loss to offset capital gains and, potentially, a portion of their ordinary income. While the concept might seem straightforward, successful implementation requires a deep understanding of the rules, timing, and potential pitfalls. This comprehensive guide will delve into everything you need to know about leveraging tax-loss harvesting in 2026 to enhance your financial outcomes.
Understanding the Fundamentals of Tax-Loss Harvesting
Before we dive into the specifics of tax-loss harvesting 2026, let’s establish a solid understanding of its core principles. At its heart, tax-loss harvesting involves selling securities (stocks, bonds, mutual funds, ETFs) that have declined in value. The realized loss can then be used to offset any capital gains you might have incurred from other investments. If your capital losses exceed your capital gains, you can use up to $3,000 of the remaining loss to offset your ordinary income. Any losses beyond that can be carried forward indefinitely to offset future capital gains or ordinary income.
This strategy is particularly effective in volatile market conditions, which often present more opportunities to identify investments trading below their purchase price. However, even in bull markets, individual securities can underperform, providing harvesting opportunities. The key is to be proactive and integrate this strategy into your overall financial planning.
Anúncios
Why is Tax-Loss Harvesting Relevant for 2026?
While the principles of tax-loss harvesting remain constant, the economic and legislative landscape can shift, making it crucial to consider the specific context of 2026. Potential changes in tax laws, market conditions, and personal financial situations can all influence the effectiveness and optimal timing of this strategy. By planning for tax-loss harvesting 2026 now, you give yourself ample time to identify opportunities, understand the implications, and consult with financial professionals.
The goal isn’t just to save on taxes; it’s to improve your overall portfolio’s tax efficiency, allowing more of your investment returns to compound over time. This can lead to significant wealth accumulation in the long run. Moreover, by selling underperforming assets, you can rebalance your portfolio, potentially investing in assets with stronger growth prospects, all while generating a tax benefit.
The Mechanics of Tax-Loss Harvesting: A Step-by-Step Guide
Implementing tax-loss harvesting 2026 effectively requires a methodical approach. Here’s a breakdown of the steps involved:
- Identify Losses: Regularly review your investment portfolio for positions that are currently trading below their purchase price. These are your potential candidates for harvesting.
- Sell Losing Investments: Sell the identified investments. The sale will realize the capital loss.
- Offset Capital Gains: Use the realized losses to offset any capital gains you’ve accumulated from selling other profitable investments.
- Offset Ordinary Income: If your capital losses exceed your capital gains, you can deduct up to $3,000 of the remaining loss against your ordinary income (e.g., salary, business income).
- Carry Forward Excess Losses: Any capital losses beyond the $3,000 limit can be carried forward to future tax years, indefinitely, to offset future capital gains or ordinary income.
- Reinvest Strategically: After selling a losing investment, you might want to reinvest the proceeds. However, you must be careful to avoid the wash-sale rule, which we’ll discuss in detail shortly.
The timing of these steps is crucial. For losses to be realized in the 2026 tax year, the sale must occur by December 31, 2026. However, it’s often prudent to execute these trades earlier in the year, or throughout the year, to avoid last-minute rushes and ensure proper settlement.
The Critical Wash-Sale Rule for 2026
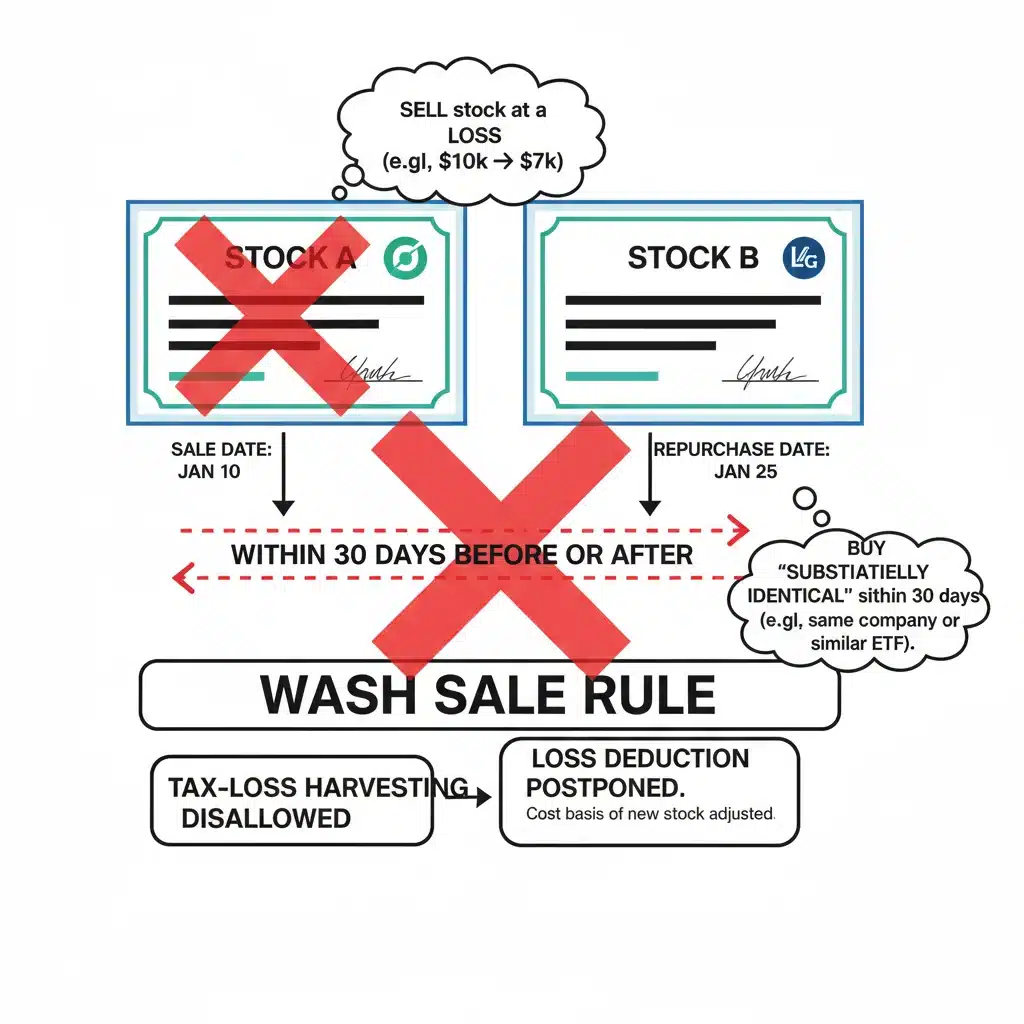
One of the most important rules to understand when engaging in tax-loss harvesting 2026 is the wash-sale rule. The IRS prohibits you from claiming a loss on a security if you buy a "substantially identical" security within 30 days before or after the sale date. This 61-day window (30 days before, the day of sale, and 30 days after) is designed to prevent investors from selling a security just to claim a loss and then immediately buying it back, effectively maintaining their position while gaining a tax benefit.
What constitutes "substantially identical"? This can be a nuanced area. Generally, it refers to a security that is virtually identical in all material respects to the one you sold. For example, buying back the exact same stock or a very similar ETF from the same issuer tracking the same index would likely trigger the wash-sale rule. To avoid this, investors often buy a different security that provides similar investment exposure but is not considered substantially identical. For instance, if you sell an S&P 500 ETF, you might buy a different S&P 500 ETF from a different provider, or an ETF tracking a similar broad market index.
Failing to adhere to the wash-sale rule can lead to the disallowance of your claimed loss, potentially resulting in unexpected tax liabilities. It’s crucial to track your trades carefully or use a brokerage that provides automated wash-sale rule tracking.
Benefits of Strategic Tax-Loss Harvesting in 2026
The advantages of incorporating tax-loss harvesting 2026 into your financial strategy extend beyond simply reducing your tax bill. Here are some key benefits:
Anúncios
- Reduced Capital Gains Taxes: This is the primary benefit. By offsetting capital gains, you can significantly lower the amount of tax you owe on profitable investments, allowing more of your money to remain invested and grow.
- Lower Ordinary Income Tax: The ability to deduct up to $3,000 against ordinary income can be a substantial benefit, especially for those in higher tax brackets.
- Portfolio Rebalancing Opportunities: Tax-loss harvesting provides a natural opportunity to review and rebalance your portfolio. By selling underperforming assets, you can strategically reallocate funds to investments that align better with your current financial goals and market outlook.
- Improved After-Tax Returns: By minimizing the impact of taxes on your investment gains, you effectively boost your after-tax returns, accelerating your wealth accumulation over time.
- Flexibility with Loss Carryforwards: The ability to carry forward unused losses indefinitely provides long-term flexibility. These losses can be a valuable asset to offset future capital gains, even years down the line.
- Psychological Benefits: While not directly financial, the act of actively managing your portfolio and finding ways to optimize it can provide a sense of control and empowerment, especially during market downturns.
Long-Term Impact on Wealth Accumulation
The compounding effect of saving on taxes year after year through tax-loss harvesting 2026 cannot be overstated. Consider two identical portfolios, one that consistently harvests losses and another that does not. Over decades, the portfolio utilizing tax-loss harvesting will likely generate significantly higher after-tax returns, leading to a much larger accumulated wealth. This is because every dollar saved in taxes is a dollar that can remain invested and continue to grow.
This strategy is particularly powerful for investors with long-term horizons, as it allows them to maintain exposure to the market while intelligently managing their tax obligations. It’s a testament to the fact that smart tax planning is an integral component of successful long-term investing.
Advanced Strategies and Considerations for 2026
Beyond the basic mechanics, there are several advanced considerations and strategies that can further optimize your tax-loss harvesting 2026 efforts.
Tax-Loss Harvesting with ETFs and Mutual Funds
ETFs and mutual funds are common investment vehicles, and they present unique considerations for tax-loss harvesting. While individual stocks are straightforward, "substantially identical" can be trickier with funds. If you sell an S&P 500 index ETF, you can usually buy a different S&P 500 index ETF from another provider without violating the wash-sale rule. The key is to ensure the new fund has a different issuer and, ideally, a slightly different underlying methodology or tracking index if possible, to minimize any IRS scrutiny.
For actively managed mutual funds, the risk of a wash sale with another fund is generally lower, as their investment strategies and holdings are typically distinct. However, always exercise caution and consult with a tax professional if unsure.
Tax-Loss Harvesting in Taxable vs. Tax-Advantaged Accounts
It’s crucial to remember that tax-loss harvesting is only applicable to investments held in taxable brokerage accounts. Losses in tax-advantaged accounts like 401(k)s, IRAs, or Roth IRAs cannot be used for tax-loss harvesting purposes because these accounts already offer tax benefits (tax-deferred growth or tax-free withdrawals). Therefore, when planning your tax-loss harvesting 2026 strategy, focus solely on your non-retirement investment accounts.
Year-End vs. Throughout the Year Harvesting
While many investors think of tax-loss harvesting as a year-end activity, it can be beneficial to harvest losses throughout the year. This approach, sometimes called "opportunistic harvesting," allows you to capture losses as they occur, rather than waiting until December. This can be advantageous for several reasons:
- Maximizing Opportunities: Market downturns or individual stock declines can happen at any time. Harvesting losses when they emerge ensures you don’t miss opportunities.
- Avoiding Year-End Rush: The end of the year can be a busy time for tax planning. Spreading out your harvesting efforts can reduce stress and potential errors.
- Better Reinvestment Opportunities: Reinvesting throughout the year allows you to take advantage of market fluctuations and potentially buy back into the market at lower prices.
However, year-end harvesting still serves a vital role, especially for those who need a final push to offset gains or simply prefer a single, concentrated effort.
Potential Pitfalls and How to Avoid Them
While powerful, tax-loss harvesting 2026 isn’t without its complexities. Being aware of potential pitfalls is key to a successful strategy.
- The Wash-Sale Rule (Revisited): As discussed, this is the biggest hurdle. Always double-check your trades and consider using different, but similar, securities for reinvestment.
- Transaction Costs: While often minimal with online brokers, frequent trading can incur transaction fees. Factor these into your calculations to ensure the tax benefit outweighs the costs.
- Market Rebound: Selling a losing investment means you miss out on any immediate rebound it might experience. If you believe the asset has strong long-term potential, selling it for a loss might conflict with your overall investment strategy. This is where the "substantially identical" replacement strategy becomes crucial – you can maintain market exposure.
- Emotional Decisions: Don’t let the desire for a tax deduction override sound investment principles. Only sell investments you truly believe are underperforming or no longer fit your portfolio strategy.
- Record Keeping: Accurate record keeping is paramount. You need to track your cost basis, sale prices, and dates to correctly report losses to the IRS. Most brokerage firms provide detailed tax statements, but it’s wise to maintain your own records as well.
Integrating Tax-Loss Harvesting into Your 2026 Financial Plan
For tax-loss harvesting 2026 to be truly effective, it needs to be an integrated part of your broader financial and tax planning. It shouldn’t be a standalone tactic but rather a component of a holistic approach to wealth management.
Collaboration with Financial Advisors and Tax Professionals
Given the complexities of tax law and investment strategies, working with a qualified financial advisor and a tax professional is highly recommended. They can help you:
- Identify appropriate harvesting opportunities.
- Navigate the wash-sale rule and other IRS regulations.
- Determine the optimal timing for sales based on your individual tax situation.
- Integrate tax-loss harvesting with your overall investment goals and risk tolerance.
- Ensure accurate reporting on your tax returns.
Their expertise can save you time, prevent costly errors, and ultimately maximize your tax savings.
Reviewing Your Investment Goals and Risk Tolerance
Tax-loss harvesting should always align with your long-term investment goals and risk tolerance. If selling an asset for a tax loss fundamentally alters your portfolio’s desired asset allocation or exposes you to unintended risks, it might not be the right move. Use harvesting as an opportunity to review and reaffirm your investment strategy, ensuring that any replacement investments are consistent with your objectives.
Staying Informed on Tax Law Changes
Tax laws can change, and what applies today might be different in 2026 or beyond. Staying informed about potential legislative changes that could impact capital gains taxes, loss deduction limits, or other relevant provisions is crucial. Reliable financial news sources, professional organizations, and your financial advisors can help you stay up-to-date.
Case Study: Illustrating the Power of Tax-Loss Harvesting
Let’s consider a hypothetical example to illustrate the impact of tax-loss harvesting 2026.
Imagine an investor, Sarah, who has the following in 2026:
- Realized Capital Gains: $10,000 from selling a profitable tech stock.
- Unrealized Capital Losses: $15,000 from a diversified international fund that has underperformed.
- Ordinary Income: $80,000.
Scenario 1: No Tax-Loss Harvesting
Sarah would owe capital gains tax on the full $10,000. Assuming a 15% long-term capital gains tax rate, she would pay $1,500 in taxes. Her international fund would remain in her portfolio, still showing an unrealized loss.
Scenario 2: With Tax-Loss Harvesting
Sarah decides to harvest her losses. She sells the international fund, realizing a $15,000 capital loss. To avoid the wash-sale rule, she reinvests the proceeds into a similar but not substantially identical international ETF.
- Offset Capital Gains: The $15,000 loss first offsets her $10,000 capital gain, bringing her net capital gains to $0. This saves her $1,500 in capital gains tax.
- Offset Ordinary Income: She has $5,000 ($15,000 – $10,000) in excess capital losses. She can use $3,000 of this to offset her ordinary income. Assuming a 22% marginal income tax bracket, this saves her an additional $660 ($3,000 * 0.22).
- Carry Forward Losses: The remaining $2,000 ($5,000 – $3,000) in losses can be carried forward to 2027 and beyond, ready to offset future gains or income.
In total, Sarah saved $2,160 in taxes for 2026 and has a valuable $2,000 loss carryforward for the future, all while maintaining her desired international market exposure. This demonstrates the tangible benefits of proactive tax-loss harvesting 2026.
Conclusion: Making Tax-Loss Harvesting a Core Part of Your 2026 Strategy
As you plan your investment strategies for 2026, remember that proactive tax management is just as important as selecting the right investments. Tax-loss harvesting 2026 offers a powerful, IRS-sanctioned method to reduce your tax liability, enhance your after-tax returns, and improve the overall efficiency of your portfolio. By understanding the rules, particularly the critical wash-sale rule, and integrating this strategy throughout the year, you can turn market downturns into tax-saving opportunities.
Whether you’re a seasoned investor or just starting, incorporating tax-loss harvesting into your financial toolkit can significantly impact your long-term wealth accumulation. Don’t leave money on the table; consult with your financial advisor and tax professional to ensure you’re fully leveraging the benefits of tax-loss harvesting 2026 for a more robust and tax-efficient investment journey.
Remember, the goal is not just to invest wisely, but to invest tax-wisely. Start planning today to make 2026 a year of optimized returns and reduced tax burdens.