Retirement Planning 2026: Optimize Your 401(k) for Maximum Growth
As we navigate the ever-evolving financial landscape, the year 2026 is rapidly approaching, bringing with it new opportunities and considerations for retirement planning. For many, a 401(k) remains the cornerstone of their retirement strategy. However, simply contributing is often not enough. To truly secure a comfortable and prosperous future, it’s crucial to understand the nuances of 401k optimization 2026. This comprehensive guide will delve into the essential strategies, regulatory updates, and expert tips to help you maximize your 401(k) contributions and ensure optimal growth for your golden years.
The world of retirement savings is dynamic, influenced by economic shifts, legislative changes, and personal circumstances. What worked last year might not be the most effective approach for 2026. Therefore, a proactive and informed strategy is paramount. We’ll explore everything from understanding the new contribution limits to leveraging advanced investment techniques, all aimed at enhancing your 401(k)’s potential.
Understanding the 401(k) Landscape in 2026
Before diving into specific optimization strategies, it’s vital to grasp the current and projected environment for 401(k) plans in 2026. The Internal Revenue Service (IRS) typically announces changes to contribution limits late in the preceding year. While we don’t have the exact figures for 2026 yet, we can anticipate trends based on inflation and economic growth. Historically, these limits have seen gradual increases, allowing individuals to save more each year. Staying informed about these changes is the first step in effective 401k optimization 2026.
Anúncios
Beyond contribution limits, understanding the types of 401(k) plans available – traditional vs. Roth – is crucial. Each offers distinct tax advantages that can significantly impact your retirement income. A traditional 401(k) allows pre-tax contributions, reducing your taxable income in the present, with withdrawals taxed in retirement. A Roth 401(k), on the other hand, accepts after-tax contributions, meaning your qualified withdrawals in retirement are tax-free. The choice between these two often depends on your current income level, anticipated future tax bracket, and overall financial strategy.
Projected Contribution Limits for 2026
While official numbers are usually released in October or November of the preceding year, financial experts often provide projections. For 2026, it’s reasonable to expect a slight increase in the elective deferral limit for employees. For instance, if the limit for 2025 were $23,000, it might rise to $23,500 or $24,000 for 2026, reflecting inflation. Similarly, the catch-up contribution limit for those aged 50 and over is also likely to see an adjustment. These increases are critical for maximizing your 401k optimization 2026 efforts, as they directly dictate how much you can squirrel away each year.
Keeping an eye on these projections and the official announcements will allow you to adjust your payroll deductions promptly. Many employers offer the flexibility to change your contribution percentage throughout the year. Don’t wait until the last minute; plan ahead to ensure you’re contributing the maximum allowable amount.
Maximizing Your Contributions: Strategies for 401k Optimization 2026
Once you understand the landscape, the next step is to implement strategies that maximize your contributions. This isn’t just about hitting the limit; it’s about making your money work harder for you.
1. Contribute the Maximum Allowable
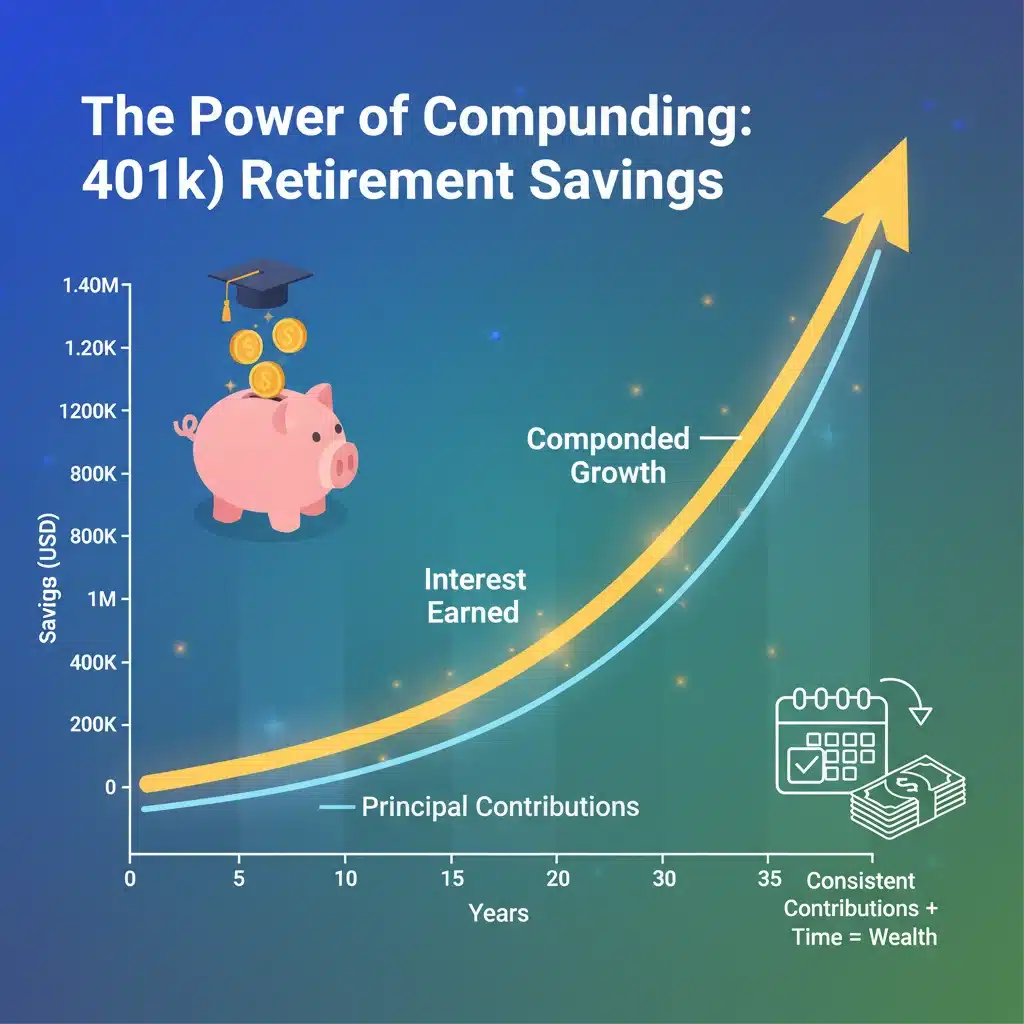
This is arguably the most straightforward yet most impactful strategy. If your budget allows, always aim to contribute the maximum amount permitted by the IRS. Every dollar contributed early benefits from the power of compounding over a longer period. For 401k optimization 2026, this means taking full advantage of the standard employee deferral limit and, if applicable, the catch-up contribution for those 50 and older.
Consider automating your contributions to make this easier. Most payroll systems allow you to set a percentage or a fixed dollar amount to be deducted directly from each paycheck. This ‘set it and forget it’ approach ensures consistency and helps avoid the temptation to spend the money elsewhere.
2. Don’t Leave Employer Match on the Table
An employer match is essentially free money. If your company offers a matching contribution, ensure you’re contributing at least enough to receive the full match. For example, if your employer matches 50% of your contributions up to 6% of your salary, you should contribute at least 6% to get the full benefit. Failing to do so is leaving guaranteed returns on the table, severely hindering your 401k optimization 2026.
This match can significantly boost your savings, sometimes adding thousands of dollars to your account annually without you having to contribute extra from your own pocket. Always check your plan’s details regarding vesting schedules for employer contributions. Understanding when these matched funds become fully yours is an important aspect of your overall retirement planning.
3. Understand the Power of Catch-Up Contributions
For individuals aged 50 and older, the IRS allows for additional ‘catch-up’ contributions above the standard limit. This provision is designed to help those closer to retirement bolster their savings. As mentioned earlier, this limit is also subject to annual adjustments. If you’re in this age bracket, utilizing catch-up contributions is a powerful tool for 401k optimization 2026, potentially adding thousands more to your retirement nest egg each year.
Anúncios
These contributions can make a significant difference, especially if you started saving later in life or had periods where you couldn’t contribute as much. It’s an excellent opportunity to accelerate your savings and make up for lost time.
4. Consider a Roth 401(k) Option
If your employer offers a Roth 401(k) option, it’s worth considering, especially if you anticipate being in a higher tax bracket in retirement than you are now. While contributions are made with after-tax dollars, qualified withdrawals in retirement are entirely tax-free. This can be a huge advantage, particularly for younger professionals who expect their income to grow substantially over their careers, or for those who believe tax rates will increase in the future.
The Roth 401(k) also offers flexibility, as distributions from contributions (not earnings) can be withdrawn tax-free and penalty-free at any time. This flexibility, combined with tax-free growth, makes it a compelling option for many seeking advanced 401k optimization 2026.
Investment Strategies for Optimal 401(k) Growth
Contributing regularly and maximizing your limits is foundational, but the true growth of your 401(k) comes from smart investment choices. Your investment strategy should align with your risk tolerance, time horizon, and financial goals.
1. Diversification is Key
A well-diversified portfolio is essential to mitigate risk and maximize returns. Don’t put all your eggs in one basket. Your 401(k) should ideally include a mix of asset classes, such as stocks (domestic and international), bonds, and potentially real estate or other alternative investments, depending on the options available in your plan. Diversification helps smooth out returns, as different asset classes perform well under different economic conditions. This is a core principle of effective 401k optimization 2026.
Many 401(k) plans offer target-date funds, which automatically diversify and rebalance their holdings based on your projected retirement year. While convenient, it’s still important to understand their underlying investments and ensure they align with your personal risk profile.
2. Understand Your Risk Tolerance
Your investment choices should always reflect your personal risk tolerance. If you’re many years away from retirement, you might be comfortable taking on more risk with a higher allocation to equities, which historically offer higher returns over the long term. As you get closer to retirement, you might want to shift towards a more conservative portfolio with a higher allocation to bonds, which are generally less volatile.
Regularly assess your risk tolerance, especially if there are significant changes in your life circumstances or market conditions. This self-assessment is crucial for ongoing 401k optimization 2026, ensuring your portfolio remains appropriate for your stage of life.
3. Rebalance Your Portfolio Periodically
Over time, market fluctuations can cause your asset allocation to drift from your target. For example, if stocks have performed exceptionally well, they might now represent a larger percentage of your portfolio than you initially intended. Rebalancing involves selling some of the overperforming assets and buying more of the underperforming ones to bring your portfolio back to your desired allocation.
This discipline helps you ‘buy low and sell high’ over the long term and ensures your portfolio’s risk level remains consistent. Most financial advisors recommend rebalancing at least once a year. Some 401(k) plans offer automatic rebalancing options, which can be a convenient feature for hands-off 401k optimization 2026.
4. Minimize Fees
Fees, even seemingly small ones, can significantly erode your retirement savings over decades. Be diligent in understanding the fees associated with your 401(k) plan and the underlying investment options. These can include administrative fees, fund expense ratios, and transaction fees.
Compare the fees of different funds within your plan. Opt for low-cost index funds or ETFs when available, as they often outperform actively managed funds over the long term, especially after accounting for fees. Being fee-conscious is a critical, often overlooked, aspect of 401k optimization 2026.
Advanced 401(k) Optimization Techniques for 2026
Beyond the fundamental strategies, there are several advanced techniques that savvy investors can employ to further enhance their 401(k) savings.
1. The Mega Backdoor Roth
For high-income earners who have already maxed out their traditional and Roth 401(k) contributions, the ‘mega backdoor Roth’ can be an incredibly powerful tool. This strategy involves making after-tax contributions to your 401(k) (if your plan allows it), and then converting those after-tax contributions into a Roth IRA. This allows you to bypass the Roth IRA income limits and contribute a substantial amount to a tax-free growth vehicle.
It’s important to note that not all 401(k) plans permit after-tax contributions, and the process can be complex. Consulting with a financial advisor is highly recommended if you’re considering this advanced 401k optimization 2026 strategy.
2. Leveraging the Solo 401(k) for Self-Employed Individuals
If you’re self-employed or have significant freelance income, a Solo 401(k) (also known as an individual 401(k)) offers much higher contribution limits than a traditional or Roth IRA. You can contribute both as an employee and as an employer, allowing for substantial tax-deferred or tax-free growth.
For 2026, the combined employee and employer contribution limit for a Solo 401(k) is expected to be significantly higher than regular 401(k) limits. This makes it an indispensable tool for self-employed individuals focused on 401k optimization 2026.
3. Understanding In-Service Withdrawals and Rollovers
Some 401(k) plans allow for ‘in-service’ withdrawals, which permit you to roll over a portion of your 401(k) funds into an IRA while still employed. This can be beneficial if your current 401(k) plan has limited investment options or high fees. Rolling funds into an IRA often provides access to a much wider array of investment vehicles and potentially lower costs.
However, it’s crucial to understand the rules and potential tax implications before initiating an in-service rollover. This move can be a strategic part of 401k optimization 2026, but requires careful consideration.
Monitoring and Adjusting Your 401(k) in 2026
Retirement planning is not a one-time event; it’s an ongoing process that requires regular monitoring and adjustments. The financial markets, your personal circumstances, and even tax laws can change, necessitating a review of your 401(k) strategy.
1. Annual Review of Your Plan
Make it a habit to review your 401(k) statement and investment performance at least once a year. Check your asset allocation, ensure your contributions are on track, and evaluate the performance of your chosen funds. This annual review is crucial for effective 401k optimization 2026.
During this review, also consider any life changes – a new job, a significant raise, marriage, children, or approaching retirement – that might warrant a change in your contribution strategy or investment mix. Adjusting your plan as needed ensures it remains aligned with your evolving goals.
2. Stay Informed About Legislation Changes
Tax laws and retirement regulations are subject to change. New legislation, such as the SECURE Act and SECURE 2.0, has already brought significant changes to retirement planning. Staying informed about any potential legislative changes for 2026 and beyond is vital. These changes could impact contribution limits, distribution rules, or even the types of investments allowed in your 401(k).
Reliable financial news sources and consultations with financial professionals can help you stay ahead of these changes, allowing you to adapt your 401k optimization 2026 strategy accordingly.
3. Seek Professional Advice
While this guide provides a wealth of information, personal finance can be complex. A qualified financial advisor can provide personalized guidance tailored to your specific situation. They can help you assess your risk tolerance, create a diversified portfolio, navigate complex tax implications, and develop a holistic retirement plan that goes beyond just your 401(k).
Especially when considering advanced strategies like the mega backdoor Roth or in-service rollovers, professional advice is invaluable. An advisor can help you make informed decisions and ensure your 401k optimization 2026 efforts are truly maximized.
Common Pitfalls to Avoid in 401(k) Optimization
Even with the best intentions, several common mistakes can hinder your 401(k) growth. Being aware of these pitfalls can help you steer clear of them.
1. Not Contributing Enough (or at All)
The most significant mistake is not contributing to your 401(k) at all, or not contributing enough to at least get the full employer match. This is leaving free money and significant tax advantages on the table. Start saving early, even if it’s a small amount, and gradually increase your contributions as your income grows.
2. Cashing Out Your 401(k) When Changing Jobs
When you change jobs, it can be tempting to cash out your 401(k) balance. However, this often incurs significant taxes and penalties, and you lose out on future tax-deferred growth. Instead, consider rolling over your 401(k) into your new employer’s plan or into an IRA. This preserves your retirement savings and continues their growth trajectory.
3. Taking a 401(k) Loan
While some plans allow 401(k) loans, they should generally be a last resort. Taking a loan from your 401(k) means your money is not invested and growing during the loan period. If you leave your job or fail to repay the loan, it can become a taxable distribution subject to penalties. Explore other options before tapping into your retirement savings.
4. Ignoring Your Investments
Setting up your 401(k) and forgetting about it is another common pitfall. As discussed, regular review and rebalancing are crucial. Market conditions change, and your risk tolerance evolves. An unmanaged 401(k) portfolio might not be performing optimally or might expose you to unnecessary risk.
5. Panicking During Market Downturns
Market volatility is a natural part of investing. Panicking and selling off your investments during a downturn can lock in losses and prevent you from participating in the eventual recovery. A long-term perspective and a diversified portfolio are your best defenses against market fluctuations. Remember that 401k optimization 2026 is a marathon, not a sprint.
Conclusion: Charting Your Course for 401(k) Optimization 2026
Effective 401k optimization 2026 is a multifaceted endeavor that requires diligent planning, informed decision-making, and consistent monitoring. By understanding the projected contribution limits, maximizing your contributions (especially employer matches and catch-up contributions), and implementing smart investment strategies like diversification and rebalancing, you can significantly enhance your retirement savings.
Furthermore, exploring advanced techniques such as the mega backdoor Roth or Solo 401(k), where applicable, can provide additional avenues for growth. Remember to regularly review your plan, stay informed about legislative changes, and don’t hesitate to seek professional financial advice to tailor your strategy to your unique circumstances.
Your retirement security is a journey, not a destination. By taking proactive steps now, leveraging the insights into 401k optimization 2026, and avoiding common pitfalls, you can build a robust financial foundation that will support your dreams for a comfortable and fulfilling retirement. Start planning today, and watch your future self thank you.
The path to a secure retirement is within your reach. Embrace these strategies, stay disciplined, and make 2026 the year you truly elevate your retirement planning game. The effort you put in today will yield substantial rewards tomorrow, ensuring a prosperous future where your financial worries are minimized, and your golden years are truly golden.
Don’t let inertia be your enemy. Take control of your financial destiny by actively engaging with your 401(k) and making conscious choices that align with your long-term goals. The principles of 401k optimization 2026 are designed to empower you, providing the tools and knowledge necessary to navigate the complexities of retirement savings with confidence and clarity.