Federal Employee Benefits 2026: Navigating Your Retirement and Health Insurance Options
As a federal employee, understanding your benefits is paramount to securing your financial future and ensuring your well-being. The landscape of federal employee benefits is comprehensive, encompassing robust retirement plans and critical health insurance options. With 2026 on the horizon, it’s crucial to stay informed about potential changes and how to best utilize these valuable resources. This guide will delve into the intricacies of federal employee benefits 2026, focusing on the Federal Employees Retirement System (FERS), the Thrift Savings Plan (TSP), and the Federal Employees Health Benefits (FEHB) program, including the much-discussed 1.5% premium adjustment.
The commitment of the federal government to its workforce is reflected in the extensive benefits package offered. These benefits are not just perks; they are fundamental components of a federal employee’s total compensation, designed to provide stability during working years and security in retirement. From defined-benefit pensions to tax-advantaged savings plans and comprehensive health coverage, the provisions are designed to attract and retain a skilled workforce dedicated to public service. Staying abreast of the latest information, especially concerning annual adjustments and enrollment periods, is key to maximizing these benefits.
For many, the sheer volume of information can be overwhelming. This article aims to demystify the core components of federal employee benefits 2026, offering clear explanations and practical advice. Whether you are a new federal employee just starting your career, or a seasoned veteran nearing retirement, a thorough understanding of these programs will empower you to make informed decisions that align with your personal and financial goals. Let’s embark on this journey to explore the crucial elements of your federal benefits package for the upcoming year.
Anúncios
Understanding the Federal Employees Retirement System (FERS) for 2026
The Federal Employees Retirement System (FERS) is the cornerstone of retirement planning for most federal employees hired after 1983. It is a three-tiered system comprising a Basic Benefit Plan, Social Security, and the Thrift Savings Plan (TSP). Each component plays a vital role in providing a secure retirement income. For 2026, while the fundamental structure of FERS is expected to remain consistent, it’s always wise to monitor any legislative updates or policy changes that could impact your future benefits.
FERS Basic Benefit Plan: Your Defined-Benefit Pension
The FERS Basic Benefit Plan is a defined-benefit pension, meaning it provides a guaranteed income stream in retirement based on your years of service and your highest average salary (High-3) over three consecutive years. The formula for calculating your annuity is generally 1% of your High-3 average salary multiplied by your years of creditable service. If you retire at age 62 or later with at least 20 years of service, the multiplier increases to 1.1%. Understanding this formula is crucial for estimating your future pension income and planning your retirement budget.
As we look towards 2026, it’s important to understand how your contributions and years of service accumulate. Every year you work for the federal government adds to your creditable service, directly increasing your future annuity. Furthermore, understanding the various retirement eligibility options under FERS – such as optional retirement, early optional retirement, and deferred retirement – is key to strategically planning your departure from federal service. Each option has specific age and service requirements, and knowing these can significantly impact when and how you choose to retire.
Social Security: An Integral Part of FERS
Unlike previous federal retirement systems, FERS includes Social Security as a component. This means federal employees under FERS contribute to and are eligible for Social Security benefits, just like most private-sector workers. The Social Security component provides a safety net and additional income stream in retirement. For 2026, potential cost-of-living adjustments (COLAs) to Social Security benefits will be announced, which can impact your overall retirement income. It’s essential to keep track of your Social Security earnings record by regularly checking your statements from the Social Security Administration.
The integration of Social Security into FERS offers a diversified approach to retirement income, reducing reliance on a single source. This also means that federal employees benefit from the portability of Social Security, as earnings from both federal and private sector employment contribute to their overall Social Security benefit. Understanding how your FERS pension, Social Security, and TSP interact is fundamental to a holistic retirement strategy, ensuring you are well-prepared for your post-employment years.
Maximizing Your Thrift Savings Plan (TSP) in 2026
The Thrift Savings Plan (TSP) is a defined-contribution plan, similar to a 401(k) in the private sector, and is arguably one of the most powerful tools in a federal employee’s retirement arsenal. It allows employees to save for retirement on a tax-deferred basis (Traditional TSP) or tax-exempt basis (Roth TSP), with the added benefit of government matching contributions.
Government Contributions and Matching
One of the most attractive features of the TSP is the government’s contribution. All FERS employees automatically receive an agency contribution equal to 1% of their basic pay, even if they don’t contribute themselves. Furthermore, the government provides matching contributions on the first 5% of an employee’s contributions: 100% on the first 3% and 50% on the next 2%. This effectively means a federal employee contributing 5% of their salary to TSP receives an additional 5% contribution from the government, totaling a 10% contribution to their retirement savings. This ‘free money’ is a critical component of federal employee benefits 2026 and should be maximized by all eligible employees.
Understanding the vesting schedule for these contributions is also important. Agency automatic (1%) contributions have a two-year vesting period for most employees, while agency matching contributions are immediately vested. This means that after two years of federal service, the 1% contributions become yours, even if you leave federal employment. The power of compounding interest, combined with these generous government contributions, makes the TSP an incredibly effective vehicle for long-term wealth accumulation.
Investment Funds and Strategies for 2026
The TSP offers a selection of low-cost index funds: the G Fund (Government Securities), F Fund (Fixed Income Index), C Fund (Common Stock Index), S Fund (Small Capitalization Stock Index), and I Fund (International Stock Index). Additionally, Lifecycle (L) Funds provide a professionally managed, diversified portfolio tailored to different retirement timelines. For 2026, it’s a good time to review your investment choices within the TSP. Your risk tolerance, time horizon, and financial goals should all factor into your investment strategy.
Anúncios
Regularly reviewing your TSP allocation is a best practice. As you get closer to retirement, you might consider shifting towards a more conservative allocation to protect your accumulated savings. Conversely, younger employees with a longer time horizon can afford to take on more risk for potentially higher returns. The TSP website provides excellent resources, including fund performance data and educational materials, to help you make informed investment decisions. Don’t underestimate the impact of smart investment choices on your overall federal employee benefits 2026 retirement outlook.
Federal Employees Health Benefits (FEHB) Program: What to Expect in 2026
The Federal Employees Health Benefits (FEHB) program is one of the most comprehensive health insurance programs in the nation, offering a wide range of choices to federal employees, retirees, and their families. Each year, during the Open Season, employees have the opportunity to review their options and make changes to their health coverage. For 2026, one of the most significant considerations will be the potential 1.5% premium adjustment.
The 1.5% Premium Adjustment and Its Impact
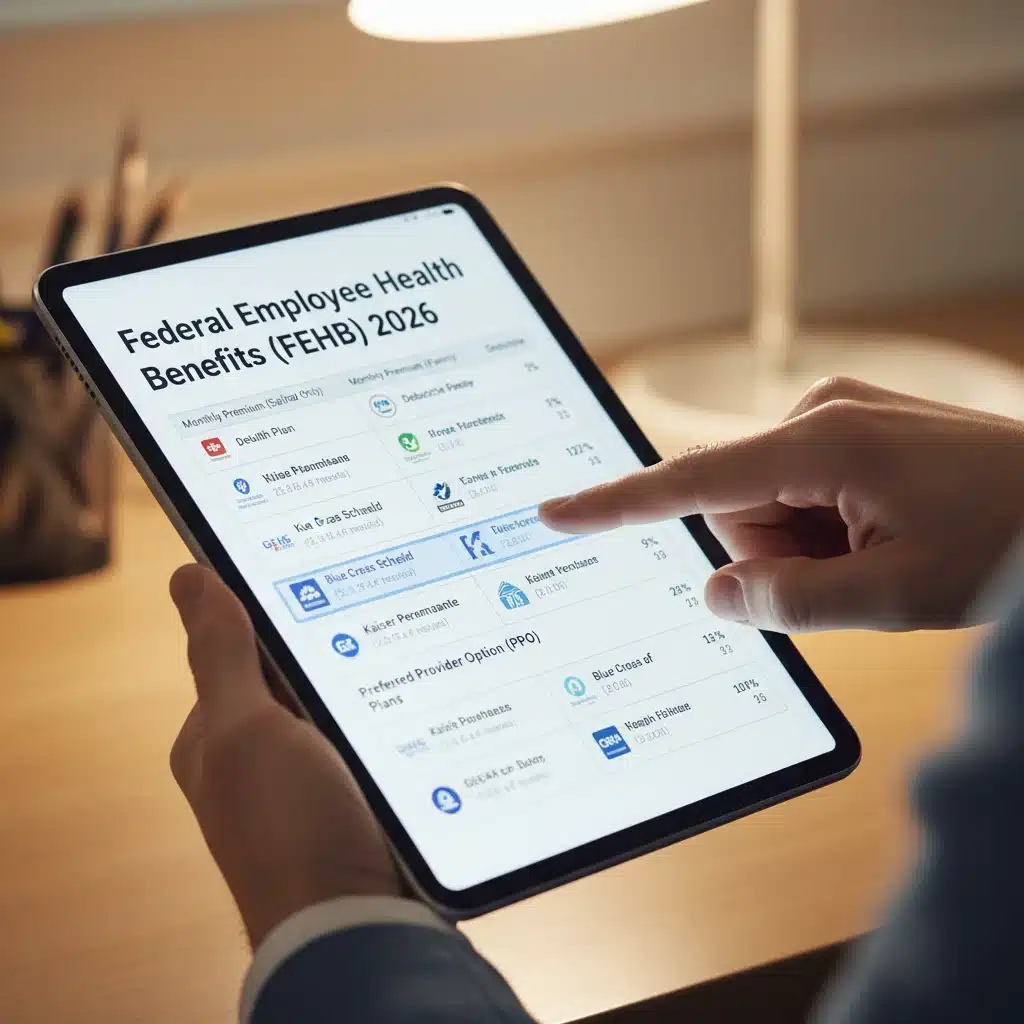
Discussions around a 1.5% premium adjustment for FEHB plans in 2026 highlight the ongoing effort to balance comprehensive coverage with affordability. While specific details will emerge closer to the Open Season, such an adjustment would mean a slight increase in the amount federal employees contribute towards their health insurance premiums. It’s important to remember that the federal government generally covers a significant portion of the premium (typically around 72% of the average premium across all plans, up to 75% of any individual plan’s premium). Even with an adjustment, FEHB remains a highly competitive and valuable benefit.
Understanding how premium adjustments affect your out-of-pocket costs is crucial for budgeting. When the official rates for 2026 are released, compare them carefully with your current plan and other available options. Consider not just the premium, but also deductibles, co-pays, out-of-pocket maximums, and prescription drug coverage. A seemingly small premium increase might be offset by superior coverage or lower co-pays in a different plan, making a switch a financially sound decision. This diligent review is a key part of managing your federal employee benefits 2026 effectively.
Choosing the Right FEHB Plan for Your Needs
The FEHB program offers a vast array of plans from various carriers, including Fee-for-Service (FFS) plans, Health Maintenance Organizations (HMOs), and High Deductible Health Plans (HDHPs) with Health Savings Accounts (HSAs). With so many choices, selecting the right plan can seem daunting. Here’s a breakdown of factors to consider for 2026:
- Healthcare Needs: Do you have chronic conditions? Do you anticipate needing significant medical care in the coming year? If so, a plan with lower deductibles and co-pays might be more cost-effective, even with a slightly higher premium.
- Provider Network: Does your preferred doctor or hospital participate in the plan’s network? Out-of-network care can be significantly more expensive.
- Prescription Drug Coverage: Compare formularies and co-pays for your specific medications across different plans.
- Financial Situation: HDHPs often have lower premiums but higher deductibles, which can be advantageous if you rarely use medical services or if you can contribute to and benefit from an HSA.
- Family Coverage: Consider whether a self-only, self-plus-one, or family enrollment is most appropriate and cost-effective for your household.
The annual FEHB Open Season is your opportunity to re-evaluate and switch plans. Don’t assume your current plan is still the best fit without a thorough review. Utilize resources like the OPM website and plan comparison tools to make an informed decision about your federal employee benefits 2026 health coverage.
Other Key Federal Employee Benefits for 2026
Beyond retirement and health insurance, federal employees enjoy a suite of other valuable benefits that contribute to their overall compensation and well-being. These include life insurance, long-term care insurance, dental and vision insurance, and flexible spending accounts.
Federal Employees’ Group Life Insurance (FEGLI)
FEGLI provides group term life insurance to federal employees and retirees. It offers various coverage options, including Basic Life, Option A (Standard), Option B (Additional), and Option C (Family). While FEGLI is a convenient option, it’s often worth comparing its costs and coverage with private life insurance policies, especially as you age, as FEGLI premiums can increase significantly. For 2026, ensure your beneficiaries are up to date and that your coverage aligns with your family’s needs.
Federal Long Term Care Insurance Program (FLTCIP)
Long-term care can be incredibly expensive, and it’s not typically covered by health insurance or Medicare. The FLTCIP offers federal employees, retirees, and their qualified family members the opportunity to purchase long-term care insurance at competitive group rates. This benefit provides financial protection for services like in-home care, assisted living, and nursing home care. While not mandatory, considering FLTCIP for 2026 is a prudent step in comprehensive financial planning, especially as healthcare costs continue to rise.
Federal Employees Dental and Vision Insurance Program (FEDVIP)
FEDVIP allows federal employees, retirees, and their eligible family members to enroll in dental and vision plans. These plans are separate from FEHB and offer a wide range of choices from various providers. Like FEHB, FEDVIP has an annual Open Season where you can enroll or make changes. Reviewing your dental and vision needs for 2026 and comparing the available plans is essential to ensure you have adequate coverage for these important aspects of your health.
Flexible Spending Accounts (FSAs)
Flexible Spending Accounts (FSAs) allow federal employees to set aside pre-tax money to pay for eligible healthcare and dependent care expenses. This can result in significant tax savings. There are two main types: Health Care FSA (HCFSA) and Dependent Care FSA (DCFSA). For 2026, be aware of the annual contribution limits and the ‘use-it-or-lose-it’ rule (though some carryover provisions exist). Planning your FSA contributions carefully based on anticipated expenses is key to maximizing this tax-advantaged benefit.
Planning Your Retirement: A Holistic Approach for 2026
Effective retirement planning for federal employees extends beyond simply understanding the components of FERS and TSP. It involves a holistic approach that integrates all your federal employee benefits 2026 with your personal financial strategy.
Integrating FERS, TSP, and Social Security
The synergy between your FERS annuity, TSP savings, and Social Security benefits is crucial. Your FERS pension provides a stable, predictable income. Your TSP offers growth potential and flexibility. Social Security adds another layer of financial security. When planning, consider how these three streams will combine to meet your income needs in retirement. Tools and calculators available on OPM and TSP websites can help you project your future income and assess any potential gaps.
Strategic Contributions and Withdrawals
For your TSP, consistently contributing at least 5% to get the full government match is non-negotiable. Beyond that, consider increasing your contributions as your salary grows. For 2026, be mindful of the annual IRS contribution limits for elective deferrals and catch-up contributions (for those aged 50 and over). Understanding TSP withdrawal options – such as single payments, monthly payments, or a combination – is also vital for creating a sustainable retirement income strategy.
Considering Early Retirement and Special Provisions
Some federal employees may qualify for special retirement provisions, such as those in law enforcement, air traffic control, or firefighters. These provisions often allow for earlier retirement with full benefits. Additionally, understanding Voluntary Early Retirement Authority (VERA) and Discontinued Service Retirement (DSR) options, which may be offered during agency reorganizations, can provide alternative pathways to retirement. Always consult with a benefits specialist or financial advisor to understand the implications of these complex options for your federal employee benefits 2026.
Key Actions for Federal Employees in 2026
To ensure you are fully prepared and maximizing your federal employee benefits 2026, consider the following actions:
- Review Your Personnel Records: Verify your service history, pay grade, and beneficiary designations are accurate and up-to-date.
- Check Your TSP Account: Review your current investment allocation, ensure you are contributing at least 5% to get the full match, and consider increasing contributions if possible.
- Prepare for FEHB Open Season: As information becomes available for 2026, thoroughly compare plans, considering potential premium adjustments, deductibles, and coverage needs.
- Understand Social Security: Regularly check your Social Security statement for accuracy and estimate your future benefits.
- Assess Other Benefits: Review your FEGLI coverage, consider FLTCIP, and evaluate FEDVIP and FSA options based on your anticipated needs.
- Seek Professional Advice: If you have complex financial situations or are nearing retirement, consult with a financial advisor specializing in federal benefits.
Conclusion: Securing Your Future with Federal Employee Benefits 2026
The comprehensive package of federal employee benefits 2026 is a significant advantage for those dedicated to public service. By diligently understanding and strategically managing your FERS pension, TSP investments, and FEHB health insurance, you can build a strong foundation for both your working years and a comfortable retirement. The potential 1.5% premium adjustment for FEHB underscores the importance of staying informed and proactive during annual enrollment periods.
Your federal benefits are dynamic, with annual adjustments and new considerations. Proactive engagement, careful planning, and a willingness to adapt your strategies are key to maximizing these invaluable resources. Take the time to educate yourself, utilize the available tools, and seek expert advice when needed. Your future financial security and well-being are directly linked to how well you navigate the landscape of federal employee benefits 2026. By taking these steps, you are not just planning for retirement; you are investing in a secure and healthy future.