Credit Card Interest Rates: How to Avoid a 24% APR on Your Balances
Anúncios
Credit Card Interest Rates: How to Avoid a 24% APR on Your Balances
In today’s financial landscape, credit cards are an indispensable tool for many, offering convenience, rewards, and a safety net for emergencies. However, the convenience comes with a significant caveat: interest rates. A high Annual Percentage Rate (APR), particularly one hovering around 24%, can quickly turn a useful financial instrument into a heavy burden. Understanding how to avoid high credit card APR is crucial for maintaining financial health and preventing debt from spiraling out of control.
Imagine carrying a balance of just $2,500 on a card with a 24% APR. If you only make the minimum payment, a significant portion of that payment will go towards interest, making it incredibly difficult to pay down the principal. Over time, you could end up paying hundreds, if not thousands, of dollars in interest alone. This article will delve into the mechanisms of credit card interest, explain why some APRs are so high, and, most importantly, provide actionable strategies to help you avoid high credit card APR and manage your finances more effectively.
Understanding Credit Card APR: The Basics
Before we can discuss how to avoid high credit card APR, it’s essential to understand what APR actually means. APR is the annual rate charged for borrowing, or earned by investing, expressed as a single percentage number that represents the actual yearly cost of funds over the term of a loan. For credit cards, it’s the interest rate you’ll pay on your outstanding balance, calculated annually. However, credit card interest is typically calculated daily, meaning the annual rate is divided by 365 to determine the daily periodic rate.
Anúncios
There are several types of APRs you might encounter:
- Purchase APR: This is the most common type and applies to new purchases you make with your credit card.
- Cash Advance APR: This rate applies when you withdraw cash using your credit card. It’s usually significantly higher than the purchase APR and often comes with immediate interest accrual and a transaction fee.
- Balance Transfer APR: This rate applies to balances you transfer from another credit card. Many cards offer promotional 0% balance transfer APRs for an introductory period, which can be a great way to consolidate debt, but be mindful of the rate after the introductory period ends.
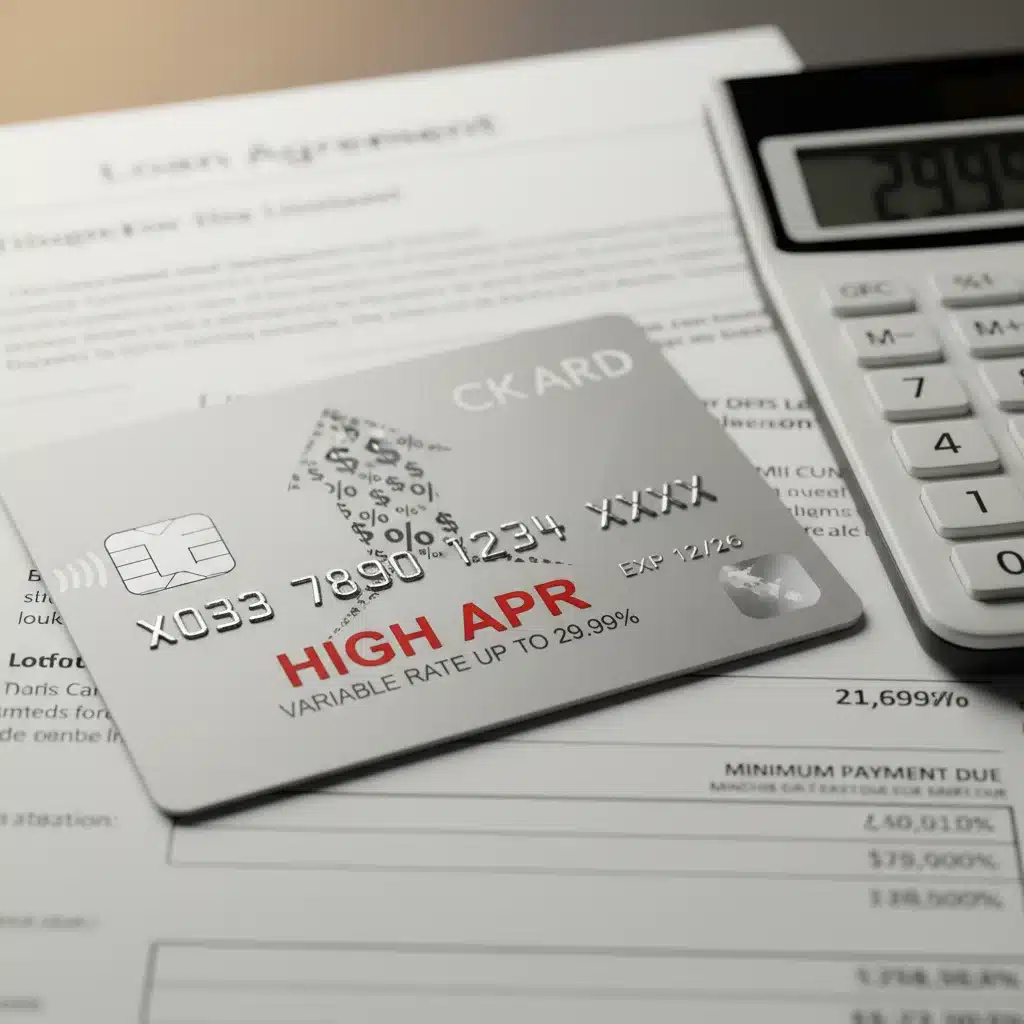
- Penalty APR: This is a significantly higher APR that can be triggered if you make a late payment or violate other terms of your cardholder agreement. It can be as high as 29.99% or even more, and can stay on your account for a prolonged period.
A 24% APR is considered quite high, often indicating either a consumer with a lower credit score, a specific type of card (like a store card), or a card with a variable interest rate that has increased due to market conditions. Understanding these different rates is the first step in learning to avoid high credit card APR.
Why Are Some APRs So High? Factors Influencing Your Rate
Several factors contribute to the APR you’re offered on a credit card. By understanding these, you can take steps to improve your standing and potentially qualify for lower rates, helping you to avoid high credit card APR.
Your Credit Score
This is arguably the most significant factor. Lenders use your credit score to assess your creditworthiness – essentially, how likely you are to repay borrowed money. A higher credit score (typically FICO scores above 700) indicates a lower risk, making you eligible for lower interest rates. Conversely, a lower credit score suggests a higher risk, leading lenders to charge a higher APR to compensate for that risk.
Economic Conditions
The Federal Reserve’s federal funds rate directly influences the prime rate, which credit card issuers use as a benchmark. When the Fed raises rates, credit card APRs, especially variable ones, tend to follow suit. This is why you might see your APR increase even if your credit behavior hasn’t changed.
Card Type and Features
Some credit cards inherently come with higher APRs. Store-branded credit cards, for instance, often have higher rates compared to general-purpose cards from major banks. Cards with extensive rewards programs or other premium features might also have slightly higher APRs, as the benefits are essentially subsidized by the interest paid by those who carry a balance.
Promotional Offers and Introductory Rates
While attractive, introductory 0% APR offers eventually expire. The standard APR that kicks in after the promotional period can be quite high, sometimes even 24% or more. It’s crucial to know what that rate will be and have a plan to pay off your balance before the introductory period ends to truly avoid high credit card APR.
Proactive Strategies to Avoid a 24% APR
Now that we understand the ‘why,’ let’s focus on the ‘how.’ Here are practical, actionable strategies to help you avoid high credit card APR and manage your credit card debt effectively.
1. Pay Your Balance in Full Every Month
This is the golden rule of credit card management. If you pay your statement balance in full by the due date each month, you won’t be charged any interest on new purchases. This completely sidesteps the issue of high APRs, regardless of what your card’s rate is. It’s the most effective way to avoid high credit card APR.
Anúncios
2. Improve Your Credit Score
A higher credit score opens the door to lower interest rates. Here’s how to boost it:
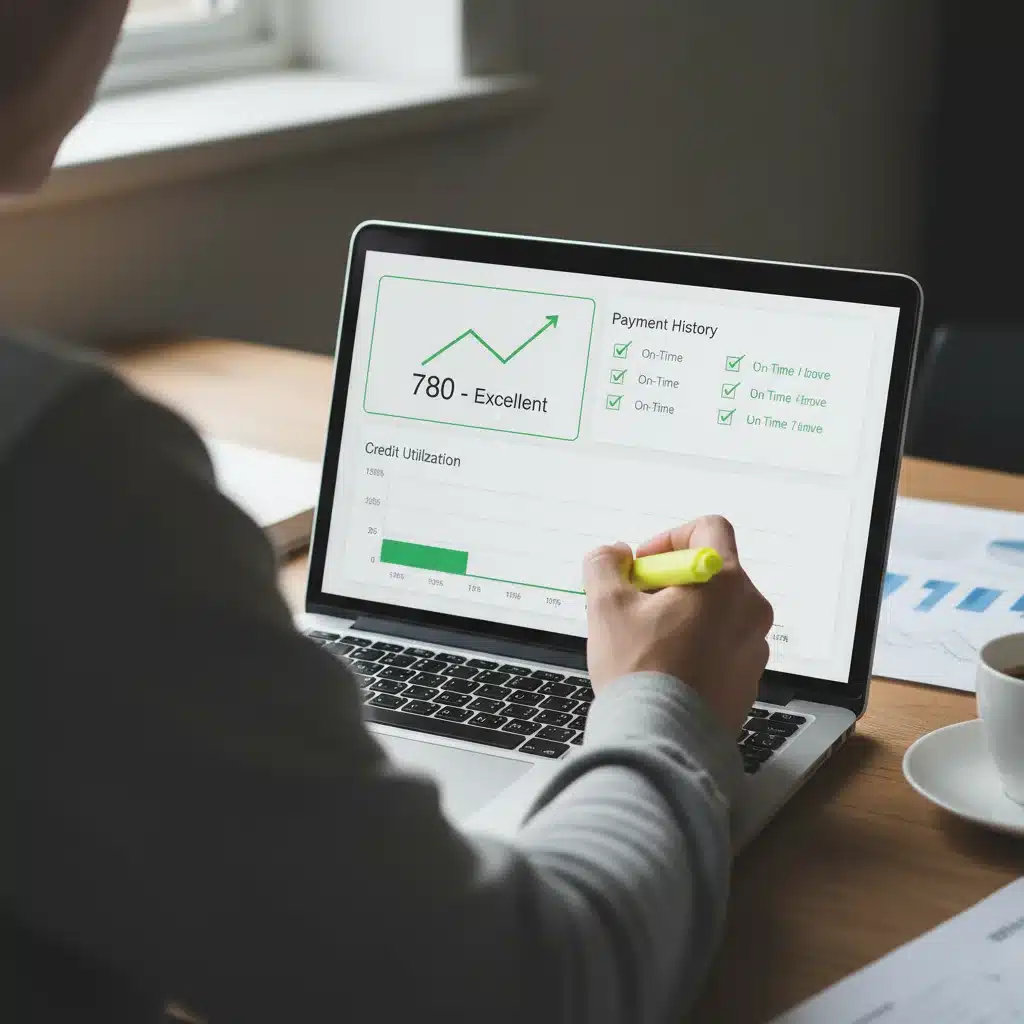
- Make all payments on time: Payment history is the most significant factor in your credit score.
- Keep credit utilization low: This refers to the amount of credit you’re using compared to your total available credit. Aim to keep it below 30%, ideally even lower (10% is excellent).
- Don’t close old accounts: Older accounts contribute to a longer credit history, which is positive for your score.
- Limit new credit applications: Each hard inquiry can temporarily ding your score. Only apply for credit when you truly need it.
- Regularly check your credit report: Dispute any errors immediately. You can get a free report from AnnualCreditReport.com.
3. Negotiate a Lower Interest Rate
It might sound too good to be true, but many card issuers are willing to negotiate. If you have a good payment history and an improved credit score, call your credit card company and ask for a lower APR. Be polite, explain your situation, and highlight your loyalty. Even a few percentage points can make a significant difference in the long run and help you avoid high credit card APR.
4. Utilize 0% APR Balance Transfer Offers Strategically
If you’re carrying a high-interest balance, a 0% APR balance transfer card can be a lifesaver. This allows you to transfer your existing debt to a new card that offers 0% interest for an introductory period (e.g., 12-18 months). This gives you a window to pay down a significant portion of your principal without interest charges.
Crucial considerations:
- Transfer fees: Most balance transfers come with a fee, typically 3-5% of the transferred amount. Factor this into your calculations.
- Plan to pay it off: Have a concrete plan to pay off the balance before the 0% period expires. If you don’t, you’ll be stuck with a potentially high standard APR on the remaining balance.
- New purchases: Avoid making new purchases on the balance transfer card during the promotional period, as these may not be subject to the 0% APR.
5. Consolidate Debt with a Personal Loan
For some, a personal loan with a fixed, lower interest rate can be a better option than a balance transfer. Personal loans often have lower interest rates than high-APR credit cards, and they come with a fixed repayment schedule, making it easier to budget and see an end to your debt. This is another excellent method to avoid high credit card APR.
6. Budget and Track Your Spending
Understanding where your money goes is fundamental to financial control. Create a realistic budget and stick to it. Identify areas where you can cut back to free up more money for debt repayment. Tools like budgeting apps, spreadsheets, or even a simple pen and paper can be incredibly effective. The less you rely on your credit card for everyday expenses, the less likely you are to accrue interest.
7. Set Up Automatic Payments
Even if you can’t pay your balance in full, always make at least the minimum payment on time. Setting up automatic payments ensures you never miss a due date, which prevents late fees and, more importantly, avoids triggering a penalty APR that can send your interest rate skyrocketing. This is a simple yet powerful way to avoid high credit card APR.
8. Understand Your Card’s Terms and Conditions
Many people sign up for credit cards without fully reading the fine print. Take the time to understand your card’s APR, grace period, fees, and how interest is calculated. Knowing these details empowers you to make informed decisions and avoid unpleasant surprises.
What to Do if You Already Have a 24% APR
If you’re already burdened with a 24% APR, don’t despair. The strategies mentioned above are still highly relevant and can help you mitigate the damage and eventually avoid high credit card APR.
- Prioritize High-Interest Debt: Use the “debt avalanche” method, where you focus on paying off the card with the highest interest rate first, while making minimum payments on others. Once that’s paid off, roll those payments into the next highest interest card.
- Increase Payments Beyond the Minimum: Even an extra $20 or $50 each month can significantly reduce the amount of interest you pay over the life of the debt.
- Consider Credit Counseling: If you feel overwhelmed, a non-profit credit counseling agency can help you create a debt management plan, negotiate with creditors, and provide education on financial literacy.
- Emergency Fund First: Before aggressively paying down debt, ensure you have a small emergency fund (e.g., $1,000) to cover unexpected expenses. This prevents you from relying on your high-APR credit card when emergencies arise.
Choosing the Right Credit Card to Avoid High APR
When applying for new credit, be strategic. Don’t just pick the card with the flashiest rewards. Consider these factors to help you avoid high credit card APR from the outset:
- Compare APRs: Always compare the standard purchase APRs across different cards. If you anticipate carrying a balance occasionally, a lower APR is more beneficial than high rewards.
- Look for Fixed vs. Variable Rates: Most credit cards have variable APRs tied to the prime rate. While less common, some cards offer fixed rates, which provide more predictability, though they might be slightly higher initially.
- Read Reviews: Look for reviews from other cardholders to understand their experiences with customer service, fees, and how interest rate changes are handled.
- Assess Your Needs: If you always pay in full, rewards and benefits might be more important than a low APR. If you sometimes carry a balance, a low APR should be a top priority.
For those with excellent credit, there are many cards offering competitive, low APRs, and even some that come with a 0% introductory APR for a substantial period. Leveraging your good credit is key to securing these favorable terms and ensuring you avoid high credit card APR.
The Long-Term Impact of High APRs
The cumulative effect of a 24% APR can be staggering. It can:
- Increase Debt Burden: A significant portion of your payments goes to interest, making it harder to reduce your principal balance.
- Hinder Financial Goals: Money spent on high interest could otherwise be saved for a down payment, retirement, or investments.
- Damage Credit Score: Carrying high balances due to accrued interest can increase your credit utilization, negatively impacting your credit score.
- Cause Stress: Financial stress is a major contributor to overall well-being. Avoiding high APRs can lead to greater peace of mind.
Understanding these long-term impacts reinforces the importance of actively working to avoid high credit card APR and manage your credit responsibly.
Conclusion: Taking Control of Your Credit Card Destiny
Credit cards are powerful financial tools, but their power comes with responsibility. A 24% APR can be a formidable foe, eroding your financial progress and trapping you in a cycle of debt. However, by understanding how interest rates work, improving your credit score, being proactive in negotiating rates, and making smart choices about how you use and choose your cards, you can effectively avoid high credit card APR.
The journey to lower interest rates and better financial health is ongoing. It requires discipline, education, and a commitment to responsible financial habits. Start today by reviewing your current credit card statements, checking your credit report, and implementing the strategies outlined in this article. Take control, and you’ll not only avoid a 24% APR but also build a stronger, more secure financial future.
Frequently Asked Questions About High Credit Card APRs
Q: What is a good credit card APR?
A: A ‘good’ APR depends on your creditworthiness and market conditions. For individuals with excellent credit, APRs can be as low as 15-18%. Anything below 20% is generally considered reasonable, while 24% or higher is on the higher end.
Q: Can my credit card APR change?
A: Yes, most credit cards have variable APRs, meaning they can change based on the prime rate. Your APR can also increase if you trigger a penalty APR due to late payments or other violations of your cardholder agreement.
Q: Is it better to pay off a credit card or save money?
A: Generally, if your credit card APR is high (e.g., 24%), it’s almost always better to pay off that high-interest debt first. The guaranteed return from avoiding interest payments usually far outweighs what you could earn in a savings account. However, always ensure you have a small emergency fund before aggressively paying down debt.
Q: How does credit utilization affect my APR?
A: While credit utilization directly impacts your credit score, which in turn influences the APRs you’re offered on new credit, it doesn’t typically change the APR on an existing card unless you trigger a penalty APR due to other factors. However, keeping utilization low is crucial for improving your score and qualifying for better rates in the future, helping you to avoid high credit card APR.
Q: What is the average credit card APR?
A: The average credit card APR fluctuates but often hovers around 20-22%. However, this is just an average, and individual rates can vary significantly based on credit scores and market conditions.