Smart Budgeting: Allocating 30% of Your Income for Housing in the Current U.S. Economy
In the dynamic and often challenging landscape of the current U.S. economy, managing personal finances effectively has become more crucial than ever. For many, the largest single expenditure is housing. The long-standing financial guideline suggests that no more than 30% of one’s gross income should be allocated to housing costs. This benchmark, often referred to as the 30% housing rule, serves as a cornerstone for financial stability and prudent budgeting. But how realistic is this guideline in today’s economic climate, and more importantly, how can individuals and families successfully adhere to it? This comprehensive guide delves into the intricacies of allocating 30% housing budget, offering practical strategies, insights, and actionable steps to navigate the complexities of the U.S. housing market and achieve financial peace of mind.
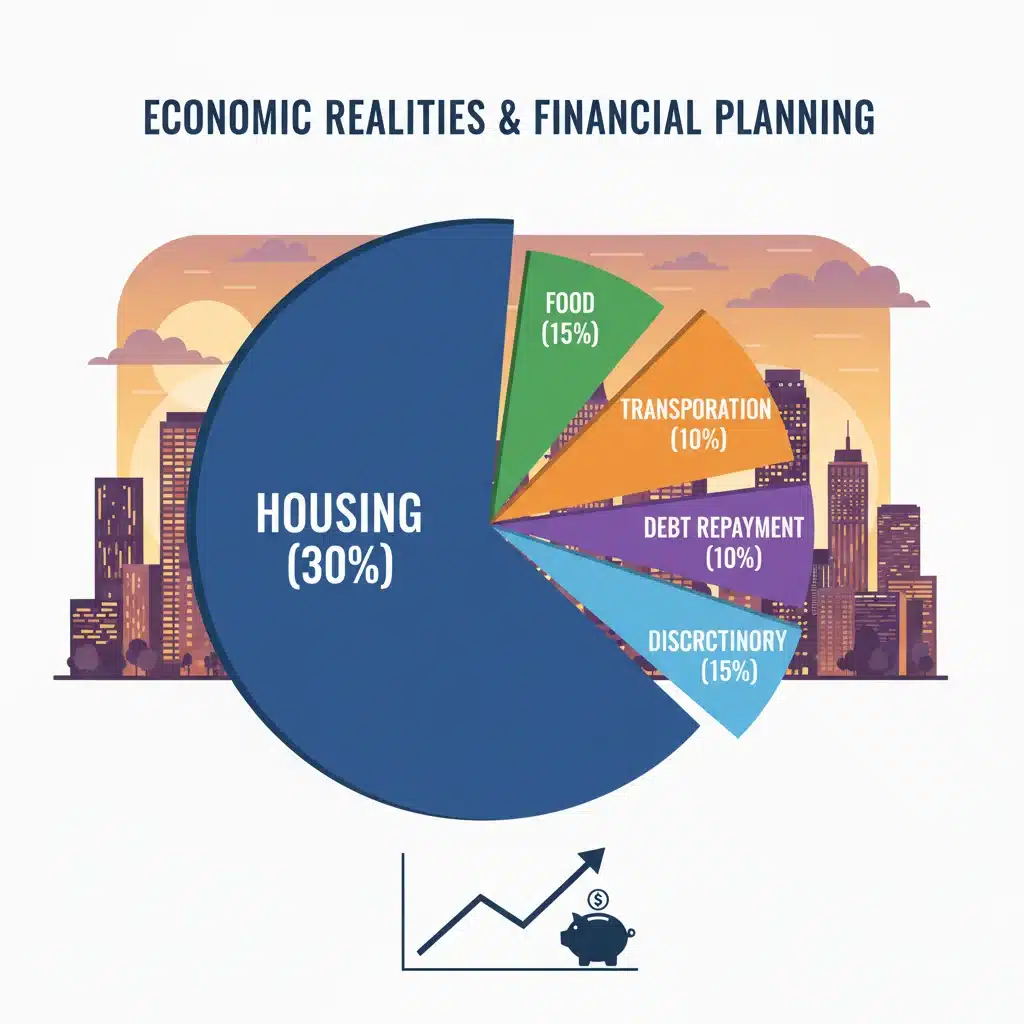
The concept of the 30% housing rule originated decades ago as a simple way to prevent households from becoming ‘housing cost-burdened.’ When more than 30% of income goes towards housing, it can severely limit a household’s ability to afford other necessities like food, healthcare, transportation, and savings. In an era marked by fluctuating interest rates, inflation, and a highly competitive housing market, understanding and implementing a 30% housing budget is not just a recommendation; it’s a critical component of sustainable financial health. This article will explore the historical context of the 30% rule, analyze its relevance in the current economic environment, and provide a detailed roadmap for making it work for you, regardless of your income level or location within the U.S.
Understanding the 30% Housing Rule: A Foundation for Financial Stability
The 30% housing rule is a widely accepted financial guideline that suggests your total housing expenses, including rent or mortgage payments, property taxes, and insurance, should not exceed 30% of your gross monthly income. This rule is often cited by financial advisors, lenders, and housing authorities as a key indicator of affordability. Adhering to a 30% housing budget helps ensure that you have sufficient funds remaining for other essential expenditures and allows for savings and discretionary spending, preventing financial strain and promoting long-term economic well-being.
Anúncios
Historical Context and Evolution of the 30% Rule
The origins of the 30% rule can be traced back to the 1930s, specifically to the National Housing Act of 1937, which established the public housing program. At that time, it was determined that families should pay no more than 20% of their income for housing. Over the decades, as economic conditions shifted and housing costs rose, this threshold gradually increased. By the 1980s, the U.S. Department of Housing and Urban Development (HUD) codified the 30% guideline, using it to define ‘housing cost-burdened’ households. This evolution reflects changing economic realities and the increasing challenge of housing affordability.
Why 30%? The Rationale Behind the Guideline
The 30% figure is not arbitrary; it’s based on extensive research and observation of household spending patterns. When housing costs exceed this percentage, households often find themselves making difficult trade-offs, such as cutting back on food, healthcare, or education. It can also make it challenging to save for emergencies, retirement, or other financial goals. The 30% housing budget is designed to strike a balance, allowing individuals and families to secure adequate shelter without sacrificing other critical aspects of their financial lives. It serves as a practical ceiling to maintain financial flexibility and avoid the precarious position of being ‘house poor.’
The Current U.S. Economic Landscape and Housing Affordability
The current U.S. economy presents a complex picture for housing affordability. Factors such as inflation, rising interest rates, and a tight housing supply have significantly impacted both rental and homeownership markets. Understanding these economic forces is crucial for anyone attempting to adhere to a 30% housing budget.
Anúncios
Inflation and Its Impact on Housing Costs
Persistent inflation has driven up the costs of nearly everything, and housing is no exception. Construction costs for new homes have increased due to higher material and labor prices. For renters, landlords often pass on increased operational costs through higher rents. For homeowners, property taxes and insurance premiums have also seen significant hikes. These inflationary pressures make it harder to keep housing expenses within the 30% threshold, especially for those whose incomes haven’t kept pace with the rising cost of living.
Rising Interest Rates and Mortgage Affordability
To combat inflation, the Federal Reserve has raised interest rates multiple times, leading to higher mortgage rates. A higher interest rate directly translates to a larger monthly mortgage payment for the same loan amount, reducing purchasing power for prospective homebuyers. This means that to stay within a 30% housing budget, buyers might need to look at less expensive homes or make larger down payments, which can be challenging in a market where home prices remain elevated.
The Supply-Demand Imbalance in the Housing Market
A significant factor contributing to high housing costs is the persistent imbalance between supply and demand. There simply aren’t enough homes available to meet the current demand, particularly in desirable urban and suburban areas. This scarcity drives up both home prices and rental rates. For individuals and families striving for a 30% housing budget, this competitive market often means facing higher prices and fewer affordable options, requiring more strategic planning and sometimes compromise on location or size.
Strategies for Achieving a 30% Housing Budget
Despite the economic challenges, achieving and maintaining a 30% housing budget is still possible with careful planning and strategic decision-making. Here are some actionable strategies to help you align your housing costs with this important financial guideline.
1. Accurate Income Assessment
The first step is to accurately calculate your gross monthly income. This is your total income before taxes and deductions. Be realistic and include all consistent sources of income. If your income fluctuates, use a conservative average to avoid overestimating your budget. Once you have this figure, multiply it by 0.30 (30%) to determine your maximum target housing expenditure.
2. Comprehensive Housing Cost Calculation
It’s crucial to include all housing-related expenses in your calculation, not just your rent or mortgage payment. For renters, this includes rent, renter’s insurance, and any mandatory HOA or utility fees. For homeowners, this means mortgage principal and interest, property taxes, homeowner’s insurance, private mortgage insurance (PMI) if applicable, and homeowner’s association (HOA) fees. Don’t forget to factor in average utility costs (electricity, gas, water, internet) if they are a significant and consistent part of your monthly housing outlay. A holistic view ensures you’re truly adhering to the 30% housing budget.
3. Budgeting and Tracking Your Spending
Once you know your target housing budget, integrate it into a comprehensive personal budget. Use budgeting apps, spreadsheets, or even pen and paper to track all your income and expenses. This will help you identify areas where you might be overspending and where you can cut back to free up more funds for housing or other financial goals. Regularly reviewing your budget ensures you stay on track with your 30% housing budget and other financial objectives.
4. Exploring Affordable Housing Options
If your current housing costs exceed the 30% guideline, or if you’re looking for new housing, explore more affordable options. This might involve:
- Downsizing: Moving to a smaller apartment or home.
- Relocation: Considering areas with lower costs of living, even if it means a longer commute or moving to a different city/state.
- Roommates/Housemates: Sharing living expenses can significantly reduce individual housing costs.
- Negotiating Rent: In some rental markets, especially during off-peak seasons, there might be room to negotiate rent with landlords.
- Exploring Government Programs: Look into local, state, and federal housing assistance programs if you qualify.
5. Increasing Your Income
Sometimes, the most direct way to make the 30% housing budget work is to increase your income. This could involve:
- Seeking a raise or promotion: Demonstrating your value at your current job.
- Taking on a side hustle: Utilizing your skills for additional income streams.
- Investing in career development: Acquiring new skills that lead to higher-paying opportunities.
- Optimizing investments: Ensuring your savings and investments are working efficiently for you.
Navigating Homeownership with a 30% Housing Budget
For aspiring homeowners, adhering to a 30% housing budget requires even more foresight and planning. The upfront costs and ongoing responsibilities of homeownership can be substantial.
Saving for a Down Payment
A larger down payment reduces the amount you need to borrow, which in turn lowers your monthly mortgage payment. Aiming for a 20% down payment can also help you avoid private mortgage insurance (PMI), further reducing your monthly housing costs and making it easier to stay within the 30% housing budget.
Understanding Mortgage Options
Explore different mortgage types (e.g., fixed-rate, adjustable-rate, FHA, VA) and understand how they impact your monthly payments and long-term costs. While ARMs might offer lower initial payments, fixed-rate mortgages provide stability. Work with a reputable lender to find the best option for your financial situation, always keeping the 30% housing budget in mind.
Factoring in Hidden Costs of Homeownership
Beyond the mortgage, property taxes, and insurance, homeowners face other expenses. These include maintenance, repairs, utilities, and potential HOA fees. It’s wise to budget an additional 1-2% of the home’s value annually for these unexpected costs. Ignoring these ‘hidden’ costs can quickly push your total housing expenditure above the 30% threshold.
The Flexibility of the 30% Rule: When to Bend (or Break) It
While the 30% housing budget is a valuable guideline, it’s not a rigid law. There are situations where it might be appropriate to deviate slightly, especially in high-cost-of-living areas or for individuals with unique financial circumstances.
High-Cost-of-Living Areas
In cities like New York, San Francisco, or Honolulu, where housing costs are exceptionally high, adhering strictly to the 30% rule can be nearly impossible for many. In such cases, a slightly higher percentage (e.g., 35-40%) might be unavoidable. However, if you exceed this, it becomes even more critical to compensate by cutting back significantly on other discretionary spending and ensuring robust savings in other areas of your budget.
High Income Earners
For individuals with very high incomes, spending 30% on housing might still leave ample funds for all other expenses and savings. In these scenarios, allocating a slightly higher percentage to housing might be a conscious lifestyle choice that doesn’t jeopardize financial stability. The key is to ensure that all other financial goals, such as retirement savings and emergency funds, are still being met.
Low Income Earners and Financial Assistance
Conversely, for low-income earners, even 30% of their gross income might not be enough to secure safe and adequate housing in many markets. This is where government assistance programs, subsidies, and non-profit organizations play a vital role. For those struggling to meet the 30% housing budget, exploring these resources is a crucial step towards housing stability.
Temporary Situations and Future Earning Potential
Sometimes, exceeding the 30% rule might be a temporary situation, perhaps due to a new job in a more expensive area with anticipated salary increases, or during a period of education or training that will lead to higher earnings. In these cases, it’s important to have a clear plan for how and when you will bring your housing costs back into alignment with your overall financial goals.
The Broader Impact of Housing Affordability on the U.S. Economy
The ability of a significant portion of the population to maintain a 30% housing budget has far-reaching implications for the overall U.S. economy. Housing affordability affects not just individual households but also local economies, labor markets, and social equity.
Economic Growth and Consumer Spending
When a large percentage of household income is consumed by housing costs, it leaves less money for other goods and services, which can dampen consumer spending and slow economic growth. Conversely, when housing is affordable, households have more disposable income, stimulating local businesses and contributing to a healthier economy. The struggle to maintain a 30% housing budget for many directly impacts their ability to contribute to the broader economy.
Labor Mobility and Workforce Development
High housing costs in job centers can deter workers from moving to areas with better employment opportunities, leading to labor shortages and hindering economic development. When housing is more accessible within a reasonable 30% housing budget, it facilitates labor mobility, allowing workers to move to where their skills are most needed, benefiting both individuals and industries.
Social Equity and Community Well-being
Housing affordability is a critical component of social equity. When housing is unaffordable, it disproportionately affects low-income individuals and marginalized communities, exacerbating wealth inequality and limiting access to quality education, healthcare, and job opportunities. Policies and strategies that support the attainment of a 30% housing budget for all contribute to more equitable and resilient communities.
Tools and Resources to Help Manage Your Housing Budget
Successfully adhering to a 30% housing budget often involves leveraging various financial tools and resources. Here’s a look at some of the most helpful options available today.
Budgeting Apps and Software
Modern technology offers a plethora of budgeting apps (e.g., Mint, YNAB, Personal Capital) that can help you track your income and expenses, categorize spending, and visualize your financial health. These tools can automate much of the budgeting process, making it easier to monitor your housing costs relative to your income and identify areas for adjustment to maintain your 30% housing budget.
Financial Advisors and Housing Counselors
For more personalized guidance, consider consulting a financial advisor or a HUD-approved housing counselor. These professionals can provide tailored advice based on your specific financial situation, help you create a realistic budget, explore mortgage options, and even assist with credit repair, all aimed at helping you achieve and sustain your 30% housing budget.
Online Calculators and Worksheets
Numerous free online calculators can help you determine how much you can afford for housing, calculate mortgage payments, and assess the impact of different interest rates or down payments. These tools are excellent for preliminary planning and understanding the financial implications of various housing decisions, ensuring you stay within your desired 30% housing budget.
Government and Non-Profit Housing Programs
Explore programs offered by federal, state, and local governments, as well as non-profit organizations. These can include rental assistance, first-time homebuyer programs, down payment assistance, and affordable housing initiatives. Such programs can significantly reduce housing costs for eligible individuals and families, making the 30% housing budget more attainable.
Long-Term Financial Planning Beyond the 30% Rule
While a 30% housing budget is a crucial short-to-medium-term goal, it’s also essential to integrate it into your broader long-term financial planning. Housing decisions today have ripple effects on your financial future.
Building an Emergency Fund
Regardless of your housing situation, having a robust emergency fund (typically 3-6 months of living expenses) is paramount. This fund acts as a buffer against unexpected life events, such as job loss, medical emergencies, or significant home repairs, preventing you from falling behind on your housing payments and jeopardizing your 30% housing budget.
Saving for Retirement and Other Goals
Ensuring your housing costs are manageable allows you to allocate sufficient funds to retirement accounts (401k, IRA), college savings, and other long-term financial goals. A balanced budget, with housing comfortably within the 30% guideline, provides the flexibility to invest in your future.
Debt Management
High levels of consumer debt (credit cards, personal loans) can strain your finances, even if your housing costs are within the 30% threshold. Prioritizing debt reduction, especially high-interest debt, can free up more income, making your overall financial picture more stable and resilient, and making it easier to maintain your 30% housing budget without stress.
Conclusion: Mastering Your 30% Housing Budget in a Changing Economy
The journey to financial stability in the current U.S. economy often begins with mastering your housing costs. The 30% housing budget rule, while a guideline, remains a powerful tool for achieving and maintaining financial health. It encourages responsible spending, promotes savings, and helps prevent the stress of being housing-cost-burdened. By understanding the economic forces at play, employing strategic budgeting techniques, exploring all available options, and engaging in proactive financial planning, you can successfully navigate the complexities of the housing market.
Whether you are a renter or a homeowner, an aspiring first-time buyer, or simply looking to optimize your current living situation, committing to the principles behind the 30% housing budget will empower you to make informed decisions that support your long-term financial well-being. It requires discipline, continuous monitoring, and sometimes, difficult choices, but the peace of mind and financial freedom that come with it are invaluable. Start assessing your housing costs today, implement these strategies, and take control of your financial future in the evolving U.S. economic landscape.