Maximize Savings: 4.5% Interest Rate Accounts in 2026 U.S.
Anúncios
Navigating the 4.5% Interest Rate Landscape for Savings Accounts: A 2026 Guide for U.S. Savers
In the dynamic world of personal finance, finding the right place for your hard-earned money can make a significant difference in its growth. For U.S. savers, the prospect of securing a 4.5% savings accounts interest rate is an exciting one, offering a substantial return compared to traditional accounts. As we look towards 2026, understanding where to find these lucrative opportunities, what factors influence them, and how to maximize their benefits becomes paramount. This comprehensive guide will delve into the intricacies of high-yield savings accounts, specifically focusing on those offering a compelling 4.5% interest rate, and equip you with the knowledge to make informed financial decisions.
The financial landscape is constantly evolving, influenced by economic indicators, Federal Reserve policies, and competitive pressures among financial institutions. While a 4.5% interest rate might seem ambitious to some, it’s a very real possibility in certain market conditions, particularly with online banks and credit unions vying for deposits. This article will not only identify potential avenues for such rates but also provide a strategic framework for evaluating and selecting the best 4.5% savings accounts for your individual financial goals.
Understanding High-Yield Savings Accounts and the 4.5% Threshold
Before diving into specific recommendations, it’s crucial to grasp what high-yield savings accounts (HYSAs) are and why a 4.5% savings accounts rate is noteworthy. Traditional brick-and-mortar banks often offer meager interest rates, sometimes barely keeping pace with inflation. HYSAs, typically offered by online banks, operate with lower overheads, allowing them to pass on greater savings to their customers in the form of higher interest rates. A 4.5% APY (Annual Percentage Yield) means that for every $1,000 you deposit, you would earn $45 in interest over a year, assuming the rate remains constant and interest is compounded. This significantly accelerates wealth accumulation compared to accounts offering 0.5% or less.
Anúncios
Several factors contribute to the availability of such attractive rates. The Federal Reserve’s federal funds rate plays a pivotal role, as it influences the interest rates banks charge each other for overnight lending. When the federal funds rate is higher, banks are generally able to offer higher interest rates on deposits. Additionally, competition among online banks, their need to attract new deposits, and their lower operating costs all contribute to the existence of competitive rates like 4.5% savings accounts.
It’s important to differentiate between advertised rates and actual APY. Always look for the APY, as it reflects the true annual rate of return, taking into account compounding interest. While a rate of 4.5% is excellent, understanding the nuances of how interest is calculated and applied is key to maximizing your earnings.
Where to Find 4.5% Savings Accounts in 2026 U.S.
Identifying financial institutions offering a 4.5% savings accounts rate in 2026 will require diligence, as rates can fluctuate. However, certain types of institutions are consistently at the forefront of offering competitive HYSAs. Online-only banks are usually your best bet. Without the overhead of physical branches, they can afford to offer higher rates. Examples of such institutions often include:
Anúncios
- Digital Banks: These include well-known names and emerging fintech companies that operate entirely online. They often leverage technology to provide seamless banking experiences and attractive rates.
- Credit Unions: Member-owned financial cooperatives sometimes offer highly competitive rates, especially to their members, as their primary goal isn’t profit maximization but serving their members.
- Brokerage Firms with Banking Arms: Some investment firms have expanded into banking services, offering HYSAs to attract and retain clients, often with competitive rates.
To pinpoint specific institutions offering a 4.5% savings accounts rate, you’ll need to regularly check:
- Online Rate Comparison Websites: Websites dedicated to comparing savings account rates are invaluable resources. They aggregate data from various banks and credit unions, making it easier to spot top-tier offers.
- Direct Bank Websites: Always verify the rates directly on the financial institution’s website, as comparison sites might not always be updated in real-time.
- Financial News Outlets: Industry news and financial publications often highlight institutions offering leading interest rates.
Remember that rates are subject to change. What might be a 4.5% savings accounts rate today could shift in the future, so staying informed is crucial for long-term savings strategies.
Key Features to Consider Beyond the Interest Rate
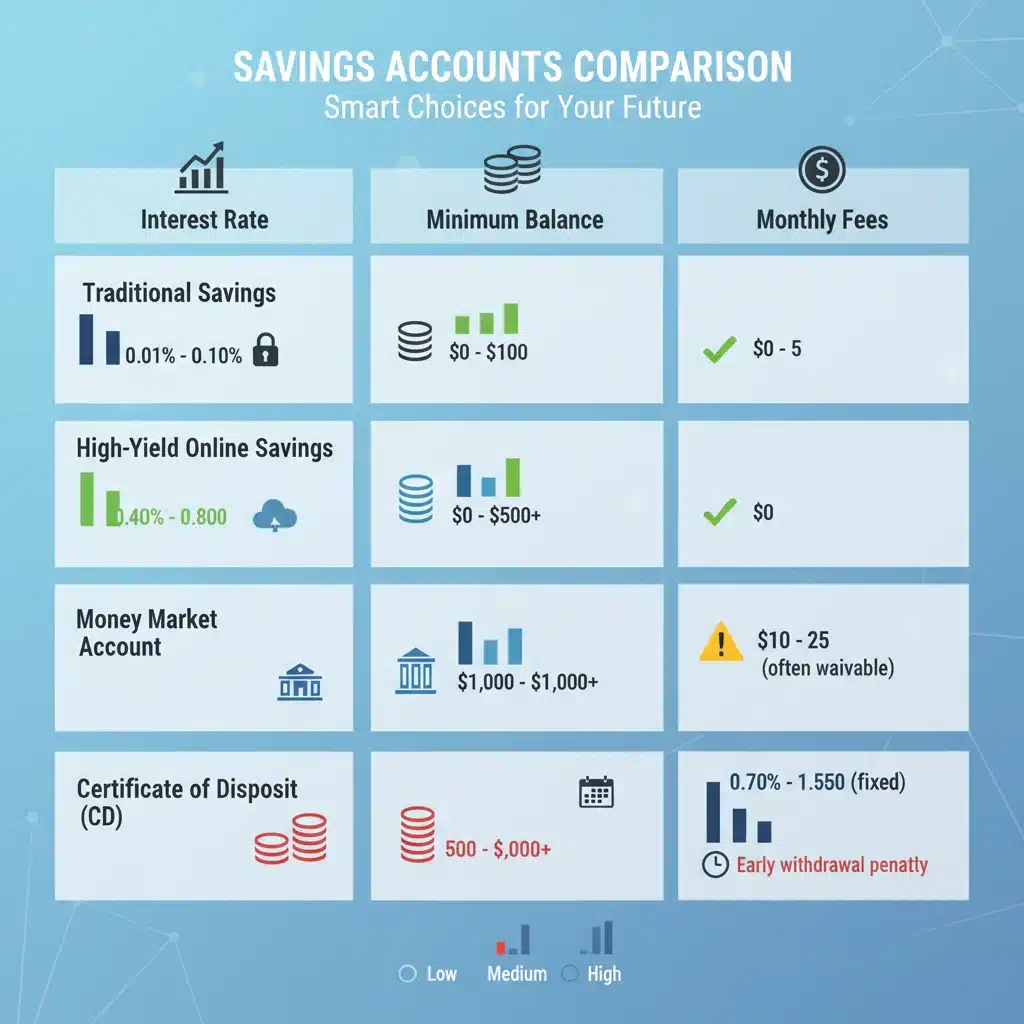
While a 4.5% savings accounts rate is undoubtedly attractive, it’s not the only factor to consider when choosing where to park your money. A holistic approach involves evaluating several other features to ensure the account meets your broader financial needs:
Minimum Balance Requirements
Some HYSAs require a minimum balance to earn the advertised APY or to avoid monthly fees. Ensure you can comfortably meet these requirements. An account with a high interest rate but a minimum balance you can’t maintain might end up costing you more in fees than you earn in interest.
Fees and Charges
Scrutinize the fee schedule. Common fees include monthly maintenance fees (often waivable with direct deposit or minimum balance), overdraft fees, and wire transfer fees. The best 4.5% savings accounts will have minimal or no monthly fees, especially if you meet certain criteria.
Accessibility of Funds
While savings accounts are generally for money you don’t need immediate access to, you should still understand how easily you can withdraw funds. Online banks typically offer electronic transfers, ATM access (often through partner networks), and sometimes even physical checks. Confirm that the withdrawal methods align with your potential needs.
FDIC or NCUA Insurance
Always ensure your chosen institution is insured by the Federal Deposit Insurance Corporation (FDIC) for banks or the National Credit Union Administration (NCUA) for credit unions. This protects your deposits up to $250,000 per depositor, per institution, in case the financial institution fails. This is non-negotiable for any secure 4.5% savings accounts.
Online and Mobile Banking Experience
Since many high-yield accounts are offered by online banks, a robust and user-friendly online and mobile banking platform is essential. Look for features like easy account management, mobile check deposit, bill pay, and strong security protocols.
Customer Service
Even with digital banking, good customer service is vital. Check reviews for responsiveness and helpfulness. Knowing you can easily reach support if an issue arises provides peace of mind.
Strategies to Maximize Your 4.5% Savings Accounts Earnings
Simply opening a 4.5% savings accounts is the first step. To truly maximize your earnings, consider these strategies:
Automate Your Savings
Set up automatic transfers from your checking account to your high-yield savings account. Even small, consistent contributions add up significantly over time, especially with a 4.5% APY. This removes the temptation to spend the money and ensures steady growth.
Regularly Review Rates
Interest rates are dynamic. While you might secure a 4.5% savings accounts rate today, other institutions might offer higher rates in the future. Make it a habit to review top savings rates every few months. If you find a significantly better offer elsewhere, don’t hesitate to transfer your funds, assuming the new account meets all your other criteria.
Understand Compounding Interest
The magic of compounding interest means your interest earns interest. The more frequently interest is compounded (daily, monthly, quarterly), the faster your money grows. While most HYSAs compound daily or monthly, understanding this concept reinforces the benefit of starting early and saving consistently.
Tiered Accounts
Some HYSAs offer tiered interest rates, meaning you earn a higher rate on larger balances. If you have a substantial amount to save, look for a 4.5% savings accounts that rewards higher deposit amounts. However, be wary of tiers that only offer the high rate on a small portion of your balance, or require an unrealistic minimum.
Emergency Fund First
Before investing in riskier assets, prioritize building a robust emergency fund in a high-yield savings account. A 4.5% savings accounts is an ideal place for this money, providing liquidity and growth without market volatility. Aim for 3-6 months of living expenses.
The Economic Outlook and Interest Rates in 2026
Predicting interest rates accurately in 2026 is challenging, as it depends on a multitude of economic factors. However, we can make educated assumptions based on current trends and historical patterns. The Federal Reserve’s stance on inflation, employment, and economic growth will be the primary drivers. If inflation remains elevated, the Fed might keep interest rates higher to cool the economy, which could translate to more attractive 4.5% savings accounts opportunities. Conversely, if the economy slows significantly, the Fed might lower rates to stimulate growth, potentially reducing HYSA rates.
Other factors include:
- Global Economic Conditions: International events can have ripple effects on the U.S. economy and interest rate policy.
- Bank Competition: The competitive landscape among online banks and traditional institutions will continue to influence offered rates. Intense competition could keep rates elevated even if the federal funds rate sees minor adjustments.
- Technological Advancements: Further innovation in fintech could lead to even more efficient banking models, allowing institutions to offer better rates to customers.
Savers should stay abreast of economic news and Federal Reserve announcements. Subscribing to financial newsletters and following reputable economic analysts can provide valuable insights into the future direction of interest rates and the potential for finding a 4.5% savings accounts.
Common Pitfalls to Avoid When Chasing High Interest Rates
While the pursuit of a 4.5% savings accounts is commendable, it’s essential to be aware of potential pitfalls:
"Teaser" Rates
Some institutions offer attractive introductory rates that revert to much lower rates after a few months. Always read the fine print to understand if the 4.5% APY is a permanent or temporary offer. A truly competitive 4.5% savings accounts will maintain its rate or adjust it based on broader market conditions, not just an introductory period.
Hidden Fees
As mentioned earlier, fees can erode your earnings. Be diligent in understanding all potential charges associated with the account. A high interest rate loses its appeal if it’s offset by numerous fees.
Over-reliance on Promotions
Don’t jump from bank to bank solely for short-term promotional rates. While it’s good to seek higher yields, constantly moving money can be time-consuming and might lead to missed opportunities if you’re not careful. Focus on institutions with a history of consistently offering strong rates for their 4.5% savings accounts.
Lack of FDIC/NCUA Insurance
Never deposit money into an account that isn’t federally insured. The allure of extremely high, unsustainable rates from uninsured entities is a major red flag and can lead to complete loss of principal. Always verify the insurance status.
Ignoring Your Financial Goals
A 4.5% savings accounts is an excellent tool, but it should align with your overall financial plan. If you need money for short-term expenses, liquidity might be more important than the absolute highest rate. If you’re saving for retirement, a savings account might be part of your strategy, but it shouldn’t be your only vehicle.
Alternative High-Yield Options to Consider Alongside a 4.5% Savings Accounts
While a 4.5% savings accounts offers a fantastic return for liquid cash, it’s beneficial to be aware of other high-yield options that might complement your savings strategy:
Certificates of Deposit (CDs)
CDs typically offer higher interest rates than savings accounts in exchange for locking up your money for a fixed term (e.g., 6 months, 1 year, 5 years). If you have money you know you won’t need for a specific period, a CD laddering strategy (investing in CDs of varying maturities) can provide both higher returns and some liquidity. In a rising interest rate environment, CD rates can sometimes surpass 4.5% savings accounts, especially for longer terms.
Money Market Accounts (MMAs)
MMAs share similarities with both savings and checking accounts. They often offer higher interest rates than traditional savings accounts and may come with check-writing privileges and debit cards. However, they might also have higher minimum balance requirements and transaction limits. Their rates are generally competitive with HYSAs, sometimes matching or exceeding a 4.5% savings accounts.
Short-Term Treasury Bills (T-Bills)
Issued by the U.S. Treasury, T-Bills are considered one of the safest investments. They mature in a year or less and can offer competitive yields, especially when the Federal Reserve is keeping interest rates high. While not a direct substitute for a savings account, they can be a great option for short-term cash you want to keep safe and earning interest.
Brokerage Cash Management Accounts
Many brokerage firms now offer cash management accounts that function similarly to HYSAs, often with competitive interest rates and integrated access to investment platforms. These can be a convenient option for those who already have investment accounts with a particular firm. The rates on these accounts can sometimes be very close to or even exceed a 4.5% savings accounts.
The Role of Technology in Finding and Managing High-Yield Accounts
Technology has revolutionized how we manage our finances, making it easier than ever to find and maintain a 4.5% savings accounts. Mobile banking apps provide instant access to your account balances, transaction history, and the ability to transfer funds with a few taps. Budgeting apps can integrate with your savings accounts, giving you a holistic view of your financial health and helping you track your progress towards savings goals.
Furthermore, AI-powered financial tools can analyze your spending habits and suggest ways to optimize your savings, potentially freeing up more money to contribute to your 4.5% savings accounts. Automated savings features, where apps round up your purchases to the nearest dollar and transfer the difference to your savings, can also contribute to passive growth.
Utilize online aggregators and comparison tools to swiftly identify the best rates. These platforms save you hours of research by compiling data from numerous financial institutions, allowing you to quickly compare APYs, minimums, and fees to find the ideal 4.5% savings accounts for your needs. Staying digitally savvy is no longer just a convenience; it’s a strategic advantage in maximizing your financial returns.
Conclusion: Securing Your Financial Future with 4.5% Savings Accounts
The pursuit of a 4.5% savings accounts in the U.S. for 2026 is a commendable financial goal. By understanding the landscape of high-yield savings accounts, knowing where to look for the best rates, and considering all relevant account features, you can significantly boost your financial growth. Remember to prioritize FDIC/NCUA insurance, be wary of hidden fees and teaser rates, and align your savings strategy with your overall financial objectives.
As the economic environment continues to evolve, staying informed and proactive will be your greatest assets. Regularly reviewing rates, automating your savings, and considering complementary high-yield options will ensure you are always making the most of your money. With careful planning and diligent execution, securing a 4.5% savings accounts can be a cornerstone of a robust and prosperous financial future.
Start your research today, compare options, and take concrete steps to ensure your savings are working as hard as they can for you. The journey to financial well-being is continuous, and leveraging the best available interest rates is a powerful step in the right direction.