U.S. Inflation at 4.2%: Strategies to Protect Your Purchasing Power This Quarter
Anúncios
U.S. Inflation at 4.2%: Strategies to Protect Your Purchasing Power This Quarter
The latest economic reports have sent ripples through the financial world: U.S. inflation has hit 4.2%. This significant rise presents a tangible challenge for consumers and investors alike, as the cost of living increases and the value of hard-earned money diminishes. Protecting your purchasing power in such an environment is not merely a financial goal; it’s a necessity. This comprehensive guide will delve into actionable strategies to help you navigate this inflationary period and safeguard your financial future this quarter.
Understanding the 4.2% Inflation Rate: What It Means for You
Before we explore protective measures, it’s crucial to understand the implications of a 4.2% inflation rate. Inflation, in simple terms, is the rate at which the general level of prices for goods and services is rising, and, consequently, the purchasing power of currency is falling. A 4.2% rate means that what cost $100 a year ago now costs $104.20. While this might seem like a small percentage, its cumulative effect over time can significantly erode your wealth.
Several factors contribute to such an increase, including supply chain disruptions, increased consumer demand following economic reopening, and expansionary monetary policies. For the average American, this means higher prices at the grocery store, increased utility bills, more expensive gasoline, and a general squeeze on household budgets. Understanding these dynamics is the first step toward formulating an effective strategy to protect purchasing power.
Revisiting Your Budget: The Foundation of Financial Resilience
In an inflationary environment, a meticulous review of your personal budget becomes paramount. Many people tend to set a budget and then forget it, but rising prices demand constant vigilance. This quarter, commit to a thorough re-evaluation of your income and expenses.
Anúncios
Identify and Cut Unnecessary Spending
Go through every line item in your budget. Are there subscriptions you no longer use? Can you reduce dining out frequency? Even small, consistent cuts can free up significant funds that can then be redirected towards more inflation-resistant investments or savings. Consider the ‘needs versus wants’ approach. While some expenses are non-negotiable, others offer flexibility. For instance, opting for generic brands over name brands for certain products can lead to noticeable savings over time.
Optimize Fixed Expenses
While variable expenses are easier to trim, don’t overlook fixed costs. Can you refinance your mortgage to a lower interest rate? Shop around for better insurance deals – car, home, or health. Even negotiating your internet or cable bill can yield savings. These might require more effort initially, but the long-term benefits are substantial in protecting your purchasing power.
Track Your Spending Religiously
Utilize budgeting apps or spreadsheets to track every dollar. This not only helps you identify areas for reduction but also makes you more conscious of your spending habits. Awareness is power, especially when inflation is eroding your money’s value.
Anúncios
Smart Investing: Your Shield Against Inflation
One of the most effective ways to protect purchasing power is through strategic investing. Simply holding cash in a savings account, especially with current interest rates often below the inflation rate, guarantees a loss in real value. Your money needs to work harder than inflation.
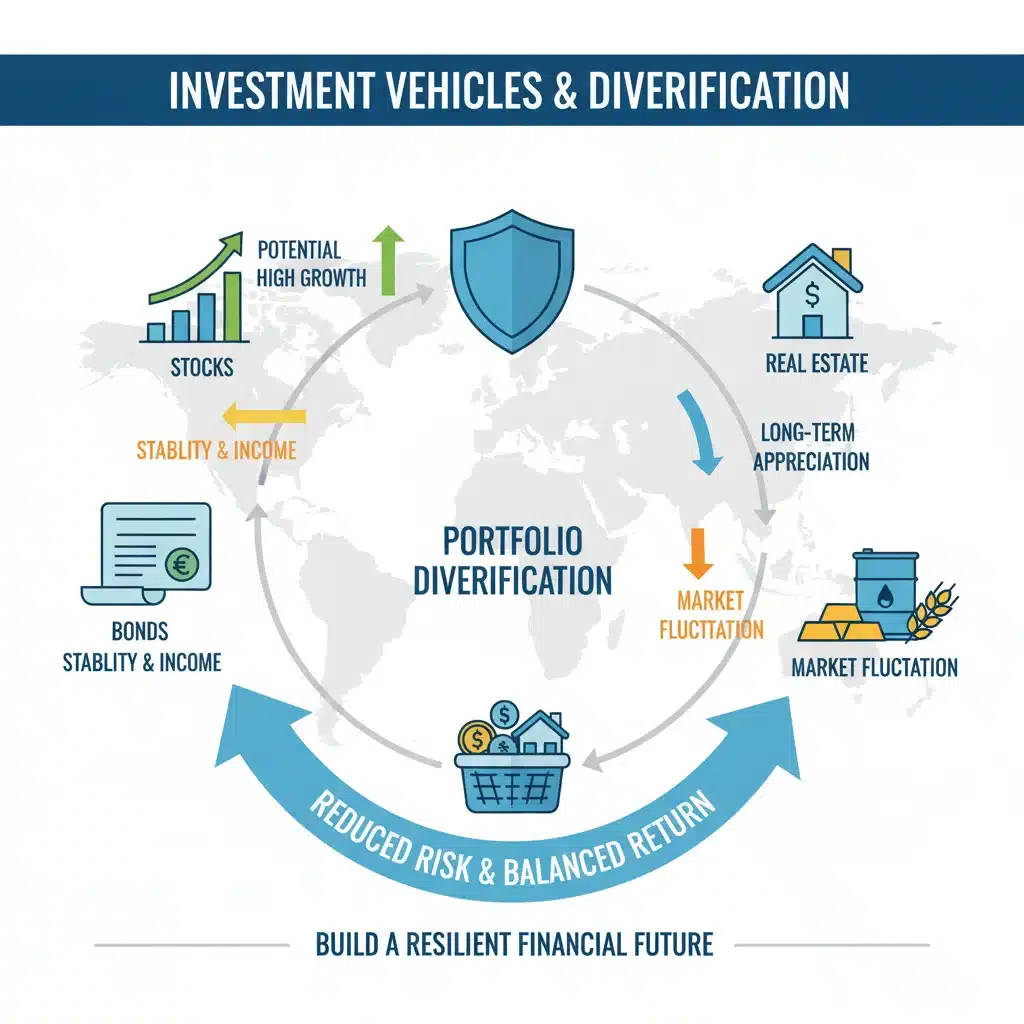
Inflation-Protected Securities (TIPS)
Treasury Inflation-Protected Securities (TIPS) are bonds issued by the U.S. Treasury that are indexed to inflation. Their principal value adjusts with the Consumer Price Index (CPI), meaning both the principal and interest payments rise with inflation. This makes them an excellent hedge against rising prices, offering a guaranteed return above inflation.
Real Estate
Historically, real estate has been a strong hedge against inflation. Property values and rental income tend to increase with inflation, making it a valuable asset to hold. If you own your home, its value may appreciate, offering some protection. For investors, rental properties can provide a steady income stream that adjusts with rising costs. However, it’s essential to consider the current market conditions and interest rates before making significant real estate investments.
Commodities
Commodities like gold, silver, oil, and agricultural products often perform well during inflationary periods. As the cost of goods rises, the price of the raw materials used to produce them also tends to increase. Gold, in particular, is often seen as a safe haven asset during economic uncertainty and inflationary pressures. Investing in commodity-focused ETFs or directly in physical commodities can offer diversification and a potential buffer against inflation.
Stocks with Pricing Power
Not all stocks are equal in an inflationary environment. Companies that possess ‘pricing power’ – the ability to raise prices without significantly impacting demand – tend to fare better. These are typically companies with strong brands, essential products or services, or those operating in industries with high barriers to entry. Look for companies in sectors like consumer staples, utilities, and healthcare. These businesses can pass on increased costs to consumers, thereby maintaining their profit margins and protecting your investment’s real value.
Dividend Stocks
Dividend-paying stocks can provide a regular income stream that can help offset the rising cost of living. Companies that consistently pay and ideally increase their dividends often demonstrate financial stability and strong cash flow, which can be particularly attractive during inflationary periods. Reinvesting these dividends can further compound your returns and help your portfolio grow faster than inflation.
Optimizing Your Debt Strategy
Inflation impacts debt differently depending on whether it’s fixed or variable rate. Understanding this distinction is crucial for managing your liabilities effectively.
Fixed-Rate Debt
If you have fixed-rate debt, such as a traditional mortgage or a fixed-rate personal loan, inflation can actually work in your favor. As the value of money decreases, the real value of your fixed debt payments also effectively decreases over time. This means you’re paying back your loan with money that is worth less than when you borrowed it. However, this doesn’t mean you should ignore fixed-rate debt; strategic repayment can still be beneficial.
Variable-Rate Debt
Variable-rate debt, like credit card balances or adjustable-rate mortgages, is more problematic during inflation. Central banks often raise interest rates to combat inflation, which in turn increases the cost of variable-rate debt. Prioritizing the repayment of high-interest variable-rate debt should be a top financial goal in an inflationary climate to prevent your payments from spiraling out of control.
Income Generation and Career Advancement
Your income is your most powerful tool to protect purchasing power. In an inflationary environment, it’s vital to ensure your income keeps pace with or ideally outpaces rising costs.
Negotiate for Raises
Don’t be afraid to ask for a raise that reflects both your contributions and the rising cost of living. Prepare by researching salary benchmarks for your role and industry, and highlight your achievements and value to the company. A cost-of-living adjustment (COLA) should be a standard expectation during periods of significant inflation.
Develop New Skills
Investing in your professional development can lead to higher earning potential. Acquire new skills that are in demand in your industry or explore opportunities in growing sectors. The more valuable your skills, the greater your leverage in salary negotiations and career advancement.
Explore Side Hustles or Passive Income Streams
Consider starting a side hustle or developing passive income streams. This could involve freelancing, consulting, selling products online, or investing in dividend stocks or rental properties. Diversifying your income sources provides a stronger financial buffer against inflation and enhances your overall financial security.
Strategic Savings and Emergency Funds
Maintaining an adequate emergency fund is always important, but its significance is amplified during inflationary periods. However, simply holding cash in a low-interest savings account might not be the best strategy.
High-Yield Savings Accounts
While still unlikely to beat 4.2% inflation, high-yield savings accounts offer better returns than traditional accounts. Look for online banks that typically provide more competitive interest rates. While your money might still lose some purchasing power, the loss will be mitigated, and your funds remain liquid for emergencies.
Short-Term CDs or Money Market Accounts
For funds you don’t need immediate access to but want to keep relatively liquid, consider short-term Certificates of Deposit (CDs) or money market accounts. These often offer slightly higher interest rates than savings accounts, though they may come with some restrictions on withdrawals.
Reviewing Your Insurance Policies
Inflation doesn’t just affect asset values; it also impacts the cost of replacing them. Reviewing your insurance policies is a crucial, often overlooked, step.
Homeowners Insurance
Ensure your homeowners insurance policy adequately covers the replacement cost of your home and its contents. Construction costs and material prices can rise significantly with inflation, so an older policy might leave you underinsured in the event of damage or loss. Speak with your insurance provider to adjust your coverage as needed.
Auto Insurance
Similarly, the cost of repairing or replacing vehicles can increase. While you might not need to adjust your liability coverage, consider reviewing your comprehensive and collision coverages to ensure they align with current vehicle values and repair costs.
Health Insurance
Healthcare costs are notoriously prone to inflation. While you might not directly control premium increases, understanding your policy’s coverage, deductibles, and out-of-pocket maximums is essential. Explore options during open enrollment periods to ensure you have the most cost-effective and comprehensive plan for your needs.
Lifestyle Adjustments and Frugality
Beyond financial instruments, adopting a more frugal mindset can significantly help protect your purchasing power.
Bulk Buying and Sales
When appropriate, buying non-perishable goods in bulk when they are on sale can lock in lower prices before inflation drives them higher. Always compare unit prices to ensure you’re getting a genuine deal.
Energy Efficiency
High energy costs are a direct consequence of inflation. Invest in energy-efficient appliances, seal drafts in your home, and be mindful of your electricity and heating/cooling usage. These small changes can add up to significant savings on utility bills.
DIY and Repair
Instead of immediately replacing items, consider repairing them yourself or finding cost-effective repair services. Learning basic DIY skills can save you money on home maintenance and other repairs, extending the life of your possessions.
Meal Planning and Cooking at Home
Food prices are a major component of inflation. Planning your meals, cooking at home, and bringing your lunch to work can drastically reduce your food expenses compared to dining out or relying on convenience foods. Utilizing coupons and shopping at discount grocery stores can further enhance these savings.
The Psychological Aspect of Inflation: Staying Calm and Rational
Inflation can be a source of anxiety, and fear can lead to impulsive financial decisions. It’s crucial to maintain a calm and rational approach.
Educate Yourself Continuously
Stay informed about economic trends and how inflation is evolving. Understanding the forces at play can help you make more informed decisions and reduce uncertainty. Follow reputable financial news sources and economists.
Avoid Panic Selling or Buying
Resist the urge to make drastic changes to your investment portfolio based on short-term market fluctuations. A well-diversified portfolio, constructed with long-term goals in mind, is your best defense. Similarly, avoid hoarding goods due to fear of future price increases, as this can lead to unnecessary waste and ties up capital.
Focus on Long-Term Goals
While immediate concerns about purchasing power are valid, don’t lose sight of your long-term financial objectives. Inflation is a cyclical phenomenon, and markets tend to recover. Continue to contribute to your retirement accounts and other long-term investments, leveraging strategies like dollar-cost averaging.
Consult a Financial Advisor
Navigating a complex economic landscape like the current inflationary period can be challenging. A qualified financial advisor can provide personalized guidance tailored to your specific financial situation, risk tolerance, and goals. They can help you:
- Assess your current financial health.
- Develop a customized investment strategy to combat inflation.
- Review and optimize your budget.
- Plan for retirement and other significant life events in an inflationary environment.
Seeking professional advice can offer peace of mind and help ensure your strategies are robust and effective.
Conclusion: Proactive Measures for a Resilient Financial Future
U.S. inflation at 4.2% is a significant economic event that demands attention and proactive measures. Protecting your purchasing power this quarter and beyond requires a multi-faceted approach: a rigorous review of your budget, strategic investments in inflation-resistant assets, smart debt management, continuous income growth, and prudent savings. By implementing these strategies, you can not only mitigate the negative effects of inflation but also strengthen your overall financial resilience. Remember, the goal is not just to survive inflation but to thrive by making your money work harder for you, ensuring your financial future remains secure.