Mastering 2026 Homeownership Costs: A Comprehensive Guide to Budgeting for Your Mortgage
The dream of homeownership remains a cornerstone of the American psyche, a symbol of stability, independence, and long-term financial growth. As we look ahead to 2026, prospective homebuyers and current homeowners alike are keenly interested in understanding the evolving landscape of 2026 homeownership costs. The housing market is dynamic, influenced by a myriad of economic factors, and being well-prepared is paramount to making sound financial decisions. This comprehensive guide will delve into every aspect of budgeting for a mortgage in 2026, from understanding interest rates and down payments to hidden expenses and future considerations, ensuring you are equipped to navigate the journey to homeownership successfully.
Understanding the 2026 Housing Market: What to Expect
Before diving into specific costs, it’s crucial to grasp the broader economic context that will shape the 2026 housing market. Several factors are expected to play significant roles:
Interest Rate Projections for 2026
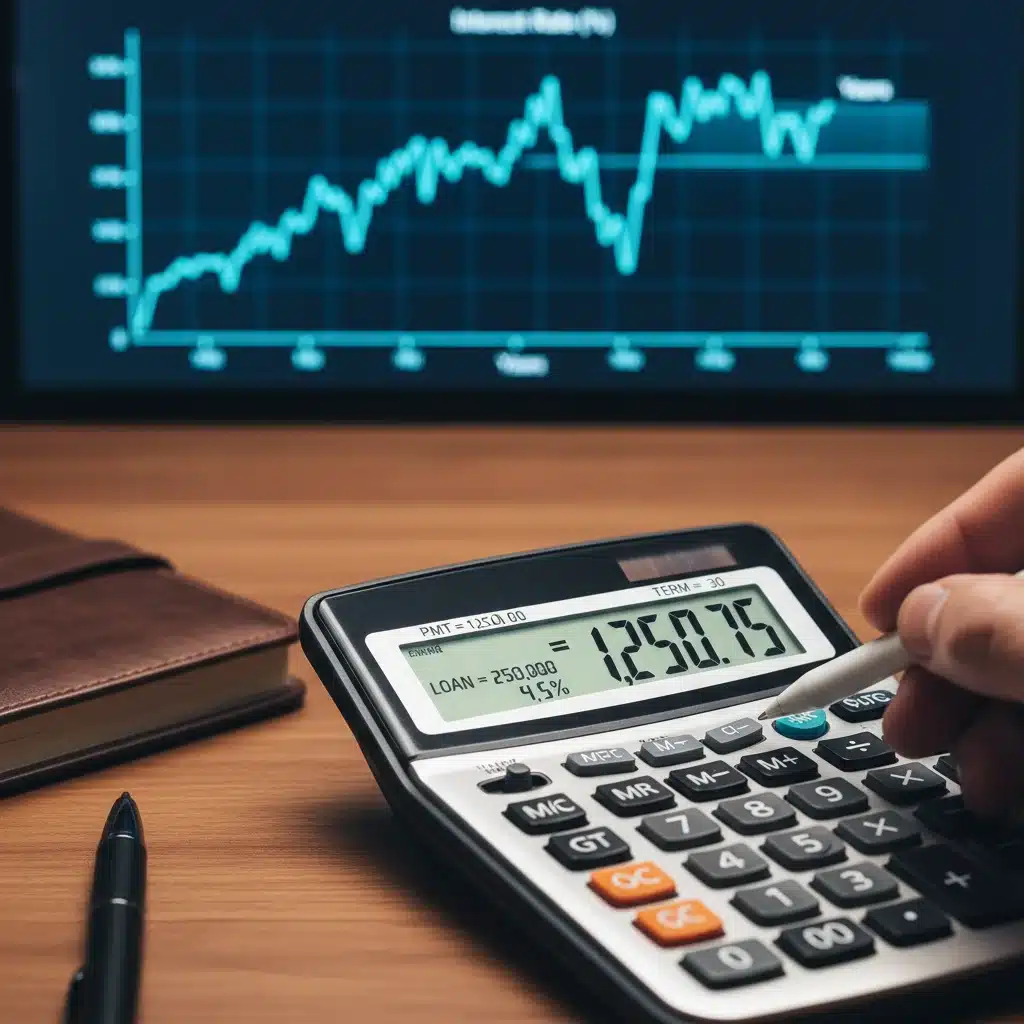
One of the most impactful elements of 2026 homeownership costs is the prevailing interest rate environment. Mortgage interest rates are influenced by federal monetary policy, inflation, and the overall health of the economy. While predictions can vary, many economists anticipate a period of stabilization, with potential for slight fluctuations. The Federal Reserve’s actions in response to inflation will be a key determinant. A slight increase could significantly impact monthly mortgage payments, while a decrease could make homeownership more accessible. It’s vital for prospective buyers to stay informed about these projections and understand how even a half-percentage point change can affect their long-term financial commitment.
Anúncios
Housing Inventory and Demand
The supply and demand dynamics of housing inventory will continue to influence home prices. If inventory remains low, prices could stay elevated, adding to overall 2026 homeownership costs. Conversely, an increase in new construction or a cooling of demand could lead to more stable or even slightly declining prices in some markets. Geographic location will play a critical role, with some regions experiencing more competitive markets than others. Researching local market trends is an indispensable step in your homebuying journey.
Economic Forecasts and Their Impact
Broader economic indicators, such as GDP growth, employment rates, and wage growth, will also shape the affordability of homes. A strong economy generally supports higher home prices and potentially higher interest rates, while a slowdown could lead to the opposite. Understanding these macroeconomic forces provides a foundation for realistic budgeting and financial planning for your 2026 homeownership costs.
The Core of 2026 Homeownership Costs: Your Mortgage
The mortgage is often the largest component of homeownership expenses. Breaking down its various elements is essential for effective budgeting.
Down Payment Strategies
The down payment is your initial equity in the home. While 20% is often recommended to avoid Private Mortgage Insurance (PMI), many loan programs allow for much lower down payments, sometimes as little as 3-5%. The size of your down payment directly impacts your loan amount and, consequently, your monthly mortgage payment. Saving aggressively for a down payment is a critical first step in managing your 2026 homeownership costs. Explore options like FHA loans, VA loans (for eligible veterans), and conventional loans with lower down payment requirements, but be mindful of the associated costs like PMI.
Understanding Mortgage Interest Rates
As mentioned, interest rates are paramount. A fixed-rate mortgage offers stability with consistent monthly payments, while an adjustable-rate mortgage (ARM) can offer lower initial rates but carries the risk of future increases. Carefully evaluate your risk tolerance and financial stability when choosing between these options. Even a small difference in interest rates can translate to tens of thousands of dollars over the life of a loan, making it a central focus when considering 2026 homeownership costs.
Principal and Interest: The Monthly Payment Breakdown
Your monthly mortgage payment is primarily composed of principal and interest. The principal portion reduces your outstanding loan balance, building equity over time. The interest portion is the cost of borrowing money. In the early years of a mortgage, a larger percentage of your payment goes towards interest. Understanding this amortization schedule can help you visualize your equity growth and long-term financial commitment. This fundamental component is a constant in 2026 homeownership costs.
Beyond the Mortgage: Other Significant 2026 Homeownership Costs
Many first-time homebuyers focus solely on the mortgage payment, overlooking other crucial expenses that contribute significantly to the overall cost of owning a home. These ‘hidden’ costs can quickly derail an unprepared budget.
Property Taxes: An Annual Burden
Property taxes are levied by local governments and are used to fund public services like schools, roads, and emergency services. These taxes can vary dramatically by location and can be a substantial portion of your monthly housing expense. They are often included in your escrow payment with your mortgage, but it’s important to understand how they are calculated and when they are due. Property tax assessments can also increase over time, impacting your future 2026 homeownership costs.
Homeowners Insurance: Protecting Your Investment
Homeowners insurance is a mandatory requirement for most mortgage lenders and protects your home and belongings from damage due to events like fire, theft, and natural disasters. The cost of insurance can vary based on your home’s location, age, construction, and the level of coverage you choose. It’s wise to shop around for quotes and understand what your policy covers and excludes. In areas prone to specific risks (e.g., hurricanes, earthquakes), additional specialized insurance may be required, adding to your 2026 homeownership costs.
Anúncios
Private Mortgage Insurance (PMI)
If your down payment is less than 20% of the home’s purchase price, your lender will typically require you to pay Private Mortgage Insurance (PMI). PMI protects the lender in case you default on your loan. While it adds to your monthly expenses, it also allows you to purchase a home with a smaller down payment. PMI can often be canceled once you reach 20% equity in your home, either through payments or an increase in home value. Factor this into your initial budget for 2026 homeownership costs.
Closing Costs: The Upfront Surprise
Closing costs are fees paid at the closing of a real estate transaction. These can include origination fees, appraisal fees, title insurance, attorney fees, recording fees, and more. Closing costs typically range from 2% to 5% of the loan amount and are a significant upfront expense that many first-time buyers underestimate. It’s crucial to budget for these costs well in advance. Understanding these fees is critical for managing your initial 2026 homeownership costs.
Ongoing 2026 Homeownership Costs: Maintenance and Utilities
Once you’ve moved in, the expenses don’t stop. Regular maintenance and utility bills are continuous financial commitments.
Utilities: A Monthly Necessity
Utility costs, including electricity, gas, water, sewer, and trash removal, are ongoing expenses that vary based on your home’s size, age, energy efficiency, and local climate. It’s advisable to get an estimate of average utility costs for homes in the area you are considering. Upgrading to energy-efficient appliances and improving insulation can help reduce these costs over time, positively impacting your long-term 2026 homeownership costs.
Home Maintenance and Repairs: The Unexpected
One of the most overlooked aspects of homeownership is the cost of maintenance and repairs. Homes require ongoing upkeep, from routine tasks like lawn care and gutter cleaning to unexpected repairs like a leaky roof or a broken appliance. Experts often recommend budgeting 1% to 3% of your home’s value annually for maintenance. Establishing an emergency fund specifically for home repairs is a wise financial strategy to mitigate the impact of unforeseen 2026 homeownership costs.
HOA Fees (If Applicable)
If you purchase a home in a planned community, condominium, or townhouse development, you will likely be subject to Homeowners Association (HOA) fees. These fees cover the maintenance of common areas, amenities (like pools or gyms), and sometimes certain exterior repairs. HOA fees can range from modest to substantial, so it’s important to understand what they cover and factor them into your monthly budget. These fees are a non-negotiable part of 2026 homeownership costs in many developments.
Budgeting Strategies for 2026 Homeownership Costs
Effective budgeting is the cornerstone of successful homeownership. Here are some strategies to help you prepare for 2026 homeownership costs:
The 28/36 Rule
A common guideline for mortgage affordability is the 28/36 rule. This suggests that your monthly housing expenses (including principal, interest, taxes, and insurance – PITI) should not exceed 28% of your gross monthly income. Additionally, your total debt obligations (including housing, car payments, student loans, and credit card debt) should not exceed 36% of your gross monthly income. While a guideline, it provides a good starting point for assessing what you can realistically afford.
Creating a Detailed Budget
Before you even start house hunting, create a comprehensive budget that accounts for all your current income and expenses. This will help you identify areas where you can save more for a down payment and assess how a new mortgage payment will fit into your financial life. Don’t forget to include discretionary spending to ensure your budget is realistic and sustainable. A thorough budget is the best defense against unexpected 2026 homeownership costs.
Building an Emergency Fund
Beyond your down payment and closing costs, having a robust emergency fund is crucial. This fund should ideally cover 3-6 months of living expenses, providing a financial safety net for unexpected job loss, medical emergencies, or significant home repairs. This fund is especially important when considering the variable nature of some 2026 homeownership costs.
Pre-Approval vs. Pre-Qualification
Obtaining mortgage pre-approval is a vital step. Unlike pre-qualification, which is an estimate, pre-approval involves a more thorough review of your financial situation by a lender, resulting in a conditional commitment for a specific loan amount. This not only gives you a clear understanding of your borrowing power but also makes your offers more attractive to sellers. A pre-approval will give you a concrete figure for your potential 2026 homeownership costs related to the mortgage.
Long-Term Financial Planning for Your Home
Homeownership is a long-term commitment, and your financial planning should reflect that.
Refinancing Opportunities
The interest rate environment can change over time. If interest rates drop significantly after you’ve purchased your home, refinancing your mortgage could be an option to secure a lower interest rate and reduce your monthly payments, thereby lowering your overall 2026 homeownership costs (or future costs). However, be aware of refinancing costs, which can include new closing costs.
Building Home Equity
As you pay down your mortgage and your home’s value potentially appreciates, you build equity. Home equity can be a valuable financial asset, accessible through home equity loans or lines of credit (HELOCs) for various purposes, such as home improvements or debt consolidation. Understanding how equity grows is key to long-term financial health and a benefit that offsets some 2026 homeownership costs.
Property Value Appreciation
While not guaranteed, property values tend to appreciate over the long term. This appreciation can increase your net worth and provide a significant return on your investment. However, market fluctuations can occur, and it’s important to view homeownership as a long-term investment rather than a short-term speculative venture. The potential for appreciation is a key driver for many considering 2026 homeownership costs.
Tips for First-Time Homebuyers in 2026
For those new to the homebuying process, the journey can seem daunting. Here are some tailored tips to navigate 2026 homeownership costs:
- Start Saving Early: The more you save for a down payment and closing costs, the better your financial position will be.
- Improve Your Credit Score: A higher credit score can qualify you for better interest rates, significantly reducing your long-term mortgage costs.
- Research Down Payment Assistance Programs: Many states and local governments offer programs to help first-time homebuyers with down payments and closing costs.
- Get Pre-Approved for a Mortgage: This gives you a clear budget and makes you a more competitive buyer.
- Work with a Reputable Real Estate Agent: An experienced agent can provide invaluable guidance, market insights, and negotiation skills.
- Don’t Forget the Inspection: A thorough home inspection can uncover potential issues before you buy, saving you from costly repairs down the line.
- Understand Your Property Taxes: Research the typical property tax rates in your desired areas.
- Factor in Ongoing Maintenance: Budget for both routine maintenance and an emergency fund for unexpected repairs.
- Consider Your Commute: Location impacts not just home price but also transportation costs, which are part of overall 2026 homeownership costs.
- Be Patient and Flexible: The homebuying process can be lengthy and require compromises. Stay persistent and open to different options.
The Role of Technology in Managing 2026 Homeownership Costs
Technology is increasingly playing a significant role in simplifying the homebuying process and helping homeowners manage their finances more effectively.
Online Mortgage Calculators and Tools
Numerous online calculators can help you estimate mortgage payments, assess affordability, and compare different loan scenarios. These tools are invaluable for understanding how various factors like interest rates, loan terms, and down payments impact your monthly 2026 homeownership costs.
Financial Planning Apps
Budgeting apps can help you track your income and expenses, set financial goals, and monitor your progress towards saving for a down payment or building an emergency fund. Many apps offer features specifically designed for homeowners, allowing you to categorize home-related expenses and track property value.
Smart Home Technology for Energy Savings
Investing in smart home technology, such as smart thermostats, energy-efficient lighting, and smart appliances, can lead to significant savings on utility bills over time. While there’s an initial investment, the long-term reduction in energy consumption contributes positively to managing your 2026 homeownership costs.
Conclusion: Preparing for a Successful Homeownership Journey in 2026
Navigating the path to homeownership in 2026 requires careful planning, diligent budgeting, and a comprehensive understanding of all associated costs. From the initial down payment and closing costs to the ongoing expenses of mortgage payments, property taxes, insurance, and maintenance, every financial detail matters. By understanding the dynamics of the 2026 housing market, meticulously planning your budget, and leveraging available resources, you can confidently embark on your homeownership journey.
Remember, homeownership is not just a financial transaction; it’s an investment in your future and a place to create lasting memories. By being well-informed and prepared for all 2026 homeownership costs, you can turn the dream of owning a home into a tangible and sustainable reality. Start planning today, stay disciplined with your savings, and seek expert advice to ensure a smooth and successful transition into your new home.