Social Security 2026: What Americans Can Expect from Adjustments
Anúncios
Understanding the future of Social Security is paramount for millions of Americans who rely on these benefits for their retirement, disability, or survivor income. As we look towards 2026, several key adjustments are anticipated that could significantly impact recipients’ financial landscapes. These adjustments are not arbitrary; they are the result of complex calculations, economic forecasts, and, at times, legislative decisions aimed at ensuring the long-term solvency and fairness of the program. This comprehensive guide will delve into the projected Social Security 2026 Adjustments, examining the various factors that influence them, what they mean for beneficiaries, and how individuals can prepare for these changes.
Social Security remains a cornerstone of financial security for American families. It’s more than just a retirement check; it provides vital support to disabled workers and their families, as well as to the survivors of deceased workers. Given its widespread impact, staying informed about upcoming changes, particularly the Social Security 2026 Adjustments, is not just a recommendation but a necessity. From Cost-of-Living Adjustments (COLA) to potential shifts in the program’s financial standing, every detail plays a role in shaping the economic future of its beneficiaries.
The Importance of Social Security Adjustments
Social Security benefits are not static; they are designed to adapt to economic realities. This adaptability is crucial for maintaining the purchasing power of benefits over time, especially in the face of inflation. The adjustments, particularly the annual Cost-of-Living Adjustment (COLA), are a testament to this design. Without these regular recalibrations, the value of Social Security benefits would erode, leaving beneficiaries struggling to keep pace with rising costs of living.
The upcoming Social Security 2026 Adjustments are particularly significant as they fall within a period of ongoing economic evolution. Factors such as inflation rates, wage growth, and demographic shifts all contribute to the calculations that determine these adjustments. For retirees, individuals with disabilities, and surviving family members, these changes directly influence their monthly income and, consequently, their ability to cover essential expenses like housing, food, healthcare, and transportation.
Beyond the immediate financial implications, these adjustments also reflect the broader health and sustainability of the Social Security program. Discussions around the Social Security 2026 Adjustments often bring to light the long-term solvency challenges faced by the trust funds and spark debates about potential reforms. Therefore, understanding these adjustments is not just about personal finance; it’s about engaging with a critical national conversation about the future of a program that serves millions.
Anúncios
Understanding the Cost-of-Living Adjustment (COLA) for 2026
The Cost-of-Living Adjustment (COLA) is perhaps the most anticipated of all Social Security adjustments. Its primary purpose is to ensure that the purchasing power of Social Security and Supplemental Security Income (SSI) benefits is not eroded by inflation. Each year, the Social Security Administration (SSA) announces a COLA, which is applied to benefits beginning in December of that year (paid out in January of the following year).
How COLA is Calculated
The COLA is determined by the increase in the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W) from the third quarter of the previous year to the third quarter of the current year. If there is no increase, there is no COLA. This calculation method is designed to reflect the real-world expenses faced by a significant portion of the population, thereby ensuring that benefits keep pace with the cost of goods and services.
Anúncios
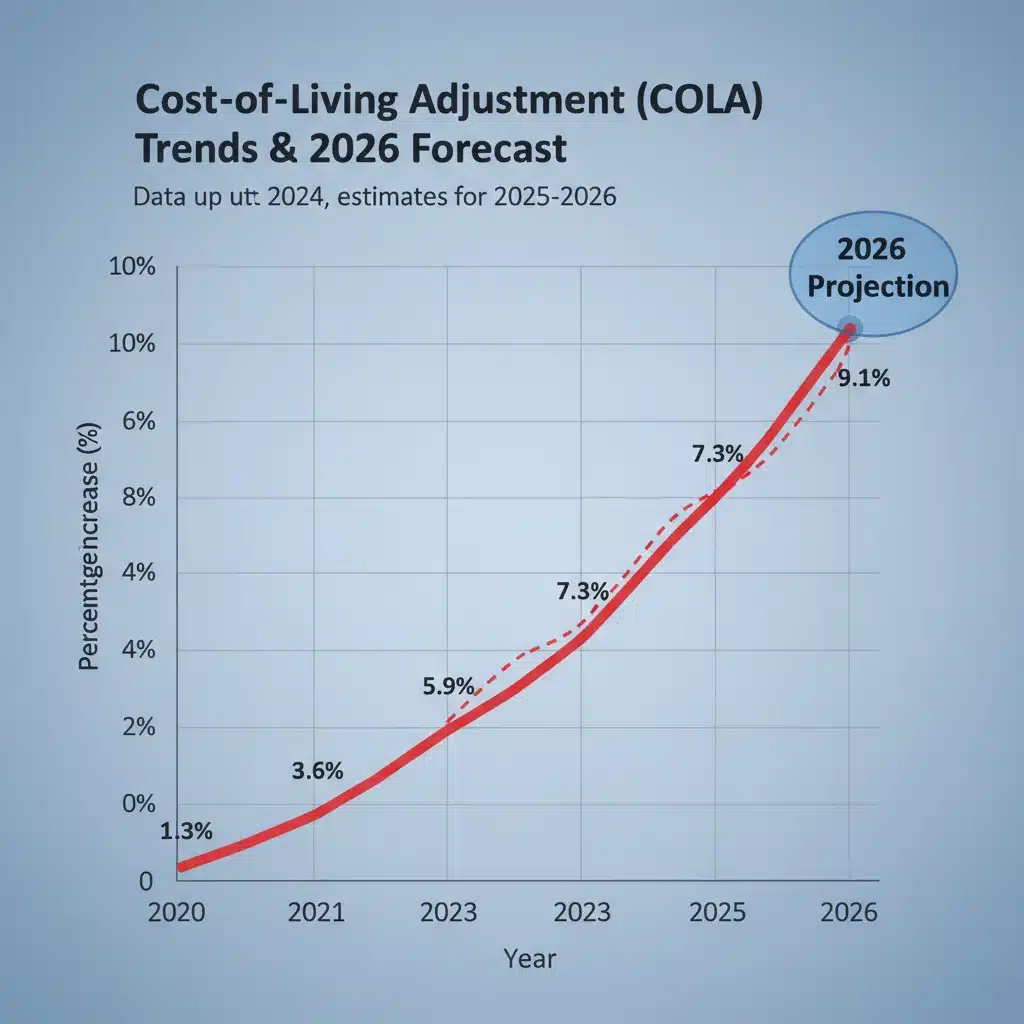
For the Social Security 2026 Adjustments, the COLA will be based on the CPI-W data from the third quarter of 2025 compared to the third quarter of 2024. While it’s too early to provide a definitive COLA percentage for 2026, economists and financial analysts make projections based on current inflation trends and forecasts. These projections are often a subject of considerable interest and speculation, as even a small percentage point difference can translate into significant dollar amounts for beneficiaries over time.
Projected COLA for 2026
Forecasting the exact COLA for 2026 involves a degree of uncertainty. However, based on current economic indicators and expert analyses, preliminary estimates can be made. Factors such as energy prices, food costs, and housing inflation will play a critical role in shaping the CPI-W leading up to the third quarter of 2025. A higher inflation environment typically leads to a higher COLA, while a more stable or deflationary period could result in a lower or even zero COLA.
It’s important for beneficiaries to monitor these projections, although the official announcement is typically made in October of the preceding year. Financial planners often advise clients to consider a range of potential COLA outcomes when planning their retirement budgets, recognizing that the actual figure for the Social Security 2026 Adjustments might deviate from initial forecasts.
Social Security Trust Funds: Solvency and Projections for 2026
The long-term solvency of the Social Security trust funds is a perennial concern and a critical aspect of any discussion about Social Security adjustments. The program operates through two main trust funds: the Old-Age and Survivors Insurance (OASI) Trust Fund and the Disability Insurance (DI) Trust Fund. These funds hold the payroll taxes collected from workers and employers, which are then used to pay out benefits.
Current State of the Trust Funds
According to the latest Trustees’ Report, the combined trust funds are projected to be able to pay 100% of promised benefits until a certain point, after which they would only be able to pay a reduced percentage if no legislative action is taken. These projections are updated annually and take into account demographic trends (such as birth rates, mortality rates, and immigration), economic assumptions (like wage growth and inflation), and program expenditures.
The Social Security 2026 Adjustments will occur within this broader context of trust fund solvency. While the program is not facing an immediate collapse, the long-term projections indicate that revenues will eventually fall short of outlays, necessitating either benefit reductions, revenue increases, or a combination of both to maintain full solvency.
Impact of Demographic Shifts and Economic Factors
Demographic shifts, particularly the aging of the baby-boomer generation and lower birth rates, mean that fewer workers are contributing to the system relative to the number of beneficiaries. This changing dependency ratio puts pressure on the trust funds. Economic factors, such as productivity growth and real wage increases, also play a significant role. Strong economic growth can improve the financial outlook of the trust funds by increasing payroll tax revenues.
For the Social Security 2026 Adjustments, the Trustees’ Report will have already provided updated projections, giving a clearer picture of the program’s financial health. These projections are crucial for policymakers who consider various legislative options to address the long-term challenges. Beneficiaries and future retirees should be aware of these trends as they can influence not only the COLA but also the broader structure of benefits in the future.
Potential Legislative Changes and Their Impact on Social Security 2026 Adjustments
While COLA is an automatic adjustment, other aspects of Social Security can be altered through legislation. Discussions about Social Security reform are ongoing in Washington, D.C., with various proposals aimed at shoring up the program’s finances and ensuring its long-term viability. Any significant legislative changes could directly or indirectly affect the Social Security 2026 Adjustments.
Common Reform Proposals
Several common reform proposals are frequently debated:
- Raising the Full Retirement Age (FRA): Gradually increasing the age at which individuals can receive their full Social Security benefits is one approach to reduce program outlays.
- Adjusting the Social Security Tax Cap: Currently, earnings above a certain threshold are not subject to Social Security taxes. Raising or eliminating this cap would increase revenue.
- Modifying the COLA Calculation: Some proposals suggest using a different inflation index, such as the Chained CPI, which typically grows slower than the CPI-W, potentially leading to lower COLA increases.
- Increasing the Payroll Tax Rate: A small increase in the percentage of earnings contributed to Social Security could significantly boost revenues.
- Means-Testing Benefits: This controversial proposal would reduce benefits for higher-income retirees.
While it’s impossible to predict which, if any, of these proposals might be enacted by 2026, the ongoing dialogue means that beneficiaries should remain attentive to legislative developments. Even if no major structural changes are implemented by 2026, the discussions themselves highlight the pressures on the system and the potential for future alterations that could affect subsequent Social Security adjustments.
How Legislative Action Could Affect 2026
Any legislative changes enacted before or during 2025 could potentially influence the Social Security 2026 Adjustments. For example, a change in the COLA calculation method could directly alter the benefit increase. Similarly, adjustments to the earnings test for those working while receiving benefits, or changes to how benefits are calculated for new retirees, could indirectly affect the overall financial picture for beneficiaries.
It is crucial for individuals nearing retirement or currently receiving benefits to stay informed about these potential legislative shifts. Engaging with advocacy groups and monitoring official government announcements can provide valuable insights into how these proposed changes might materialize and impact their financial planning.
Impact on Beneficiaries: What the Social Security 2026 Adjustments Mean for You
The Social Security 2026 Adjustments will have tangible effects on various groups of beneficiaries. Understanding these impacts can help individuals fine-tune their financial strategies and ensure they are prepared for the future.
Retirees
For current retirees, the COLA is the most direct impact. A higher COLA means more disposable income to cover rising living costs, while a lower COLA could necessitate tighter budgeting. Retirees should also consider how potential legislative changes, such as adjustments to the full retirement age or means-testing, might affect their long-term benefit projections, even if those changes don’t take full effect by 2026.
Individuals with Disabilities
Social Security Disability Insurance (SSDI) beneficiaries also receive the annual COLA. For these individuals, whose ability to work may be limited, the stability and adequacy of their benefits are particularly critical. Any changes to the COLA or other program parameters could significantly impact their financial well-being and access to essential services.
Survivors
Spouses, children, and other dependents who receive survivor benefits are also subject to the same COLA adjustments. For many, these benefits represent a crucial safety net. Understanding the Social Security 2026 Adjustments allows survivor beneficiaries to plan for their financial future with greater certainty.
Future Retirees and Workers
For those still in the workforce, the Social Security 2026 Adjustments might seem less immediate. However, they are highly relevant. Projections about trust fund solvency and potential legislative reforms directly impact the future benefits they can expect. Workers nearing retirement should pay close attention to any changes in the full retirement age or benefit calculation formulas, as these can alter their retirement planning significantly.
Planning for the Social Security 2026 Adjustments
Given the anticipated Social Security 2026 Adjustments, proactive planning is essential. Whether you are a current beneficiary or still years away from retirement, taking steps now can help you mitigate potential risks and maximize your financial security.
Review Your Social Security Statement
Regularly reviewing your Social Security statement is a fundamental step. This statement provides an estimate of your future benefits based on your earnings record. It’s crucial to check for any discrepancies and ensure your earnings history is accurate, as this directly impacts your benefit calculations.
Diversify Retirement Savings
Relying solely on Social Security for retirement income can be risky, especially with ongoing discussions about the program’s long-term solvency. Diversifying your retirement savings through 401(k)s, IRAs, and other investment vehicles can provide a buffer against potential changes to Social Security benefits. This strategy ensures that even if Social Security 2026 Adjustments or future changes are less favorable, your overall financial plan remains robust.
Consider Working Longer
Working beyond your full retirement age can increase your monthly Social Security benefit in several ways. Firstly, you continue to contribute to Social Security, potentially boosting your average indexed monthly earnings (AIME), which is used to calculate your benefits. Secondly, for each year you delay claiming benefits past your full retirement age, up to age 70, you earn delayed retirement credits, significantly increasing your monthly payment.
Understand Medicare and Healthcare Costs
Medicare premiums are often deducted directly from Social Security benefits. Therefore, changes in Medicare costs can indirectly impact the net Social Security benefit received. As part of planning for the Social Security 2026 Adjustments, it’s wise to also monitor projected Medicare premium increases and factor them into your overall budget. Healthcare costs are a major expense in retirement, and understanding their interplay with Social Security is vital.
Stay Informed and Seek Professional Advice
The landscape of Social Security is constantly evolving. Staying informed through official SSA channels, reputable financial news sources, and government reports is critical. Additionally, consulting with a qualified financial advisor who specializes in retirement planning can provide personalized guidance tailored to your specific circumstances. They can help you understand how the Social Security 2026 Adjustments and broader program changes might affect your financial plan and suggest strategies to optimize your benefits.
The Future Outlook Beyond 2026
While our focus is on the Social Security 2026 Adjustments, it’s important to recognize that the program’s challenges and potential changes extend far beyond that year. The long-term projections from the Social Security Trustees indicate that without legislative intervention, the trust funds will eventually be depleted, leading to a reduction in benefits. This means that discussions and potential reforms will continue to be a significant part of the national agenda for years to come.
Ongoing Dialogue and Bipartisan Solutions
Finding a bipartisan solution to ensure the long-term solvency of Social Security is a complex but necessary endeavor. Various stakeholders, including policymakers, economists, and advocacy groups, will continue to propose and debate different approaches. These discussions will inevitably influence future Social Security adjustments, making it imperative for citizens to remain engaged and voice their perspectives.
Personal Responsibility in Retirement Planning
Ultimately, while Social Security provides a vital foundation, personal responsibility in retirement planning is more crucial than ever. The Social Security 2026 Adjustments serve as a reminder that individuals should not solely rely on government benefits for their financial security. Building a robust personal savings plan, exploring investment opportunities, and making informed decisions about claiming benefits are all essential components of a secure financial future.
Conclusion: Navigating the Social Security 2026 Adjustments
The Social Security 2026 Adjustments represent another chapter in the ongoing evolution of a program critical to millions of Americans. From the annual Cost-of-Living Adjustment (COLA) designed to combat inflation to the broader implications of trust fund solvency and potential legislative reforms, these changes demand attention and proactive planning.
By understanding how COLA is calculated, staying informed about the financial health of the trust funds, and monitoring legislative developments, beneficiaries and future retirees can better prepare for what lies ahead. Reviewing personal Social Security statements, diversifying retirement savings, and seeking professional financial advice are practical steps that can help ensure financial resilience in the face of these adjustments.
Social Security has been a bedrock of American society for decades, and its continued viability is a shared responsibility. By engaging with the information, planning diligently, and advocating for thoughtful solutions, individuals can contribute to securing their own financial future and the future of Social Security for generations to come. The Social Security 2026 Adjustments are not just numbers; they are a call to action for informed citizenship and prudent financial management.