Mortgage Rates & Home Buying: A 6.8% Average Impact
Anúncios
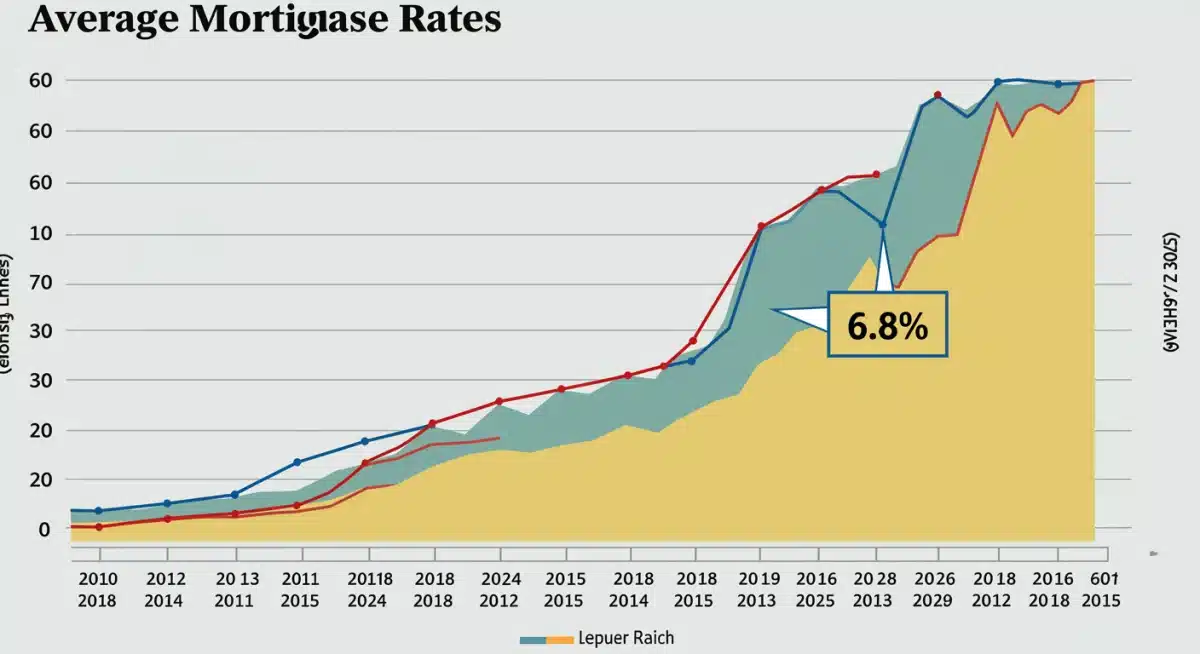
Understanding the influence of a 6.8% average mortgage rate is crucial for prospective homebuyers in 2026, as it directly shapes affordability and market dynamics for purchasing power.
Navigating the housing market can feel like a complex puzzle, especially when economic indicators shift. For anyone considering a home purchase in the near future, particularly in 2026, understanding the impact of mortgage rates 2026 is paramount. A projected average rate of 6.8% could significantly reshape affordability and home buying power, making careful planning more critical than ever.
The economic landscape influencing 2026 mortgage rates
The trajectory of mortgage rates is rarely a straight line; it’s a dynamic response to broader economic forces. As we look towards 2026, several key factors are expected to shape whether that 6.8% average holds steady, rises, or falls. These influences range from global economic stability to domestic policy decisions, all playing a role in the cost of borrowing for a home.
Anúncios
Inflation remains a primary driver. When inflation is high, central banks often raise interest rates to cool down the economy, which in turn pushes mortgage rates higher. Conversely, a stable or declining inflation rate could lead to more favorable borrowing conditions. The Federal Reserve’s monetary policy, particularly its federal funds rate decisions, directly impacts the interest rates lenders offer. Any shifts in their approach to managing economic growth and price stability will have a ripple effect on the housing market.
Global and domestic influences
- Geopolitical events: Global conflicts or significant international trade disputes can create economic uncertainty, leading investors to seek safer assets like U.S. Treasury bonds. This can indirectly influence mortgage rates.
- Job market strength: A robust job market with low unemployment often signals a strong economy, which can contribute to inflationary pressures and higher rates.
- Housing supply and demand: The fundamental balance between available homes and prospective buyers also plays a role. A tight supply can push prices up, while high demand can sustain higher mortgage rates as lenders see strong buyer interest.
Understanding these interconnected elements is crucial for anticipating the future of mortgage rates. While a 6.8% average is a projection, these underlying economic conditions are the levers that will ultimately determine its reality, making it essential for potential homebuyers to stay informed about both macro and micro economic developments.
How a 6.8% average rate impacts monthly payments
A 6.8% average mortgage rate isn’t just a number; it translates directly into real-world monthly payments for homeowners. This percentage dictates a significant portion of your housing budget, influencing how much house you can afford and the financial strain of homeownership. Understanding this direct correlation is vital for budgeting and financial planning.
Anúncios
Let’s consider an example. For a $400,000 home with a 20% down payment, a 30-year fixed-rate mortgage at 6.8% would result in a considerably higher monthly principal and interest payment compared to a lower rate. This increase can amount to hundreds of dollars each month, which over the lifespan of a loan, adds up to a substantial sum. This is why even a seemingly small percentage point increase can have a profound effect on a buyer’s financial capacity.
Calculating your potential payments
- Loan amount: The larger the loan, the more significant the impact of the interest rate on monthly payments.
- Loan term: A 30-year mortgage will have lower monthly payments than a 15-year mortgage at the same rate, but you’ll pay more interest over the long term.
- Down payment: A larger down payment reduces the principal amount borrowed, thereby lowering your monthly interest payments.
The implications extend beyond just the principal and interest. Higher monthly payments can affect your eligibility for a loan, as lenders assess your debt-to-income ratio. A higher mortgage payment might push this ratio beyond acceptable limits, even for buyers with good credit. Therefore, a 6.8% rate necessitates a more conservative approach to home affordability, urging buyers to re-evaluate their budgets and expectations.
Home affordability and buying power in 2026
The concept of home affordability is directly tied to the interplay of home prices, income levels, and, crucially, mortgage rates. With a projected 6.8% average mortgage rate in 2026, the landscape for home affordability and buying power is set to be challenging for many prospective homeowners across the United States. This rate acts as a significant barrier, particularly in markets where home prices have already seen substantial appreciation.
Higher interest rates mean that for the same monthly payment, a buyer can afford a smaller loan amount. This directly reduces their buying power. For instance, if a buyer could afford a $350,000 home at a 5% interest rate, that same monthly payment might only qualify them for a $300,000 home at a 6.8% rate. This reduction in purchasing capacity means buyers may need to compromise on location, size, or features, or save a larger down payment.
Strategies to enhance buying power
- Increase down payment: A larger down payment reduces the loan amount, thereby mitigating the impact of higher interest rates.
- Improve credit score: A higher credit score can qualify you for the best available rates, even if the overall average is high.
- Explore different loan types: While fixed-rate mortgages are common, adjustable-rate mortgages (ARMs) might offer lower initial rates, though with inherent risks.
The challenge of affordability is not uniform; it varies significantly by region and local market dynamics. High-cost-of-living areas will feel the pinch of a 6.8% rate more acutely than more affordable regions. Therefore, potential buyers must conduct thorough research into their target markets and realistically assess their financial capabilities in light of these elevated borrowing costs. Adapting expectations and exploring all available financial avenues will be key to successful homeownership in 2026.
Strategies for homebuyers in a high-rate environment
Facing a 6.8% average mortgage rate requires a strategic approach from homebuyers. It’s not about giving up on the dream of homeownership, but rather about adapting tactics to navigate the market effectively. Being well-prepared and flexible can make a significant difference in securing a home that fits both your needs and your budget.
One primary strategy is to focus on improving your financial health. This includes aggressively saving for a larger down payment, which reduces the amount you need to borrow and, consequently, the total interest paid over the life of the loan. Additionally, working to improve your credit score can help you qualify for the most competitive rates available, even if the general market is high. Lenders often offer better terms to borrowers deemed less risky.
Navigating the market effectively
- Consider adjustable-rate mortgages (ARMs): While riskier, ARMs often start with lower interest rates than fixed-rate mortgages, which can be beneficial if you plan to move or refinance within the initial fixed period.
- Look at less competitive markets: Expanding your search to include slightly less desirable neighborhoods or suburban areas might reveal more affordable options.
- Seek pre-approval: Getting pre-approved for a mortgage gives you a clear understanding of what you can afford and makes you a more attractive buyer to sellers.
Another crucial strategy is to be patient and flexible. The housing market can be unpredictable, and waiting for potential rate dips or an increase in housing supply could work in your favor. Moreover, being open to different types of homes, such as townhouses or condos instead of single-family homes, can broaden your options within your budget. Ultimately, a high-rate environment demands diligence, financial prudence, and a willingness to adapt your home buying plan.
Refinancing potential and future rate predictions
While a 6.8% average mortgage rate presents challenges for new homebuyers, it also raises questions about refinancing potential for existing homeowners and the long-term outlook for rates. Understanding the dynamics of refinancing and future predictions is crucial for both current and aspiring homeowners to make informed decisions.
For those purchasing a home with a 6.8% rate, the hope is often that rates will decline in the future, allowing for a refinance into a lower rate. Refinancing can significantly reduce monthly payments and the total interest paid over the loan term. However, the decision to refinance depends on various factors, including closing costs, how long you plan to stay in the home, and the actual rate difference. A substantial drop in rates, typically 0.75% to 1% below your current rate, usually makes refinancing a financially sound move.
Factors influencing future rate predictions
- Federal Reserve policy: The Fed’s stance on inflation and economic growth will continue to be the most significant factor influencing future rate movements.
- Economic growth: Strong, sustained economic growth might lead to higher inflation and, consequently, higher rates.
- Global economic stability: International events can cause shifts in investor confidence, impacting bond yields and mortgage rates.
Predicting future mortgage rates with certainty is difficult, as many variables are at play. However, economists and financial institutions continually release forecasts based on current data and trends. These predictions often suggest periods of fluctuation, with potential for rates to stabilize or even gradually decrease if inflation is brought under control. Homeowners and prospective buyers should monitor these forecasts closely, but also remember that they are estimates, and market conditions can change rapidly. The key is to remain agile and ready to act when favorable conditions arise.
The long-term financial implications of a 6.8% rate
The immediate impact of a 6.8% average mortgage rate is felt in higher monthly payments and reduced buying power. However, the long-term financial implications extend far beyond these initial considerations, affecting wealth accumulation, retirement planning, and overall financial stability for decades to come. Understanding this broader picture is essential for making sound financial decisions when purchasing a home.
One significant implication is the total cost of interest paid over the life of the loan. Even a seemingly small increase in the interest rate can add tens of thousands, or even hundreds of thousands, of dollars to the total amount repaid for a home. This extra cost means less money available for other investments, savings, or discretionary spending. It can slow down wealth accumulation and delay other financial goals, such as saving for retirement or a child’s education.
Managing long-term financial health
- Aggressive principal payments: Paying extra towards your principal each month, even a small amount, can significantly reduce the total interest paid and shorten the loan term.
- Consider a shorter loan term: If financially feasible, a 15-year mortgage, despite higher monthly payments, can save a substantial amount in interest over the long run.
- Regular financial reviews: Periodically reviewing your mortgage and financial situation can help identify opportunities for refinancing or other adjustments to optimize your financial health.
Moreover, a higher mortgage burden can reduce financial flexibility. In times of economic uncertainty or unexpected expenses, a significant portion of income committed to housing can limit options. It underscores the importance of building an emergency fund and maintaining a diverse investment portfolio to offset the increased housing cost. Long-term financial planning with a 6.8% mortgage rate requires a disciplined approach, focusing on debt reduction and strategic savings to ensure a secure financial future.
| Key Point | Brief Description |
|---|---|
| Impact on Monthly Payments | A 6.8% rate significantly increases monthly principal and interest payments, impacting affordability. |
| Reduced Buying Power | For the same monthly budget, buyers can afford a smaller loan amount, limiting home options. |
| Strategic Adjustments Needed | Buyers must save more for down payments, improve credit, or consider different loan types. |
| Long-Term Financial Strain | Higher rates lead to increased total interest paid, affecting wealth accumulation and financial flexibility. |
Frequently asked questions about 2026 mortgage rates
Mortgage rates in 2026 are primarily influenced by inflation, the Federal Reserve’s monetary policy, and the overall strength of the U.S. economy. Global economic events and the supply and demand dynamics within the housing market also play significant roles in shaping their trajectory.
A 6.8% mortgage rate significantly increases your monthly principal and interest payment compared to lower rates. For example, on a $300,000 loan, this rate could add hundreds of dollars to your monthly housing expense, directly impacting your budget and affordability.
Yes, but it requires strategic planning. You might need to save a larger down payment, improve your credit score for better terms, or consider properties in more affordable areas. Exploring different loan products, like ARMs, could also be an option depending on your financial situation and long-term plans.
Refinancing is definitely an option if mortgage rates decline significantly after your purchase. Many homeowners aim to refinance if rates drop by 0.75% to 1% or more, as this can lead to substantial savings on monthly payments and total interest over the life of the loan.
The long-term impacts include paying significantly more in total interest over the loan’s duration, which can slow down wealth accumulation and reduce financial flexibility. It emphasizes the importance of making extra principal payments or considering a shorter loan term to mitigate these effects.
Conclusion
The projected 6.8% average mortgage rate for 2026 presents a distinct set of challenges and opportunities for the housing market. While it necessitates a more disciplined approach to home buying, including rigorous financial planning and a willingness to adapt, it doesn’t close the door on homeownership. Prospective buyers must remain informed about economic shifts, explore all available financing options, and strategically position themselves to achieve their home buying goals. Ultimately, understanding the intricate relationship between economic indicators and mortgage rates will be the cornerstone of successful navigation in the evolving real estate landscape.