FICO Score Updates: How a 20-Point Shift Can Impact Your Loan Rates
Anúncios
The Latest FICO Score Updates: How a 20-Point Shift Can Impact Your Loan Rates
In the complex world of personal finance, your FICO score stands as a pivotal gatekeeper, determining not just whether you’ll be approved for a loan, but also the crucial terms and interest rates attached to it. For many, the FICO score can feel like an enigmatic, ever-changing entity. However, understanding its dynamics, especially the impact of even a seemingly small 20-point shift, is paramount to navigating your financial journey successfully. Recent FICO score updates and ongoing refinements mean that staying informed is more critical than ever. This comprehensive guide will delve into the nuances of FICO scores, explain how a marginal change can have a monumental effect on your loan rates, and provide actionable strategies to optimize your credit health.
Your FICO score is more than just a number; it’s a three-digit summary of your creditworthiness, derived from the data in your credit reports. Lenders use this score to assess the risk of lending you money. A higher score generally indicates a lower risk, translating into more favorable loan terms, including lower interest rates. Conversely, a lower score signals higher risk, often leading to higher interest rates or even loan denials. The latest FICO score impact on consumers underscores the need for continuous credit monitoring and proactive management.
Understanding the FICO Score: A Brief Overview
Before we explore the impact of a 20-point shift, let’s briefly revisit what a FICO score is and how it’s calculated. Developed by the Fair Isaac Corporation, FICO scores are the most widely used credit scores by lenders. They typically range from 300 to 850, with higher scores being better. The score is calculated using a complex algorithm that considers five main categories from your credit report:
- Payment History (35%): This is the most significant factor, reflecting your track record of paying bills on time. Late payments, bankruptcies, and collections can severely damage this component.
- Amounts Owed (30%): This looks at how much credit you’re using compared to your available credit (credit utilization ratio). Keeping this ratio low (ideally below 30%) is beneficial.
- Length of Credit History (15%): The longer your credit accounts have been open and in good standing, the better.
- New Credit (10%): This considers how many new credit accounts you’ve opened recently and how many hard inquiries have been made on your credit report. Too many can be a red flag.
- Credit Mix (10%): Lenders prefer to see a healthy mix of different types of credit, such as installment loans (mortgages, auto loans) and revolving credit (credit cards).
Recent FICO score updates often involve minor tweaks to these algorithms, sometimes to better reflect current economic conditions or consumer behavior. While these updates might seem subtle, their cumulative effect can be profound, especially when considering the FICO score impact on your borrowing power.
Anúncios
The "20-Point Shift" Phenomenon: Why It Matters
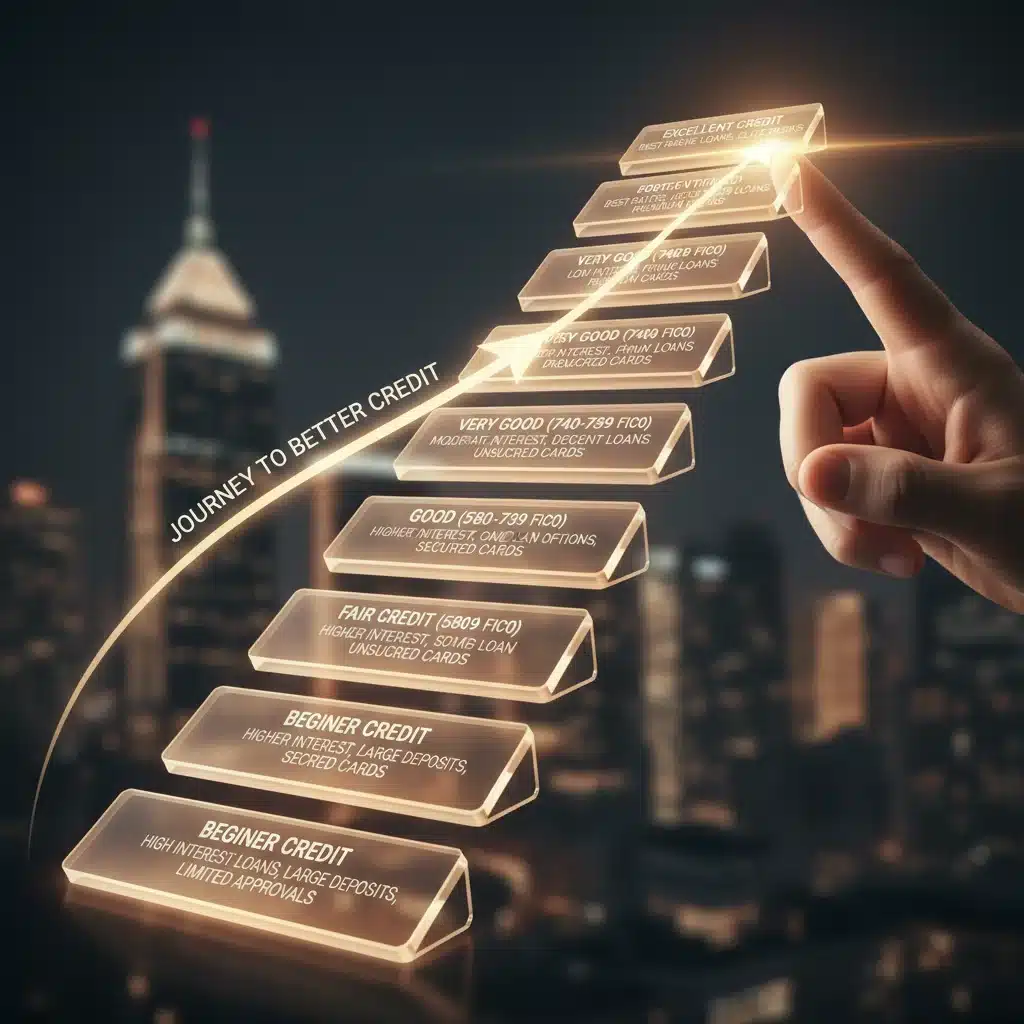
You might think a 20-point change in your FICO score is negligible. After all, it’s a small fraction of the 300-850 range. However, this seemingly minor fluctuation can push you into a different ‘score band,’ which lenders use to categorize borrowers. Each band corresponds to a different level of perceived risk and, consequently, different interest rates and loan terms. The FICO score impact of these band shifts is where the real financial consequences lie.
Let’s illustrate this with an example. Imagine a lender’s risk tiers:
- Excellent Credit: 760-850
- Very Good Credit: 700-759
- Good Credit: 670-699
- Fair Credit: 580-669
- Poor Credit: 300-579
If your score is 690, you’re in the “Good Credit” band. A 20-point increase to 710 moves you into the “Very Good Credit” band. This shift, though small numerically, can unlock significantly better interest rates. Conversely, a 20-point drop from 680 to 660 could push you from “Good Credit” to “Fair Credit,” resulting in higher borrowing costs. The FICO score impact is thus highly sensitive to these thresholds.
Impact on Different Loan Types
Mortgage Loans
A mortgage is likely the largest financial commitment most people will ever make. Even a slight difference in interest rates can translate into tens of thousands of dollars over the life of a 15-year or 30-year loan. For instance, consider a $300,000 mortgage. A borrower with a FICO score in the “Very Good” range (e.g., 720) might qualify for a 6.5% interest rate, while a borrower with a “Good” score (e.g., 680) might face a 7.0% rate. Over 30 years, that 0.5% difference can add up to over $30,000 in additional interest paid. The FICO score impact here is immense.
Recent FICO score updates have also emphasized payment history and credit utilization for mortgages, making it even more crucial to maintain stellar credit habits leading up to a home purchase. Lenders are increasingly risk-averse, meaning that even small improvements in your FICO score can make your application more attractive and secure better terms.
Auto Loans
While not as long-term as a mortgage, an auto loan also represents a significant financial outlay. Similar to mortgages, auto loan interest rates are heavily influenced by your FICO score. A 20-point increase could shift you from a 9% APR to a 7% APR on a $30,000 car loan over five years. This seemingly minor change could save you hundreds or even thousands of dollars in interest, making your monthly payments more manageable. The FICO score impact on auto loan affordability is often underestimated by consumers.
Credit Cards
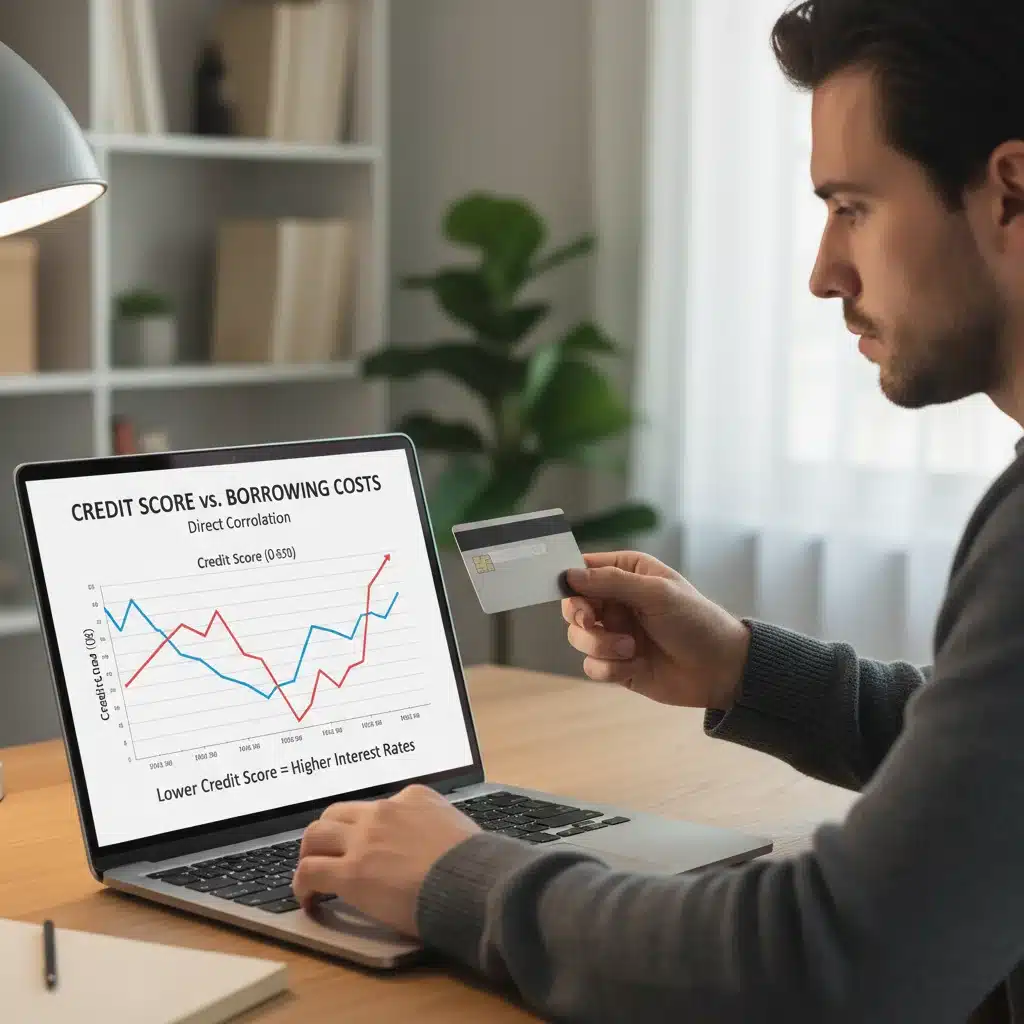
For revolving credit like credit cards, a higher FICO score can lead to lower Annual Percentage Rates (APRs), higher credit limits, and access to premium rewards cards. A 20-point drop might not only increase your APR but also make it harder to get approved for new cards or limit your ability to secure balance transfer offers with 0% introductory rates. The FICO score impact here affects your day-to-day spending power and financial flexibility.
Personal Loans
Personal loans, often used for debt consolidation, home improvements, or unexpected expenses, also see significant rate variations based on credit scores. A 20-point improvement could move you from a high-double-digit APR to a more reasonable single-digit rate, saving you substantial amounts of money and making repayment much easier. This FICO score impact is particularly relevant for those seeking to consolidate high-interest debts.
Anúncios
Recent FICO Score Updates and What They Mean
FICO periodically releases new versions of its scoring models, such as FICO Score 8, FICO Score 9, and the latest FICO Score 10 and 10 T. Each version aims to be more predictive of credit risk. While lenders don’t all adopt the newest models immediately, it’s essential to be aware of the general trends in these updates:
- FICO Score 9: This version is more forgiving of paid collection accounts (they no longer negatively impact your score) and distinguishes between medical and non-medical collections, with medical collections having less impact. It also considers rental payment history if reported to credit bureaus.
- FICO Score 10 and 10 T: These are the latest iterations. FICO Score 10 T, in particular, incorporates “trended data.” Instead of just looking at your current credit utilization, it analyzes your credit utilization over the past 24 months. This means consistent high utilization, even if paid down by the statement date, could be viewed less favorably. Conversely, consistently paying down balances can boost your score. This ‘trended data’ approach significantly amplifies the FICO score impact of your ongoing spending habits.
The key takeaway from these updates is that responsible, consistent credit management is becoming even more crucial. Lenders want to see a pattern of good behavior, not just snapshots. Understanding these FICO score updates is vital for optimizing your credit strategy.
Strategies to Improve Your FICO Score and Mitigate Negative FICO Score Impact
Given the significant FICO score impact on your financial life, actively managing and improving your score should be a priority. Here are actionable strategies:
1. Pay Bills On Time, Every Time
As payment history accounts for 35% of your score, consistent on-time payments are the single most effective way to improve and maintain a good FICO score. Set up automatic payments or calendar reminders to ensure you never miss a due date. Even one late payment (30+ days past due) can cause a significant FICO score drop.
2. Keep Credit Utilization Low
Your credit utilization ratio (amounts owed) is the second most important factor. Aim to keep your total credit card balances below 30% of your total available credit. For example, if you have a combined credit limit of $10,000, try to keep your balances under $3,000. For an optimal FICO score impact, aim for even lower, ideally under 10%. Paying down balances strategically before your statement closing date can also help, especially with models that use trended data.
3. Don’t Close Old, Paid-Off Accounts
The length of your credit history matters. Closing old credit card accounts, especially those with no annual fees, can shorten your average credit age and reduce your total available credit, which can negatively affect your credit utilization ratio. Both can lead to a negative FICO score impact.
4. Limit New Credit Applications
Each time you apply for new credit (a loan or credit card), a “hard inquiry” is placed on your credit report. A few hard inquiries within a short period can signal higher risk to lenders and slightly lower your score. Only apply for new credit when absolutely necessary.
5. Diversify Your Credit Mix
While not a major factor, having a mix of credit types (e.g., a credit card and an installment loan like a car loan) can be beneficial. It shows you can responsibly manage different kinds of debt. However, don’t take on debt you don’t need just to diversify your credit mix, as the FICO score impact from this factor is minimal compared to others.
6. Regularly Check Your Credit Report
Errors on your credit report can unfairly drag down your FICO score. You are entitled to a free copy of your credit report from each of the three major bureaus (Experian, Equifax, and TransUnion) once every 12 months via AnnualCreditReport.com. Review them carefully for inaccuracies and dispute any errors immediately. Correcting errors can have a swift, positive FICO score impact.
7. Consider a Secured Credit Card or Credit Builder Loan
If you have a limited credit history or are rebuilding bad credit, a secured credit card or a credit builder loan can be excellent tools. A secured card requires a deposit, which becomes your credit limit, while a credit builder loan involves saving money in an account while making small payments. Both help establish positive payment history. This proactive approach can significantly improve the FICO score impact over time.
The Long-Term Financial Implications of FICO Score Impact
The FICO score impact extends far beyond just loan rates. A strong credit score can open doors to:
- Lower Insurance Premiums: In many states, insurance companies use credit-based insurance scores to determine your premiums. A higher FICO score can mean lower rates on auto and home insurance.
- Easier Rental Approvals: Landlords often check credit scores as part of their tenant screening process. A good score can make it easier to secure housing.
- Better Employment Opportunities: Some employers, particularly those in financial or security-sensitive roles, may check your credit report (with your permission). While they don’t see your score, a responsible credit history reflects positively on your character.
- Lower Utility Deposits: Utility companies may waive or reduce security deposits for customers with excellent credit.
Understanding and proactively managing your FICO score is not just about getting a better deal on a loan today; it’s about building a robust financial foundation for your future. The cumulative FICO score impact of maintaining good credit habits can save you thousands of dollars and reduce financial stress over your lifetime.
Dispelling Common FICO Score Myths
To truly harness the power of your FICO score, it’s important to distinguish fact from fiction:
- Myth: Checking your own credit score hurts it.
Fact: Checking your own credit score or report (a “soft inquiry”) has no impact on your FICO score. Only “hard inquiries” from lenders when you apply for new credit can slightly lower it. - Myth: Carrying a small balance on your credit card helps your score.
Fact: While having an open, active account is good, carrying a balance just to “help” your score is unnecessary and costs you money in interest. Paying your balance in full each month is the best strategy for a positive FICO score impact. - Myth: All debt is bad for your score.
Fact: Responsible use of various types of credit (a healthy credit mix) can actually help your score by demonstrating your ability to manage debt. It’s irresponsible debt, like high utilization or late payments, that harms it. - Myth: Once a negative item disappears, your score instantly recovers.
Fact: While the removal of negative items (like bankruptcies after 7-10 years) will certainly help, the recovery isn’t always instant. Your score also depends on the positive credit history you’ve built since then.
Conclusion: Empowering Your Financial Future with FICO Score Awareness
The FICO score is a dynamic and powerful tool in the financial landscape. Its periodic updates and the significant FICO score impact of even a 20-point shift on loan rates and other financial aspects cannot be overstated. By understanding the factors that influence your score, staying informed about recent FICO score updates, and implementing consistent, responsible credit habits, you can take control of your financial destiny.
Don’t underestimate the power of those few points. Whether you’re planning to buy a home, purchase a car, or simply want to ensure you’re getting the best possible terms on your credit cards, a diligent approach to your FICO score will pay dividends for years to come. Start monitoring your credit reports regularly, practice smart credit utilization, and make on-time payments a non-negotiable habit. Your future self – and your wallet – will thank you for mastering the FICO score impact.