Unlocking Public Assistance: An Expert’s Guide to Navigating Benefits and Financial Aid
Anúncios
When you hear “public assistance,” what comes to mind? For many, it’s a vague concept associated with unemployment or a last-resort safety net. Yet, the reality is far more common and complex; nearly one in five American households receives some form of government aid, making it a standard feature of the U.S. economic landscape. This isn’t a sign of failure, but a reflection of a system designed to support working families, students, seniors, and those facing unexpected hardship.
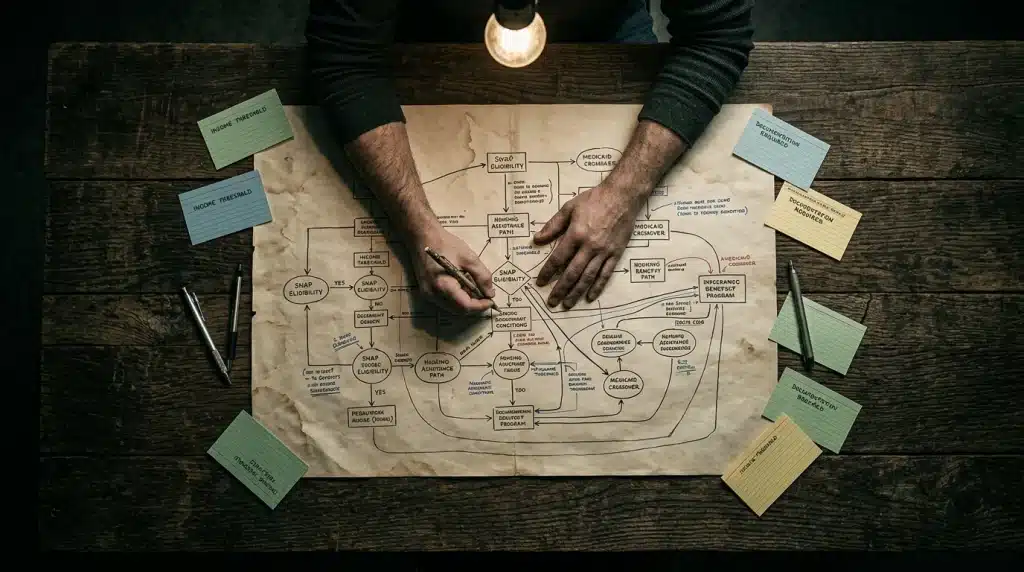
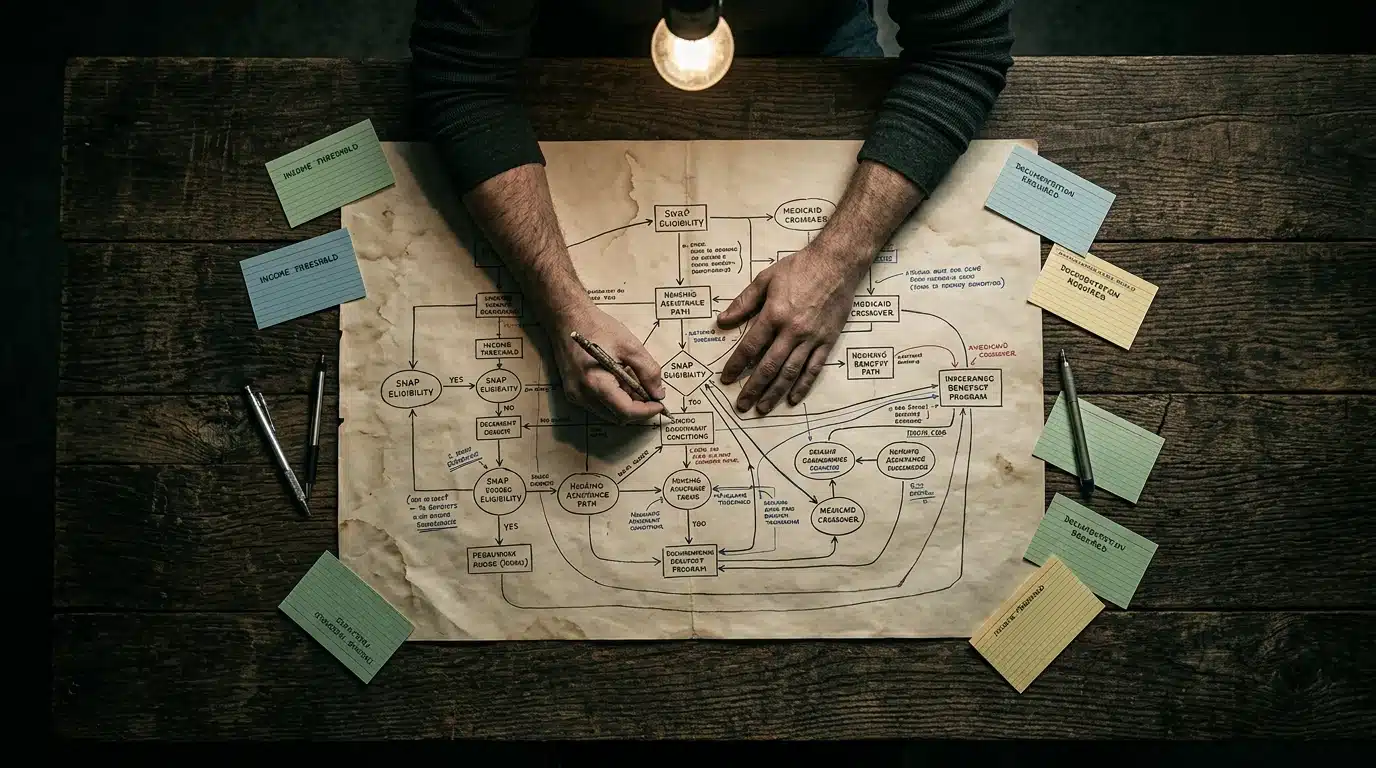
Despite its prevalence, navigating the world of benefits can feel like an impossible task. The system is a sprawling network of federal, state, and local programs, each with its own set of intricate rules, income thresholds, and application processes. It’s a world where applying for one form of aid can unexpectedly impact your eligibility for another, and where simple paperwork mistakes are a leading cause of denial for families who genuinely qualify for help.
This guide is designed to cut through that confusion. Drawing on insights from financial planners, public benefits lawyers, and policy experts, we will demystify the process from start to finish. You will learn how to identify the key categories of aid you might have overlooked, adopt strategic application methods to maximize your chances of approval, and integrate these benefits into a sustainable long-term financial plan. Consider this your roadmap to turning a daunting process into an empowering step toward financial stability.
The Current Landscape of Government Benefits: What Professionals See
When most people hear the term government benefits, their minds often jump to one or two major programs like unemployment insurance or food assistance. While those are significant, what professionals in the field see is a much wider, more intricate network of support systems. The sheer variety of aid available is often the biggest surprise for individuals just starting to explore their options. It’s a common misconception that public assistance is only for those who are out of work; in reality, many programs are designed to supplement income for working families, students, and seniors.
The scale of these programs is massive. According to the U.S. Census Bureau, nearly one in five U.S. households received some form of government assistance in recent reporting periods. That figure highlights a simple truth. These benefits are a standard part of the national economic structure. Understanding this system is a key part of mastering your financial future, not a sign of failure.
Anúncios
This reality forces an important question: if so many people use these programs, why does navigating them feel like trying to solve a puzzle with half the pieces missing? The underrated factor here is how interconnected—and sometimes, how frustratingly separate—these programs can be. Applying for one benefit might affect your eligibility for another, creating a complex web of rules.
Key Categories of Aid: Beyond the Obvious
To make sense of it all, it helps to group benefits into several core categories. Thinking about them this way can simplify the search process and reveal types of aid you might not have considered. Each category targets a different life need, from putting food on the table to keeping a roof over your head.
- Food and Nutrition Assistance: This includes well-known programs like the Supplemental Nutrition Assistance Program (SNAP) and the Special Supplemental Nutrition Program for Women, Infants, and Children (WIC), which provide funds specifically for purchasing groceries.
- Housing Support: Programs like Section 8 housing choice vouchers and public housing help make rent affordable. There are also emergency programs for preventing eviction or finding temporary shelter.
- Healthcare Coverage: Medicaid and the Children’s Health Insurance Program (CHIP) offer free or low-cost health insurance to millions of adults and children who meet income requirements.
- Direct Financial and Utility Assistance: This is a broad category that covers everything from Temporary Assistance for Needy Families (TANF) to the Low Income Home Energy Assistance Program (LIHEAP), which helps with heating and cooling bills.
One emerging trend that professionals are closely watching is the push toward integrated benefits applications. Some states are developing online portals where residents can apply for multiple programs at once. This shift is a response to years of feedback about confusing, separate application processes—and let’s be honest, the paperwork can be a workout on its own. While not yet universal, this move toward simplification is a promising development in navigating the new financial landscape and making aid more accessible.
Strategic Application: Professional Tips for Maximizing Eligibility
Approaching a benefits application isn’t just about filling out paperwork; it’s about presenting a clear and accurate picture of your financial situation. The difference between approval and denial often comes down to preparation. Think of it less like taking a test and more like building a case. Every document and number you provide is a piece of evidence supporting your eligibility.
The system is designed with specific rules, and understanding them is your first strategic advantage. A surprising number of applicants are denied not because they don’t qualify, but because of simple, avoidable errors. This is a game of details.
Understanding Income and Asset Thresholds
Before you even begin, it’s required to understand how agencies define your financial standing. Most programs look at two key figures: countable income and countable assets. Countable income includes obvious sources like wages and salaries, but it can also include things like unemployment benefits, alimony, and even some freelance work. What trips people up? Many programs disregard a certain amount of earned income to encourage work, a detail often buried in the fine print.
Assets are treated similarly. Not everything you own counts against you. For instance, your primary home, one vehicle, and personal belongings are typically exempt. savings accounts, secondary properties, or extra vehicles are usually considered countable. According to research from the Center on Budget and Policy Priorities, nearly 22% of initial application rejections for programs like SNAP stem from misreporting or misunderstanding asset limits. Knowing exactly what the program counts is the first step toward a successful application.
The ‘Do’s and Don’ts’ of Your Application
Navigating the application process requires a methodical approach. Caseworkers review hundreds of files, so clarity and completeness are your best allies. Following a structured plan can significantly improve your odds of a smooth process and a positive outcome.
- Do Gather Documents First: Before you type a single word, collect everything you might need. This includes recent pay stubs, tax returns from the previous year, bank statements, social security cards for all household members, and proof of address like a utility bill.
- Do Be Meticulously Honest: It can be tempting to omit a small side job or a little bit of savings, but inconsistencies are a major red flag. Agencies have systems to verify information, and being caught providing false data can lead to disqualification and even fraud charges.
- Don’t Leave Blanks: If a question doesn’t apply to you, write “N/A” (Not Applicable) instead of leaving it blank. An empty field can be interpreted as an oversight, potentially stalling your application while the agency requests clarification. Think about mastering your financial future by treating this process with the seriousness it deserves.
- Do Keep Copies: Make copies—digital or physical—of every single page you submit. This creates a personal record that is invaluable if your application is lost or if you need to reference it during an appeal.
Common Mistakes to Avoid
The most frequent error applicants make is underestimating the scope of “household.” Most benefit programs require you to include everyone who lives and shares meals with you, even if they aren’t related or applying for benefits themselves. Their income and assets may impact your household’s overall eligibility criteria.
Anúncios
Another common pitfall is failing to report changes in a timely manner. If you get a new job or someone moves out of your home after you apply, you are typically required to report it within a specific timeframe, usually 10-30 days. Failing to do so can result in having to pay back benefits later on.
It sounds simple, but double-checking your math is critical.
Leveraging Local Resources for Support
You don’t have to go through this process alone. Many local non-profits and community action agencies offer free assistance with benefits applications. These counselors—some of them are former caseworkers—know the system’s quirks and can help you avoid common mistakes. Trying to figure it all out yourself is like trying to fix a car engine with only a user manual; an expert’s guidance makes the job much easier.
Your local Department of Health and Human Services office is another key resource. They can clarify confusing questions and provide checklists specific to the programs you’re applying for. These professionals can also offer insights into navigating the new financial landscape when your circumstances change. Using these support systems isn’t a sign of weakness; it’s one of the smartest application strategies you can employ. Their help can ensure your application accurately reflects your need, setting you up for the best possible outcome.
You don’t change the whole dish. You use the new ingredient—the benefit—to free up other resources, like your income, so they can be used for different purposes like debt reduction or savings.
— Maria Rodriguez, Certified Financial Planner
| Benefit Type | Primary Financial Impact | Long-Term Consideration |
|---|---|---|
| SNAP (Food Assistance) | Frees up cash from grocery budget for savings or debt. | Non-taxable; does not count as earned income for most credit applications. |
| Medicaid (Health Coverage) | Eliminates or drastically reduces unpredictable medical costs and insurance premiums. | Asset limits may apply, which can affect savings strategies for some individuals. |
| Unemployment Insurance | Provides taxable income replacement during job loss. | Must be reported on tax returns; can affect tax liability and eligibility for tax credits. |
| Housing Choice Vouchers (Section 8) | Reduces housing costs, freeing up a large portion of income. | Can impact ability to move and may have long waiting lists, affecting long-term mobility. |
Financial Planning with Public Aid: An Expert’s Perspective
Receiving public assistance is often viewed solely as a short-term lifeline, but financial experts see it differently. They view these benefits as a strategic component that can be woven into a larger financial plan. Integrating aid correctly can stabilize your present situation while building a stronger foundation for the future. It’s not just about survival; it’s about creating a path forward.
Maria Rodriguez, a Certified Financial Planner who specializes in low-to-moderate income households, explains it as adding a temporary, but powerful, ingredient to a familiar recipe. “You don’t change the whole dish,” she says. “You use the new ingredient—the benefit—to free up other resources, like your income, so they can be used for different purposes like debt reduction or savings.” This shift in mindset is underlying to turning aid into a tool for growth rather than a simple patch.
Balancing Benefits with Personal Savings Goals
One of the most immediate effects of receiving assistance is the creation of breathing room in your budget. When a benefit like the Supplemental Nutrition Assistance Program (SNAP) covers a significant portion of your grocery bill, the money you would have otherwise spent is now available. Suddenly, you have capital that can be directed toward long-term goals. A study from the National Bureau of Economic Research suggested that households receiving SNAP benefits were able to increase their liquid savings by an average of $550 over a six-month period.
This newfound cash flow is a powerful opportunity. You can use it to build an emergency fund, contribute to a retirement account, or pay down high-interest debt. But does this create a dependency that’s hard to break? The key is to create a “step-down” plan for when the benefits end, gradually reallocating your income back to the expenses the aid once covered. The initial boost from understanding the basics of benefits and smart spending can set a positive trajectory for years.
Thinking of benefits as a temporary subsidy for your savings goals is the healthiest approach.
To clarify how different benefits fit into your financial picture, consider their primary function and impact:
| Benefit Type | Primary Financial Impact | Long-Term Consideration |
|---|---|---|
| SNAP (Food Assistance) | Frees up cash from grocery budget for savings or debt. | Non-taxable; does not count as earned income for most credit applications. |
| Medicaid (Health Coverage) | Eliminates or drastically reduces unpredictable medical costs and insurance premiums. | Asset limits may apply, which can affect savings strategies for some individuals. |
| Unemployment Insurance | Provides taxable income replacement during job loss. | Must be reported on tax returns; can affect tax liability and eligibility for tax credits. |
| Housing Choice Vouchers (Section 8) | Reduces housing costs, freeing up a large portion of income. | Can impact ability to move and may have long waiting lists, affecting long-term mobility. |
Impact on Taxes and Future Financial Stability
What many people don’t realize is the varied tax treatment of government benefits. While aid like SNAP, WIC, and Medicaid is generally not considered taxable income, unemployment compensation is. This distinction is critical for financial planning, as receiving $1,200 in unemployment benefits has a different net value than receiving a $1,200 housing subsidy — a surprisingly frequent point of confusion that can lead to an unexpected tax bill.
Beyond taxes, the integration of public aid requires a dynamic approach to navigating your personal finances. Some programs, particularly Medicaid and Supplemental Security Income (SSI), have strict asset limits. A household might have to spend down savings to become eligible, which feels counterintuitive to long-term planning. This is where professional advice becomes required to structure assets in compliant ways, for instance, through specific trusts or ABLE accounts for those with disabilities.
Ultimately, the goal is to use these programs as a bridge, not a destination. By strategically managing the aid you receive, you can address immediate needs while keeping your eyes fixed on the objective of achieving lasting financial independence.
Advocacy and Appeals: When to Seek Professional Help
Receiving a denial letter for a benefit you desperately need can feel like hitting a brick wall. While it’s tempting to simply give up, the data suggests that’s often the wrong move. The underrated factor here is that many initial denials are overturned on appeal, especially when the applicant has professional support. It’s a tough reality.
Knowing when to call for backup is key. If your application was denied due to complex eligibility rules, missing documentation, or an administrative error, it’s probably time to seek help. Navigating the appeals process alone is like trying to argue a case without knowing the law — you’re at a significant disadvantage. According to a study by the Center on Budget and Policy Priorities, applicants with legal representation have a success rate in disability appeals that is nearly 53% higher than those without it.
What does that professional help actually do? An advocate or legal aid attorney understands the specific language and evidence the agency requires. “We see clients who are rightfully eligible but failed to present their case in the precise way the bureaucracy demands,” explains Mark Rivera, a public benefits lawyer. “Our job is to translate their real-life situation into the required legal framework, which dramatically improves their chances.” Understanding the system is a huge part of navigating the new financial landscape created by a change in income.
This isn’t just for complex cases, either. Sometimes, just having a professional make the phone calls gets your case noticed. For those just starting out, even mastering the basics of an application can be a challenge, let alone an appeal.
Don’t assume you can’t afford this kind of assistance. Many legal aid societies and non-profit advocacy groups offer free or low-cost services based on income. Seeking their counsel isn’t an admission of defeat; it’s a strategic step toward securing the support you are entitled to receive.
Future-Proofing Your Access to Benefits: What Experts Advise
Securing benefits isn’t a one-time event; it’s an ongoing process of staying aware. Policies governing public assistance are constantly in flux, with the National Conference of State Legislatures reporting that over 1,200 bills related to public benefits were considered just in the last legislative session. Staying informed is like checking the weather before a long road trip—you need to know what conditions are ahead to prepare effectively. It’s about proactive planning.
So, how can you keep up without getting overwhelmed? Experts suggest focusing on reliable sources. Subscribing to email updates from official government agencies like the Social Security Administration or your state’s Department of Health and Human Services is a great first step. non-profit advocacy groups often provide clear, easy-to-understand summaries of proposed changes. This is a key part of mastering your financial future and ensuring stability.
The underrated factor here is the power of local community. Joining online forums or local support groups can provide real-time updates and shared experiences from people in similar situations. These networks often hear about administrative changes (—the kind that don’t always make headlines but directly impact your application—) long before official announcements are widely circulated. It’s about building a web of information.
Ultimately, being prepared for shifts in policy is the best defense. Legislative debates around work requirements for SNAP and adjustments to housing assistance funding are ongoing topics. By staying alert to these discussions, you gain the ability to adapt your financial strategy. Understanding how to react to these shifts is necessary when navigating the new financial landscape. Your awareness today is your security for tomorrow.
From Applicant to Advocate: Your Next Move
Understanding the landscape of public assistance is more than an academic exercise; it’s a critical component of personal financial resilience. The true takeaway isn’t just a list of programs or application tips, but a basic shift in perspective. You are not merely a passive applicant hoping for approval, but the active manager of your own case. The system may be complex, but it is not unknowable, and your proactive engagement is the single most important factor in your success.
So, what is the one practical step you can take after reading this? Before a crisis hits, conduct a personal readiness audit. Use the information here to identify the local non-profits, legal aid societies, and community action agencies in your area. Bookmark their websites and save their contact information. By building your support network now, you transform a potential moment of panic into a moment of planned, decisive action. In the intricate dance of benefits and bureaucracy, preparation is not just power—it is peace of mind.
Frequently Asked Questions
How do professionals determine which government benefits are best suited for an individual’s situation?
Professionals conduct a holistic assessment of an individual’s core life needs, including food, housing, healthcare, and direct financial circumstances. They categorize potential aid to identify all possible support systems, not just the most obvious ones. This full approach ensures that no opportunity for assistance is overlooked during the evaluation process.
What are the most common reasons for benefit application denials, according to experts?
According to experts, many denials are due to simple, avoidable errors rather than ineligibility. The most common mistakes include misreporting or misunderstanding income and asset limits, submitting incomplete applications with blank fields, and incorrectly defining the household size by omitting members who live and share meals with the applicant.
Can receiving one type of government benefit affect eligibility for others?
Yes, receiving one type of government benefit can affect your eligibility for others. The system is an interconnected web of rules where the aid from one program can alter your financial profile for another. This is why understanding the specific regulations for each benefit is important for successful navigation and financial planning.
How often should one review their benefit eligibility with a financial professional?
You should review your eligibility whenever a significant life event occurs that changes your financial or household situation. This includes events like getting a new job, a change in income, or someone moving into or out of your home. Failing to report these changes in a timely manner, typically within 10-30 days, can lead to disqualification or overpayment issues.
Are there specific resources experts recommend for understanding complex benefit regulations?
Experts strongly recommend leveraging local, free resources for guidance with complex regulations. Key recommendations include non-profit organizations and community action agencies that specialize in benefit applications. your local Department of Health and Human Services office is a primary resource for official checklists and clarifying specific rules.