Quarterly Financial Check-Up: Optimize Your Personal Finances
Anúncios
Quarterly Financial Check-Up: Optimize Your Personal Finances
In the whirlwind of daily life, it’s easy to let personal finances fall by the wayside. We set goals at the beginning of the year, perhaps even draft a budget, but without regular maintenance, even the best intentions can falter. This is where a consistent quarterly financial check-up becomes not just beneficial, but absolutely essential. Think of it like a routine health check-up for your money; it allows you to identify potential issues early, celebrate successes, and make necessary adjustments to ensure your financial well-being.
A quarterly financial check-up is more than just glancing at your bank balance. It’s a structured, proactive approach to managing your money that empowers you to stay on track towards your financial goals, adapt to life changes, and build a stronger financial future. This comprehensive guide will walk you through five critical areas to review during your quarterly financial check-up, providing actionable steps and insights to help you optimize your personal finances effectively.
Why is a quarterly financial check-up so important? Life is dynamic. Your income might change, expenses could fluctuate, new financial products might emerge, or your personal goals might evolve. A quarterly review provides the perfect cadence to catch these shifts and adjust your strategy accordingly. It prevents small problems from snowballing into larger ones and ensures that your financial plan remains aligned with your current circumstances and aspirations. By dedicating a few hours each quarter to this vital exercise, you’re investing in peace of mind and long-term financial security.
Anúncios
1. Income and Expense Analysis: Understanding Your Cash Flow
The foundation of any sound financial plan is a clear understanding of where your money comes from and where it goes. Your quarterly financial check-up should always begin with a thorough income and expense analysis. This isn’t just about knowing your net income; it’s about dissecting your cash flow to identify patterns, opportunities for savings, and potential areas of overspending.
Reviewing Your Income Streams
Start by listing all your income sources for the past three months. This includes your primary salary, freelance income, bonuses, dividends, interest, rental income, or any other money flowing into your accounts. Have there been any changes? Did you receive a raise? Did a side hustle generate more or less than expected? Understanding these fluctuations is crucial for accurate budgeting and forecasting.
- Track all sources: Ensure every dollar earned is accounted for.
- Identify trends: Are certain income streams growing or shrinking?
- Plan for variability: If you have variable income, how can you better manage it?
Deep Dive into Your Expenses
This is often the most revealing part of the quarterly financial check-up. Go through all your spending for the last three months. Categorize everything: housing, utilities, groceries, transportation, dining out, entertainment, subscriptions, healthcare, personal care, and so on. Many budgeting apps and banking platforms offer automated categorization, making this task much easier.
As you review your expenses, ask yourself:
- Are there any surprises? Did you spend significantly more in one category than you anticipated?
- Where can you cut back? Identify non-essential spending that could be reduced or eliminated without significantly impacting your quality of life. For example, unused subscriptions, excessive dining out, or impulse purchases.
- Are your essential expenses stable? Have your rent, mortgage, utility bills, or insurance premiums changed?
- Are you maximizing savings? Look for opportunities to save on recurring bills, like negotiating insurance rates or switching utility providers.
The goal here is not to deprive yourself, but to make conscious choices about your spending. By understanding exactly where your money is going, you gain control. This analysis informs your budget for the next quarter and helps you align your spending with your financial goals.
A robust income and expense analysis during your quarterly financial check-up is the bedrock upon which all other financial decisions are built. Without this clarity, you’re essentially navigating your finances blindfolded.
2. Debt Management and Reduction Strategies
Debt can be a significant impediment to financial freedom. During your quarterly financial check-up, it’s imperative to take a hard look at all your outstanding debts and assess your progress in reducing them. This includes credit card debt, personal loans, student loans, car loans, and your mortgage.
Inventory Your Debts
List every debt you owe, including:
- The creditor
- The outstanding balance
- The interest rate
- The minimum monthly payment
- The due date
This comprehensive overview helps you prioritize which debts to tackle first. High-interest debts, like credit card balances, typically demand immediate attention due to their compounding nature.
Anúncios
Assess Your Debt Reduction Progress
Compare your current debt balances to those from the previous quarter. Are you making progress? Are you sticking to your debt repayment plan? If not, why? Understanding the ‘why’ is crucial for adjusting your strategy.
- Are you paying more than the minimum? If possible, allocate extra funds to your highest-interest debts.
- Have your interest rates changed? Keep an eye on variable interest rates, especially on credit cards.
- Are you incurring new debt? If so, identify the root cause and address it.
Explore Debt Reduction Strategies
Your quarterly financial check-up is the perfect time to re-evaluate your debt reduction strategy. Consider:
- Debt Snowball Method: Pay off the smallest debt first to gain momentum, then roll that payment into the next smallest debt.
- Debt Avalanche Method: Focus on paying off the debt with the highest interest rate first, saving you money in the long run.
- Balance Transfers: If you have good credit, consider transferring high-interest credit card balances to a card with a 0% introductory APR. Be mindful of transfer fees and the promotional period.
- Debt Consolidation Loans: For multiple high-interest debts, a personal loan with a lower interest rate can consolidate them into one manageable payment.
- Negotiating with Creditors: If you’re struggling to make payments, contact your creditors to see if they offer hardship programs or lower interest rates.
Successfully managing and reducing debt is a marathon, not a sprint. A regular quarterly financial check-up ensures you’re consistently moving towards a debt-free future, freeing up more of your income for savings and investments.
3. Savings and Emergency Fund Review
Having a robust savings strategy, particularly an adequately funded emergency fund, is a cornerstone of financial security. Your quarterly financial check-up must include a detailed review of your savings accounts and their alignment with your short-term and long-term goals.
Emergency Fund Assessment
An emergency fund should ideally cover 3-6 months of essential living expenses. During your quarterly financial check-up, check the balance of your emergency fund. Is it fully funded? If not, what is your plan to get there? Have your essential expenses changed, requiring an adjustment to your emergency fund target?
- Calculate your target: Re-evaluate 3-6 months of current essential expenses.
- Assess current balance: How close are you to your goal?
- Automate contributions: Set up automatic transfers to ensure consistent growth.
- Accessibility: Is your emergency fund easily accessible but separate from your daily spending accounts?
Reviewing Short-Term and Long-Term Savings Goals
Beyond your emergency fund, you likely have other savings goals: a down payment for a house, a new car, a vacation, education, or retirement. Your quarterly financial check-up is the time to check on the progress of each of these goals.
- Short-Term Goals (1-3 years): Are you on track for that vacation next year? Is your new car fund growing as planned?
- Mid-Term Goals (3-10 years): How are you progressing towards a home down payment or a child’s education?
- Long-Term Goals (10+ years): While retirement savings are often tied to investments, the initial contributions and strategy start here.
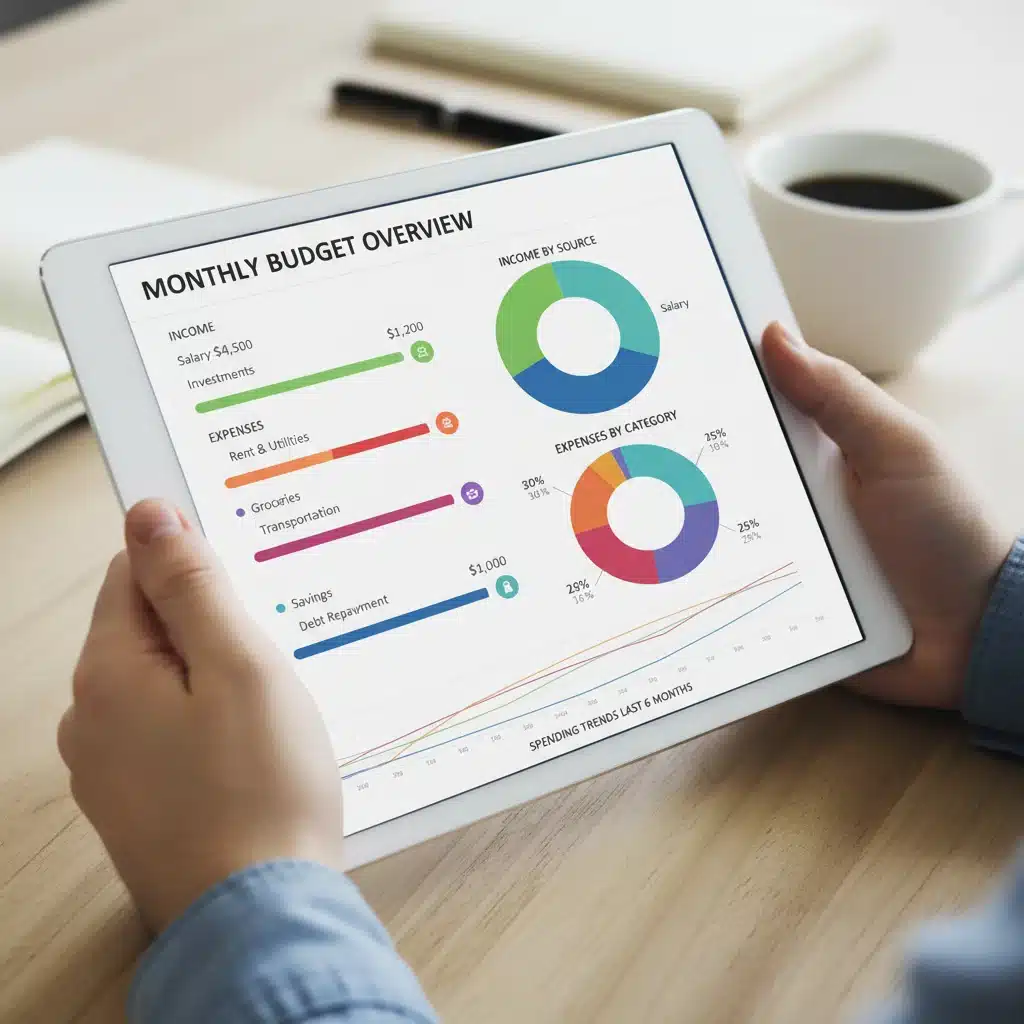
For each goal, consider:
- Target amount: Is the original target still realistic?
- Current progress: How much have you saved so far?
- Contribution rate: Are you contributing enough each month or quarter to reach your goal on time?
- Interest earned: Is your savings account offering a competitive interest rate? Consider high-yield savings accounts.
If you find yourself off track, don’t despair. Use this quarterly financial check-up as an opportunity to adjust. Can you reallocate funds from less critical areas? Can you increase your income? Or do you need to adjust the timeline or scope of your goal?
Consistent monitoring of your savings during your quarterly financial check-up ensures that your financial safety net is strong and your aspirations are within reach.
4. Investment Portfolio Performance and Strategy
For those with investments, your quarterly financial check-up is an opportune time to review your portfolio’s performance and ensure it remains aligned with your risk tolerance and long-term financial objectives. This is not about panic selling or buying based on short-term market fluctuations, but rather a strategic assessment.
Performance Review
Take a look at how your investments have performed over the past quarter and year-to-date. Compare your returns against relevant benchmarks (e.g., S&P 500 for US equities, a global bond index for fixed income). Understand that market fluctuations are normal, but consistent underperformance might warrant a deeper look.
- Review statements: Go through your brokerage statements, mutual fund reports, and retirement account summaries.
- Assess individual holdings: How are your individual stocks, bonds, and funds performing?
- Understand market context: Don’t just look at numbers; understand what has been happening in the broader market.
Asset Allocation Check
Your asset allocation – the mix of different asset classes like stocks, bonds, and cash – is arguably the most critical determinant of long-term returns and risk. During your quarterly financial check-up, check if your current asset allocation still matches your target allocation.
Market movements can cause your portfolio to drift from its original target. For example, a strong stock market might make your equity allocation higher than intended. This is where rebalancing comes in.
- Identify drift: Has your allocation shifted significantly from your target?
- Rebalance if necessary: Sell a portion of overperforming assets and buy underperforming ones to bring your portfolio back into alignment. This helps manage risk and maintains your desired exposure to different asset classes.
- Consider your life stage: As you get closer to retirement, your risk tolerance might decrease, necessitating a more conservative allocation.
Contribution and Diversification Review
Are you consistently contributing to your investment accounts, especially retirement accounts like 401(k)s and IRAs? Maxing out these accounts, especially if your employer offers a match, is a powerful way to grow wealth.
Also, ensure your portfolio remains well-diversified across different sectors, industries, geographies, and asset types. Over-concentration in one area can expose you to unnecessary risk.
- Maximize contributions: Are you taking full advantage of tax-advantaged accounts?
- Diversification check: Are you spread across various investments to mitigate risk?
- Review fees: Are you paying excessive fees on your investment products? High fees can significantly erode returns over time.
A regular investment review as part of your quarterly financial check-up ensures your money is working as hard as possible for you and that you’re comfortable with the level of risk you’re taking on.
5. Financial Goals and Future Planning
The final, and perhaps most motivating, part of your quarterly financial check-up is to revisit your financial goals and make plans for the future. Are your goals still relevant? Have new goals emerged? Are you on track to achieve them?
Re-evaluate Your Financial Goals
Life happens. A job change, a new family member, a health event, or even a shift in personal priorities can all impact your financial goals. Use your quarterly financial check-up to:
- Review existing goals: Are your short-term, mid-term, and long-term goals still what you want to achieve?
- Adjust timelines or amounts: Do your goals need to be updated based on your current financial situation or life circumstances?
- Set new goals: Have any new aspirations come to light that require financial planning?
Be specific with your goals. Instead of ‘save more money,’ aim for ‘save $5,000 for a down payment on a new car by December 2024.’ Specificity makes goals measurable and achievable.
Future Planning: Beyond the Quarter
A quarterly financial check-up isn’t just about the past three months; it’s also about looking ahead. Consider these forward-looking aspects:
- Tax Planning: Are there any tax-saving opportunities you can take advantage of before year-end? Have your income or deductions changed in a way that impacts your tax liability?
- Insurance Review: Check your insurance policies (health, auto, home, life, disability). Are your coverages adequate? Are you getting the best rates? Life events often necessitate changes in insurance needs.
- Estate Planning: While not a quarterly task, ensure your beneficiaries are up-to-date on all accounts. If you have a will or trust, a quick check to see if it reflects your current wishes is prudent.
- Career Development: How does your career path align with your financial aspirations? Are there opportunities for professional development that could lead to higher income?
- Inflation Impact: Consider how rising costs might affect your future purchasing power and adjust your savings targets accordingly.
By regularly reviewing and adjusting your financial goals and future plans, your quarterly financial check-up transforms from a mere accounting exercise into a powerful tool for manifesting your ideal financial life. It provides clarity, direction, and the motivation to stay committed to your financial journey.
Making Your Quarterly Financial Check-Up a Habit
The key to success with a quarterly financial check-up is consistency. It might feel like a chore at first, but with each passing quarter, it will become an empowering habit that gives you immense control over your financial destiny. Here are some tips to integrate it into your routine:
- Schedule it: Put a recurring appointment in your calendar for the first week of each new quarter. Treat it like an important business meeting.
- Choose a dedicated time: Find a time when you can focus without distractions.
- Gather your documents: Before you start, collect all necessary statements – bank, credit card, investment, loan, and pay stubs.
- Use technology: Leverage budgeting apps, financial aggregators, and online banking tools to streamline the process.
- Don’t aim for perfection: The goal is progress, not perfection. If you miss a quarter or don’t get through everything, just pick up where you left off.
- Celebrate small wins: Acknowledge your progress, even if it’s just paying off a small debt or increasing your savings by a little. Positive reinforcement helps maintain motivation.
- Consider professional help: If your finances are complex or you feel overwhelmed, a financial advisor can provide valuable guidance during your quarterly financial check-up and beyond.
A quarterly financial check-up is not about judging past mistakes; it’s about learning from them and proactively shaping a better financial future. It’s an opportunity to ensure your money is working for you, aligning with your values, and propelling you towards your most ambitious goals.
Conclusion: Your Path to Financial Empowerment
Taking the time for a regular quarterly financial check-up is one of the most impactful actions you can take for your personal finances. It provides a structured framework to understand your cash flow, manage debt, build robust savings, optimize investments, and ensure your financial goals remain on track. By consistently engaging in this vital practice, you move beyond passive money management to become an active, informed, and empowered participant in your financial journey.
Embrace the discipline of the quarterly financial check-up. It’s not just about numbers; it’s about building resilience, achieving dreams, and securing a future where you have the freedom and flexibility to live life on your own terms. Start today, and watch your financial confidence and prosperity grow, quarter by quarter.