Federal Student Loan Forgiveness 2026: Eligibility & Application Guide
Anúncios
Navigating Federal Student Loan Forgiveness 2026: Your Essential Guide to Potential Relief
The landscape of federal student loan forgiveness is constantly evolving, and for millions of Americans, understanding the latest changes and opportunities for relief is paramount. As we look towards 2026, new initiatives, policy adjustments, and ongoing programs continue to offer pathways to debt reduction or even complete elimination. This comprehensive guide aims to demystify the federal student loan forgiveness 2026 landscape, providing you with the most up-to-date information on eligibility, application processes, and crucial deadlines, including the highly anticipated $10,000 relief. Whether you’re a long-time borrower or new to the repayment journey, grasping these details is essential to securing the financial relief you may deserve.
Student loan debt has long been a significant burden for many, impacting financial stability, career choices, and major life decisions. Recognizing this, the U.S. government has implemented various programs designed to alleviate this pressure. However, these programs are often complex, with specific criteria and application windows that can be challenging to navigate. Our goal is to cut through the confusion, offering clear, actionable advice to help you determine your eligibility for federal student loan forgiveness 2026 and guide you through the necessary steps.
Understanding the Current State of Federal Student Loan Forgiveness
Before diving into the specifics of 2026, it’s crucial to understand the foundation of federal student loan forgiveness programs. These initiatives are generally categorized into several main types, each with unique requirements and benefits. The key is to identify which program, or combination of programs, best suits your individual circumstances.
The Ever-Evolving Landscape: What’s New for 2026?
While the broader strokes of federal student loan forgiveness remain consistent, specific details, such as eligibility thresholds, application windows, and the scope of relief, can shift. For 2026, borrowers are keenly watching for updates on potential new rounds of blanket forgiveness, adjustments to existing programs like Public Service Loan Forgiveness (PSLF), and enhancements to Income-Driven Repayment (IDR) plans. The $10,000 relief, a significant point of discussion and action in recent years, continues to be a focus for many seeking immediate financial alleviation. Understanding these updates is key to maximizing your chances of receiving student loan forgiveness 2026.
Anúncios
Key Federal Student Loan Forgiveness Programs
Several established programs form the backbone of federal student loan forgiveness. Familiarizing yourself with these is the first step toward determining your potential eligibility:
- Public Service Loan Forgiveness (PSLF): Designed for individuals working full-time for qualifying non-profit organizations or government agencies. After 120 qualifying monthly payments under a qualifying repayment plan, the remaining balance on Direct Loans may be forgiven.
- Income-Driven Repayment (IDR) Plan Forgiveness: These plans adjust your monthly payment based on your income and family size. After 20 or 25 years of payments (depending on the plan and loan type), any remaining balance is forgiven. Recent adjustments, often referred to as the "IDR Adjustment," are making it easier for borrowers to reach forgiveness sooner by counting more periods towards the required time.
- Teacher Loan Forgiveness (TLF): Offers up to $17,500 in forgiveness for eligible teachers who teach full-time for five consecutive academic years in low-income schools or educational service agencies.
- Total and Permanent Disability (TPD) Discharge: For borrowers who are unable to engage in any substantial gainful activity due to a physical or mental impairment.
- Borrower Defense to Repayment: Provides relief to students whose schools engaged in misconduct, such as making false promises or defrauding students.
- Closed School Discharge: For borrowers who could not complete their program because their school closed.
Each of these programs has intricate requirements, and staying informed about any modifications is crucial for student loan forgiveness 2026. The government periodically reviews and updates these programs, often in response to economic conditions or legislative changes.
Anúncios
Are You Eligible for the $10,000 Relief in 2026?
The prospect of a $10,000 relief has been a significant talking point in student loan discussions. While previous attempts at broad forgiveness faced legal challenges, the Biden administration has continued to pursue targeted relief through various avenues, often leveraging existing laws. For borrowers hoping for the $10,000 relief in 2026, it’s important to understand the specific criteria that have been discussed and implemented in different forms.
Understanding the Targeted Relief Efforts
Historically, discussions around $10,000 in relief have often centered on borrowers meeting certain income thresholds or those who received Pell Grants. While a universal $10,000 forgiveness program for all federal borrowers has not materialized in the way some hoped, targeted approaches have provided similar levels of relief to specific groups. These include:
- Income-Based Relief: Often, relief programs are structured to benefit low- and middle-income borrowers, with specific adjusted gross income (AGI) limits. For instance, single filers earning below a certain AGI (e.g., $125,000) or married couples/heads of households below a higher threshold (e.g., $250,000) might be prioritized.
- Pell Grant Recipients: Borrowers who received Pell Grants during their education have often been a focus for additional relief, acknowledging their greater financial need during college.
- Borrowers in Specific Programs: Enhancements to existing programs like PSLF and IDR have effectively led to significant forgiveness for many, often exceeding the $10,000 mark for eligible individuals. The "fresh start" initiative for defaulted borrowers also represents a form of targeted relief.
It is vital to monitor official announcements from the U.S. Department of Education and Federal Student Aid (FSA) as 2026 approaches. Any new broad or targeted $10,000 relief initiatives would be widely publicized, along with clear eligibility requirements and application instructions. Do not rely on unofficial sources for such critical information.
How to Prepare for Potential $10,000 Forgiveness
Even without a definitive announcement for a new $10,000 relief program specifically for 2026, there are proactive steps you can take to position yourself favorably should one emerge:
- Ensure Your Information is Up-to-Date: Log in to your Federal Student Aid account (studentaid.gov) and verify that your contact information, loan details, and income records are current.
- Consolidate Your Loans (If Applicable): For some types of older federal loans (e.g., FFEL Program loans, Perkins Loans), consolidation into a Direct Consolidation Loan is often a prerequisite for eligibility for many federal forgiveness programs, including some IDR plans and PSLF. This could also be a factor in future targeted relief.
- Understand Your Loan Types: Only federal student loans are eligible for federal forgiveness programs. Private student loans are not. Know which types of loans you have.
- Monitor Official Channels: Regularly check studentaid.gov and official Department of Education press releases for any news regarding student loan forgiveness 2026.
Applying for Student Loan Forgiveness 2026: The Process
The application process for federal student loan forgiveness 2026 varies significantly depending on the specific program. However, some general principles and steps apply across the board. Missing deadlines or providing incomplete information can delay or even jeopardize your chances of relief.
General Application Steps and Best Practices
Regardless of the program, a structured approach to applying for student loan forgiveness is always best:
- Identify the Correct Program: Based on your employment, loan types, and financial situation, determine which federal student loan forgiveness program you are most likely to qualify for.
- Gather Necessary Documentation: This typically includes proof of income (tax returns, pay stubs), employment verification (for PSLF, TLF), and potentially medical documentation (for TPD). Keep copies of everything you submit.
- Complete the Application Form Accurately: Application forms are usually available on studentaid.gov or through your loan servicer. Read all instructions carefully and fill out every section completely and accurately.
- Submit Before Deadlines: Pay close attention to any announced deadlines. For the $10,000 relief, if a new initiative is launched, there will undoubtedly be a specific application window. For ongoing programs like PSLF or IDR, you need to submit annual certifications or applications.
- Keep Records: Maintain thorough records of all communications with your loan servicer and the Department of Education, including dates, names of representatives, and confirmation numbers.
Specifics for Public Service Loan Forgiveness (PSLF)
For those pursuing PSLF, the process involves several critical steps:
- Eligible Employer: Ensure your employer qualifies. This typically includes U.S. federal, state, local, or tribal government organizations, or non-profit organizations that are tax-exempt under Section 501(c)(3) of the Internal Revenue Code.
- Eligible Loans: Only Direct Loans qualify. If you have FFEL or Perkins Loans, you must consolidate them into a Direct Consolidation Loan.
- Qualifying Payments: You must make 120 qualifying monthly payments under a qualifying repayment plan (typically an IDR plan). Payments must be made while employed full-time by a qualifying employer.
- Employment Certification: Annually, or when you change employers, submit the PSLF Employment Certification Form (ECF). This is crucial for tracking your progress towards the 120 payments.
- Application for Forgiveness: After making 120 qualifying payments, you will submit a PSLF application.
The PSLF program has undergone significant improvements, including the limited PSLF Waiver and the IDR Adjustment, which have retroactively counted more payments towards forgiveness. These changes have made PSLF more accessible and forgiving for many. Keep an eye on any further adjustments that might impact student loan forgiveness 2026.
Navigating Income-Driven Repayment (IDR) Plans
IDR plans are a cornerstone of federal student loan forgiveness. They are crucial for managing monthly payments and are often a prerequisite for PSLF. The newest IDR plan, the Saving on a Valuable Education (SAVE) Plan, has replaced the REPAYE Plan and offers even more generous terms for many borrowers.
Understanding the SAVE Plan
The SAVE Plan significantly reduces monthly payments for many borrowers, especially those with lower incomes. Key features include:
- Lower Discretionary Income Calculation: The amount of income protected from payment calculations has increased, leading to lower monthly payments for many.
- Interest Subsidies: If your monthly payment doesn’t cover the accrued interest, the government covers the remaining interest, preventing your balance from growing.
- Shorter Forgiveness Timelines: Forgiveness could occur as early as 10 years for borrowers with original loan balances of $12,000 or less.
Enrolling in an IDR plan, particularly the SAVE Plan, is a critical step for many seeking student loan forgiveness 2026, as it can both lower your monthly burden and put you on track for eventual forgiveness.
Important Deadlines and What to Do Now
While specific deadlines for broad student loan forgiveness 2026 are yet to be announced, there are ongoing deadlines and actions you should take now to ensure you don’t miss out on existing opportunities or new ones as they emerge.
The June Deadline: What Does It Mean?
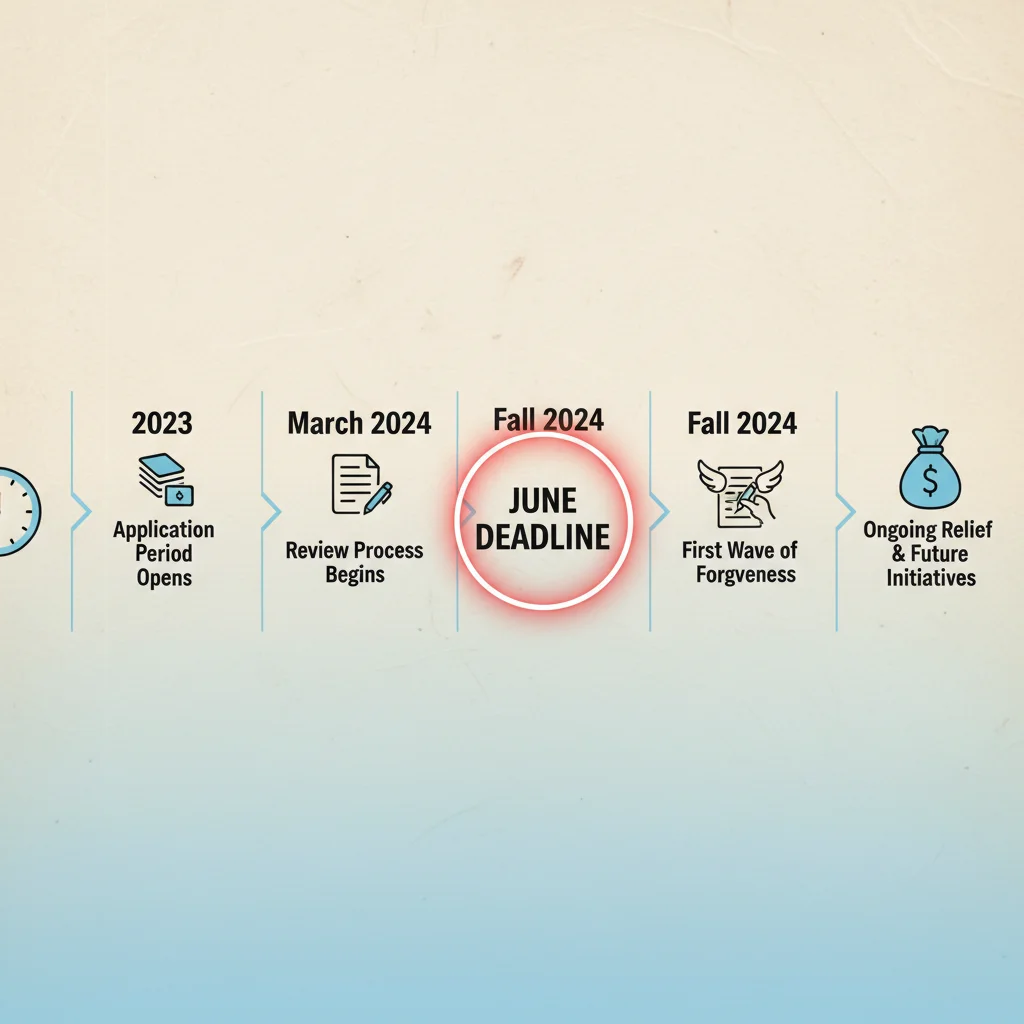
The mention of a "June deadline" often refers to specific, time-limited initiatives or temporary waivers that have been implemented. For instance, previous waivers, like the PSLF Waiver, had application deadlines. It is crucial to clarify which "June deadline" is being referred to in any official communication. Always consult studentaid.gov for the most accurate and current information regarding any upcoming deadlines related to student loan forgiveness 2026.
As of late 2024, a significant "June deadline" to be aware of relates to the IDR Account Adjustment. This adjustment, which aims to correct past administrative errors and count more periods towards IDR and PSLF forgiveness, has a deadline for borrowers with commercially held FFEL Program loans and Perkins Loans to consolidate them into a Direct Consolidation Loan. Failure to consolidate by this deadline (often June 30th of a given year, but always verify the exact date) could mean missing out on the benefits of the adjustment, which could lead to significant forgiveness. This is a critical step for many seeking student loan forgiveness 2026.
Proactive Steps to Take Before 2026
Even without a specific 2026 forgiveness program announced, there are actions you can take today:
- Review Your Loan Portfolio: Log into studentaid.gov. Understand what types of federal loans you have (Direct, FFEL, Perkins) and who your loan servicer is.
- Check Your Payment History: Ensure your loan servicer has an accurate record of your payments. If you suspect errors, dispute them immediately.
- Enroll in an IDR Plan: If you are not already on an IDR plan, consider enrolling, especially in the SAVE Plan. This can lower your payments and put you on the path to forgiveness.
- Certify Employment for PSLF: If you work in public service, make sure you are regularly submitting your PSLF Employment Certification Form.
- Update Contact Information: Ensure your loan servicer and FSA have your current mailing address, email, and phone number. This is how you’ll receive critical updates.
- Beware of Scams: Be highly skeptical of any offers that promise immediate or guaranteed student loan forgiveness for a fee. Official forgiveness programs do not charge for applications.
Common Pitfalls and How to Avoid Them
Navigating federal student loan forgiveness can be complex, and many borrowers encounter common pitfalls that can delay or prevent them from receiving relief. Being aware of these can help you avoid them.
Misunderstanding Loan Types
One of the most frequent mistakes is not understanding that only federal student loans are eligible for federal forgiveness programs. Private loans, obtained from banks or other private lenders, are not. Some older federal loans (like FFEL or Perkins loans) may need to be consolidated into a Direct Loan to qualify for certain programs. Always verify your loan types on studentaid.gov.
Incorrectly Tracking Payments for PSLF
For PSLF, it’s not just about making 120 payments; they must be qualifying payments. This means they must be made on time, for the full amount due, under a qualifying repayment plan, and while working full-time for a qualifying employer. Many borrowers fail to submit the PSLF Employment Certification Form regularly, leading to discrepancies in payment counts. Certify your employment annually, or when you change jobs, to ensure accurate tracking.
Missing Deadlines
Deadlines are critical. Whether it’s for annual IDR recertification, consolidating loans for the IDR Adjustment, or applying for specific relief initiatives, missing a deadline can have severe consequences. Set reminders, mark your calendar, and regularly check official FSA communications.
Falling Victim to Scams
The promise of student loan forgiveness often attracts scammers. Be wary of companies that charge upfront fees for services that are free through the Department of Education, promise immediate forgiveness, or ask for your FSA ID password. Legitimate help is available directly from your loan servicer or studentaid.gov.
Not Re-evaluating Your Options
Your financial situation and eligibility for programs can change. It’s wise to re-evaluate your repayment options and potential for student loan forgiveness 2026 periodically. New programs or adjustments to existing ones might make you eligible for relief you weren’t before.
The Future of Student Loan Forgiveness Beyond 2026
The conversation around student loan debt and forgiveness is ongoing. While specific policies can change with administrations and legislative priorities, the underlying need for relief and more manageable repayment options remains a significant issue. As we look beyond student loan forgiveness 2026, several trends and possibilities could shape the future landscape:
- Continued Focus on Targeted Relief: Rather than universal forgiveness, future efforts may continue to focus on targeted relief for specific groups, such as low-income borrowers, Pell Grant recipients, or those in specific professions.
- Enhancements to IDR Plans: The SAVE Plan represents a significant step forward in making IDR plans more effective. Further enhancements, such as shorter forgiveness timelines for all borrowers or more generous income protections, could be considered.
- Simplification of Programs: The complexity of current programs is a barrier for many. There may be a push for greater simplification and consolidation of forgiveness pathways to make them more accessible.
- Addressing Loan Interest: The issue of accruing interest, which can cause loan balances to grow even while borrowers are making payments, is a persistent concern. Policies that cap interest or subsidize it more broadly could be explored.
- State-Level Initiatives: Beyond federal programs, some states are exploring or implementing their own student loan relief programs, particularly for residents working in high-need areas or professions.
Staying informed about these broader discussions can help you anticipate future changes and plan your financial strategy. The most reliable source for information will always be the official Federal Student Aid website and announcements from the U.S. Department of Education.
Conclusion: Taking Control of Your Student Loan Debt
The journey to understanding and potentially receiving federal student loan forgiveness 2026 can feel overwhelming, but it is a journey worth undertaking. With potential relief of $10,000 or more available through various programs, being informed and proactive is your best strategy.
Remember to:
- Stay Informed: Regularly check studentaid.gov for the latest updates on programs, eligibility, and deadlines.
- Know Your Loans: Understand whether you have federal or private loans and their specific types.
- Act Proactively: Consolidate loans if necessary, enroll in appropriate repayment plans like SAVE, and certify your employment for PSLF.
- Document Everything: Keep meticulous records of all applications, communications, and payments.
- Seek Official Guidance: Rely only on your loan servicer and the Department of Education for accurate information, and beware of scams.
By taking these steps, you can significantly improve your chances of qualifying for student loan forgiveness 2026 and alleviating the burden of student debt. Your financial future is in your hands, and with the right information and action, you can navigate the path to relief successfully.