Unlock Financial Savings: The Power of a 750+ Credit Score in the U.S.
Anúncios
Understanding Your Credit Score: How a 750+ Score Can Save You Thousands Annually in the U.S.
In the intricate landscape of personal finance in the United States, your credit score stands as a pivotal indicator of your financial health and responsibility. Far from being just a number, a strong credit score, particularly one exceeding 750, acts as a powerful key, unlocking a world of financial advantages and potentially saving you thousands of dollars each year. This comprehensive guide will delve into the profound impact of a 750+ credit score, illustrating how it can significantly reduce your financial burdens and pave the way for greater financial freedom.
Many Americans are aware that a good credit score is beneficial, but the true magnitude of its impact often remains underestimated. We’re not just talking about getting approved for a credit card; we’re talking about tangible, substantial savings on major life purchases and ongoing financial commitments. From securing the best interest rates on mortgages and auto loans to lowering insurance premiums and even influencing rental applications, a 750+ Credit Score Benefits are far-reaching and deeply impactful.
This article will explore the mechanics of credit scores, dissecting what makes a score ‘excellent’ and outlining the specific ways a 750+ score translates into real-world savings. We will provide actionable strategies for improving and maintaining such a score, ensuring you are well-equipped to harness its full potential. So, if you’re looking to optimize your financial future and save a significant amount of money, understanding and improving your credit score is an indispensable first step.
The Anatomy of a Credit Score: What Constitutes ‘Excellent’?
Before we explore the benefits, let’s first understand what a credit score is and why a 750+ score is considered excellent. In the U.S., the most commonly used credit scoring models are FICO and VantageScore. While they have slightly different ranges, generally, scores fall into these categories:
Anúncios
- Poor: 300-579
- Fair: 580-669
- Good: 670-739
- Very Good: 740-799
- Excellent: 800-850
A score of 750 or higher firmly places you in the ‘Very Good’ to ‘Excellent’ category. Lenders view individuals with such high scores as exceptionally reliable and low-risk borrowers. This perception is crucial, as it directly influences the terms and conditions they are willing to offer you.
Key Factors Influencing Your Credit Score:
Your credit score is a dynamic number, constantly updated based on your financial behavior. Five primary factors contribute to its calculation:
- Payment History (35%): This is the most significant factor. Paying your bills on time, every time, is paramount. Late payments, bankruptcies, and collections can severely damage your score.
- Amounts Owed (30%): This refers to your credit utilization ratio – the amount of credit you’re using compared to your total available credit. Keeping this ratio low (ideally below 30%) is vital.
- Length of Credit History (15%): The longer your credit accounts have been open and in good standing, the better. This demonstrates a track record of responsible borrowing.
- Credit Mix (10%): Having a healthy mix of different types of credit (e.g., credit cards, installment loans like mortgages or auto loans) can positively impact your score, showing you can manage various credit products.
- New Credit (10%): Opening too many new credit accounts in a short period can be seen as risky. Each hard inquiry (when a lender checks your credit for a new application) can temporarily ding your score.
Understanding these components is the first step toward strategically building and maintaining a 750+ credit score. It’s not about magic; it’s about consistent, responsible financial habits.
Anúncios
The Thousand-Dollar Impact: How a 750+ Credit Score Saves You Money
Now, let’s get to the core of the matter: the tangible financial benefits. A 750+ credit score isn’t just about bragging rights; it’s about cold, hard cash saved. These savings accumulate across various aspects of your financial life, often amounting to thousands annually.
1. Lower Interest Rates on Loans: Mortgages, Auto Loans, Personal Loans
This is arguably where a high credit score shines brightest. Lenders offer their most competitive interest rates to borrowers with excellent credit because they represent the lowest risk. Even a seemingly small difference in an interest rate can translate into massive savings over the life of a loan.
Mortgages:
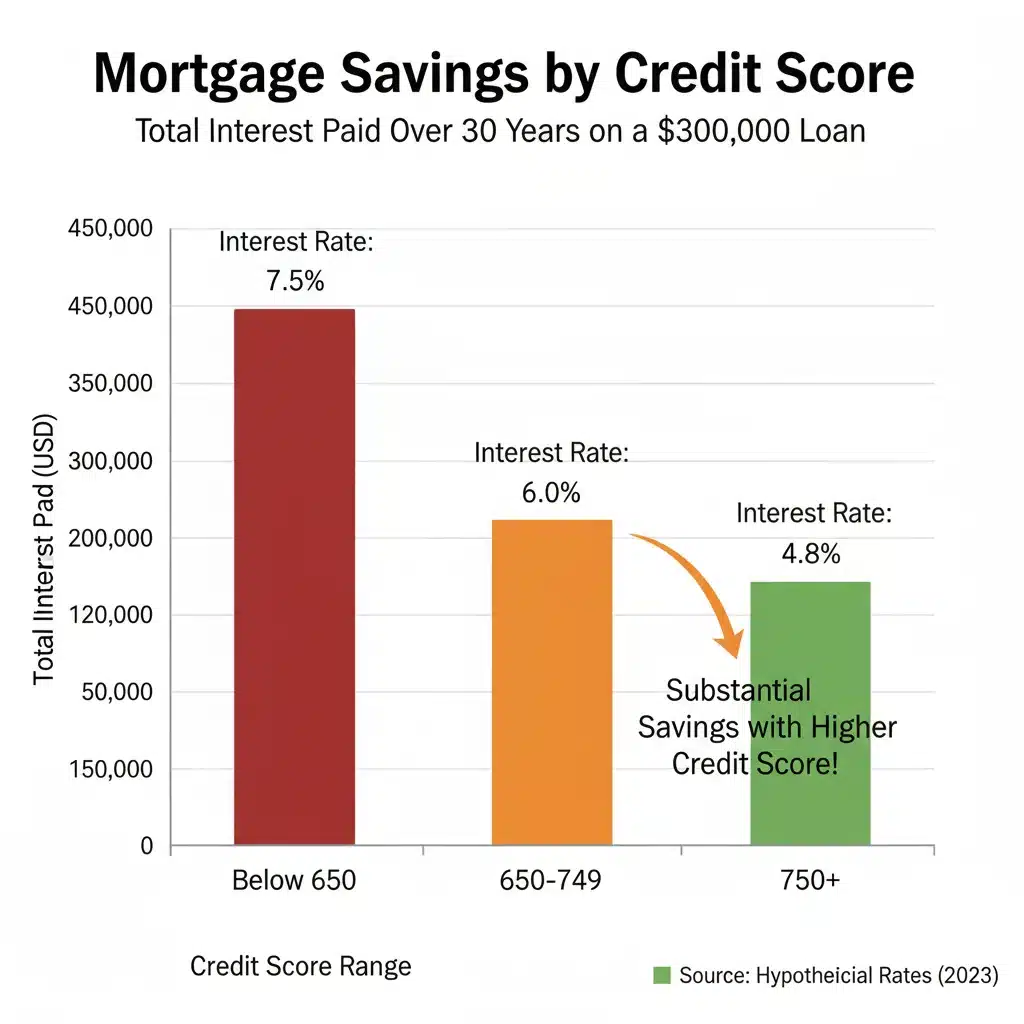
A mortgage is often the largest financial commitment an individual makes. A 750+ credit score can qualify you for the absolute lowest interest rates available. Consider a $300,000, 30-year fixed-rate mortgage. The difference between a 6.5% interest rate (for good credit) and a 5.5% interest rate (for excellent credit) can be staggering:
- 6.5% Interest Rate: Monthly payment approximately $1,896. Total interest paid over 30 years: $382,560.
- 5.5% Interest Rate: Monthly payment approximately $1,703. Total interest paid over 30 years: $313,080.
That’s a savings of nearly $193 per month and a colossal $69,480 over the life of the loan! This isn’t an exaggeration; these are real numbers that illustrate the power of a superior credit score. These savings can free up significant funds for other investments, savings, or simply a better quality of life.
Auto Loans:
Similarly, a high credit score can dramatically reduce the cost of financing a vehicle. For a $30,000, five-year auto loan:
- 7% Interest Rate (Good Credit): Monthly payment approximately $594. Total interest paid: $5,640.
- 4% Interest Rate (Excellent Credit): Monthly payment approximately $552. Total interest paid: $3,120.
Here, you save $42 per month, totaling $2,520 over five years. Imagine applying these savings to car insurance, maintenance, or even investing it.
Personal Loans:
Whether for debt consolidation, home improvements, or unexpected expenses, personal loans can be a lifesaver. With a 750+ score, you’ll secure the lowest available Annual Percentage Rates (APRs), potentially saving hundreds or even thousands depending on the loan amount and term. For example, a $10,000 personal loan over three years could see interest rates drop from 15% (good credit) to 8% (excellent credit), saving you over $1,200 in interest.
2. Lower Insurance Premiums
Surprisingly to some, your credit score can also impact your insurance premiums. In many states, auto and home insurance companies use credit-based insurance scores (a variation of your credit score) to help determine your rates. Statistical data suggests that individuals with higher credit scores tend to file fewer claims, making them less risky to insure.
This means a 750+ credit score could lead to significantly lower premiums for your car, home, and even renters insurance. While the exact savings vary by insurer and state, it’s not uncommon for individuals with excellent credit to pay 10-20% less than those with average credit. Over a year, this could easily amount to several hundred dollars in savings across multiple policies.
3. Better Credit Card Offers and Rewards
With excellent credit, you’re a prime candidate for the most lucrative credit card offers. This includes:
- 0% APR Introductory Offers: For extended periods (12-24 months), allowing you to pay down debt interest-free or finance a large purchase without incurring immediate interest.
- Higher Credit Limits: Providing more financial flexibility and helping to keep your credit utilization ratio low.
- Premium Rewards Programs: Access to top-tier cashback, travel points, and exclusive perks that can save you money on flights, hotels, and everyday purchases.
- Lower Ongoing APRs: If you carry a balance, a lower standard APR means less interest paid.
Maximizing credit card rewards alone can easily translate to hundreds of dollars in value annually, effectively putting money back in your pocket.
4. Easier Approval for Rentals and Utilities
Landlords often check credit scores as part of their tenant screening process. A 750+ score demonstrates reliability and financial stability, making you a more attractive applicant. This can lead to easier approval, potentially avoiding requirements for larger security deposits or co-signers. Similarly, utility companies may waive security deposits for customers with excellent credit, saving you upfront costs.
5. Access to Exclusive Financial Products and Services
Some financial institutions offer exclusive products or services to their most creditworthy clients. This could include preferred banking services, investment opportunities, or specialized financial advice. While not always a direct cash saving, these can provide significant long-term financial benefits and advantages.
6. Enhanced Negotiation Power
When you have a strong credit score, you gain leverage. If you’re comparing loan offers, you can often use a competing offer to negotiate an even better rate with another lender, knowing that your excellent credit makes you a desirable client. This negotiation power can lead to additional savings beyond the initial offers.
Strategies to Achieve and Maintain a 750+ Credit Score
Attaining a 750+ credit score is a journey that requires discipline and strategic financial management. Here are the most effective strategies:
1. Pay All Bills On Time, Every Time
This cannot be stressed enough. Payment history accounts for 35% of your FICO score. Set up automatic payments for all your bills, including credit cards, loans, utilities, and even rent if reported to credit bureaus. A single late payment can significantly ding your score.
2. Keep Your Credit Utilization Low
As mentioned, credit utilization is 30% of your score. Aim to keep the amount of credit you’re using below 30% of your total available credit. For example, if you have a credit card with a $10,000 limit, try to keep your balance below $3,000. Even better, aim for below 10% for optimal results. Paying down balances multiple times a month can also help.
3. Maintain a Long Credit History
The average age of your credit accounts matters (15% of your score). Avoid closing old credit accounts, even if you don’t use them frequently, as this can shorten your credit history and reduce your total available credit, impacting your utilization ratio. Keep your oldest accounts open and in good standing.
4. Diversify Your Credit Mix (Responsibly)
Having a mix of installment loans (like mortgages or auto loans with fixed payments) and revolving credit (like credit cards with variable payments) demonstrates your ability to manage different types of credit (10% of your score). However, only take on new credit if you genuinely need it and can afford the payments. Don’t open accounts just to diversify.
5. Limit New Credit Applications
Each time you apply for new credit, a ‘hard inquiry’ is placed on your credit report, which can temporarily lower your score by a few points (10% of your score). Only apply for credit when necessary, and space out your applications. Multiple hard inquiries in a short period can signal to lenders that you’re in financial distress or taking on too much debt.
6. Regularly Monitor Your Credit Report
It’s crucial to regularly check your credit reports from the three major bureaus (Experian, Equifax, and TransUnion) for errors or fraudulent activity. You can get a free copy of your credit report from each bureau once every 12 months at AnnualCreditReport.com. Dispute any inaccuracies immediately, as they can negatively impact your score.
7. Become an Authorized User (If Applicable)
If you have a trusted family member or partner with excellent credit and a long, positive payment history, becoming an authorized user on one of their credit cards can help improve your score. Their positive payment history and low utilization will be reflected on your report, but ensure they are financially responsible.
8. Consider a Secured Credit Card or Credit-Builder Loan
If your credit score is currently low, these tools can help you build credit responsibly. A secured credit card requires a cash deposit as collateral, while a credit-builder loan involves you making payments into a savings account that is released to you at the end of the loan term. Both report your payments to credit bureaus, helping to establish a positive payment history.
The Long-Term Rewards of a High Credit Score
The benefits of a 750+ credit score extend beyond immediate savings. It builds a foundation for long-term financial stability and opportunity. With excellent credit, you are positioned to:
- Achieve Financial Goals Faster: Whether it’s buying a home, starting a business, or funding education, lower borrowing costs mean more of your money goes towards the principal, accelerating your progress.
- Navigate Financial Emergencies More Easily: In times of unexpected financial strain, access to low-interest credit can be a lifesaver, providing a safety net without burdening you with exorbitant interest rates.
- Experience Less Financial Stress: Knowing you have a strong financial profile provides peace of mind and reduces the stress associated with financial applications and approvals.
- Gain Trust from Lenders and Businesses: Your credit score is a reflection of your financial reliability. A high score builds trust, opening doors to better opportunities and terms across various financial interactions.
Common Misconceptions About Credit Scores
To further empower you, let’s dispel a few common myths:
- Checking your own credit score hurts it: This is false. Checking your own credit is a ‘soft inquiry’ and does not affect your score.
- Closing old credit cards boosts your score: Actually, it can do the opposite. Closing an old, unused card reduces your total available credit, which can increase your credit utilization ratio and shorten your credit history.
- Carrying a balance improves your score: Not true. You don’t need to pay interest to build credit. Paying your balance in full each month is the best practice for both your score and your wallet.
- All debt is bad: While excessive debt is detrimental, responsibly managed debt (like a mortgage or student loan) can actually help build a strong credit history.
Conclusion: Your Path to Thousands in Savings
In the competitive financial landscape of the U.S., a 750+ credit score is not merely a benchmark of financial responsibility; it is a powerful tool for wealth accumulation and significant annual savings. The thousands of dollars you can save on interest rates for major loans, reduced insurance premiums, and superior credit card rewards are not abstract figures; they are real, measurable benefits that directly impact your financial well-being.
By diligently adhering to the strategies outlined in this guide – prioritizing on-time payments, maintaining low credit utilization, nurturing a long credit history, and monitoring your reports – you can build and sustain an excellent credit score. This commitment will translate into a more secure financial future, granting you access to the best financial products and services, and ultimately empowering you to achieve your financial goals with greater ease and lower cost.
Don’t underestimate the power of your credit score. Start taking proactive steps today to understand, improve, and leverage your credit, and watch as those thousands of dollars in savings begin to materialize, year after year. Your financial future is largely in your hands, and a 750+ credit score is your ticket to unlocking its full potential.