Social Security Disability Benefits: Understanding the 2026 Cost-of-Living Adjustment (COLA) of 2.5%
For millions of Americans relying on Social Security Disability benefits, understanding the annual Cost-of-Living Adjustment (COLA) is crucial for financial planning and stability. The COLA is designed to ensure that the purchasing power of Social Security benefits is not eroded by inflation. As we look ahead to 2026, projections indicate a potential 2026 COLA disability adjustment of around 2.5%. This article delves into what this projected increase means for beneficiaries, how it’s calculated, its potential impact, and what you should consider to prepare for these changes.
The Social Security Administration (SSA) makes annual adjustments to benefits to keep pace with the rising cost of goods and services. These adjustments are particularly vital for individuals with disabilities who may have limited income sources. A 2.5% increase, while seemingly modest, can have a significant cumulative effect on a beneficiary’s financial well-being over time. It reflects ongoing economic trends and the SSA’s commitment to maintaining the value of the support it provides.
Navigating the complexities of Social Security can be challenging, but being informed about upcoming changes like the 2026 COLA disability is the first step towards securing your financial future. We’ll explore the historical context of COLA, the specific methodology used for its determination, and the broader economic factors that influence these critical annual adjustments. Understanding these elements will empower you to better anticipate and adapt to the financial landscape of 2026 and beyond.
Anúncios
What is COLA and Why Does It Matter for Disability Benefits?
The Cost-of-Living Adjustment (COLA) is an annual increase in Social Security and Supplemental Security Income (SSI) benefits. Its primary purpose is to protect the purchasing power of these benefits from inflation. Without COLA, the fixed income of beneficiaries would gradually lose value as the cost of living rises, making it harder to afford necessities like food, housing, and healthcare.
For individuals receiving Social Security Disability Insurance (SSDI) or Supplemental Security Income (SSI), COLA is not just a technical adjustment; it’s a lifeline. These benefits often represent the primary, if not sole, source of income for many recipients. A consistent and appropriate COLA ensures that beneficiaries can maintain their standard of living despite inflationary pressures. The projected 2026 COLA disability of 2.5% is an estimate based on current economic forecasts, and it will play a crucial role in determining the financial outlook for millions.
The significance of COLA extends beyond simply increasing monthly payments. It influences budgeting, access to services, and overall financial stability. For example, a higher COLA can help offset increased medical costs or rising utility bills. Conversely, a low or non-existent COLA in periods of high inflation can lead to significant financial strain. This is why the announcement and understanding of the 2026 COLA disability are so keenly anticipated each year.
Understanding the mechanism behind COLA is also important. It’s not an arbitrary decision but a calculation tied to specific economic indicators. This scientific approach aims to provide a fair and objective adjustment that reflects real-world economic conditions. While the exact percentage can fluctuate based on these indicators, the commitment to making these adjustments remains a cornerstone of the Social Security program.
How is the 2026 COLA Calculated? The CPI-W’s Role
The Social Security Administration determines the annual COLA based on the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). This index measures the average change over time in the prices paid by urban wage earners and clerical workers for a market basket of consumer goods and services. The calculation method is straightforward yet critical:
- Reference Period: The SSA compares the average CPI-W for the third quarter (July, August, and September) of the current year (in this case, 2025) with the average CPI-W for the third quarter of the last year in which a COLA was enacted (usually the prior year).
- Percentage Increase: The percentage increase in the CPI-W between these two periods determines the COLA. If there is no increase, or if prices decrease, there is no COLA.
- Rounding: The resulting percentage is then rounded to the nearest one-tenth of one percent.
For the 2026 COLA disability, the SSA will look at the CPI-W data for Q3 2025 and compare it to Q3 2024. The projected 2.5% increase is an early estimate, and the final figure will be announced in October 2025 once the official CPI-W data for July, August, and September of that year becomes available. It’s important to remember that this projection is subject to change as economic conditions evolve.
The CPI-W is chosen because it is considered to reflect the spending patterns of working-class Americans, which aligns with the demographic served by Social Security benefits. While other inflation measures exist, such as the CPI-U (Consumer Price Index for All Urban Consumers), the CPI-W is specifically mandated by law for COLA calculations. This ensures consistency and transparency in the adjustment process for the 2026 COLA disability and all future COLAs.
Critics sometimes argue that the CPI-W doesn’t fully capture the spending habits of seniors and people with disabilities, who may have higher healthcare costs than the general working population. However, for now, it remains the standard metric. Understanding this calculation method helps beneficiaries appreciate the factors influencing their future benefit amounts.
Projected 2.5% Increase: What Does It Mean for Your Benefits?
A projected 2.5% increase in the 2026 COLA disability means that, on average, beneficiaries would see their monthly payments rise by that percentage. To illustrate, if your current monthly disability benefit is $1,500, a 2.5% COLA would add $37.50 to your monthly payment, bringing it to $1,537.50. While this might seem like a small amount on a monthly basis, it accumulates significantly over a year, totaling an additional $450 annually in this example.
Anúncios
This increase is designed to help you keep pace with the rising cost of living. However, it’s crucial to consider this adjustment in the context of broader economic trends. If inflation rates are higher than 2.5%, your purchasing power might still slightly diminish. Conversely, if inflation is lower, the 2.5% COLA could provide a small boost in real income.
It’s also important to remember that the COLA applies to both Social Security Disability Insurance (SSDI) and Supplemental Security Income (SSI) benefits. However, the impact on SSI recipients can be more nuanced due to strict income and resource limits. An increase in SSI benefits due to COLA might, in some cases, affect eligibility for other means-tested programs, although the SSA typically adjusts these thresholds as well to prevent a ‘benefits cliff.’
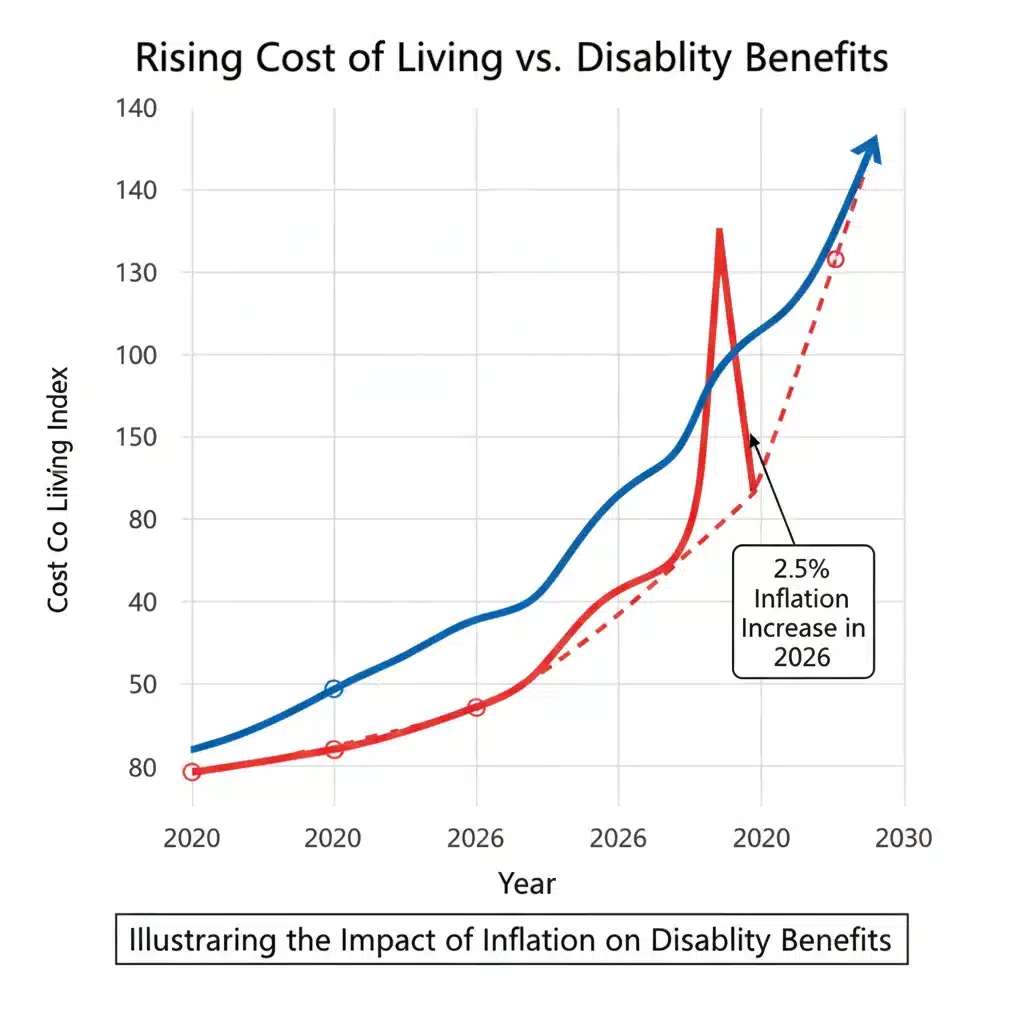
Beneficiaries should use this projected 2026 COLA disability as an opportunity to review their personal budgets. Consider how rising costs in areas like healthcare, housing, and transportation might interact with this increase. Proactive financial planning can help ensure that the adjustment effectively contributes to your financial security.
Furthermore, this increase also affects the maximum taxable earnings for Social Security, the maximum Social Security benefit, and the Substantial Gainful Activity (SGA) limits for disability beneficiaries. While the COLA directly impacts your monthly check, these other adjustments can have indirect but equally significant implications for your overall financial planning and eligibility status. Staying informed about all these related changes is key to maximizing your benefits and avoiding any potential pitfalls.
Historical Context of COLA Adjustments
To fully appreciate the projected 2026 COLA disability, it’s helpful to look at historical COLA adjustments. Since automatic annual COLAs began in 1975, the percentages have varied significantly, reflecting different economic periods:
- High Inflation Eras: In the late 1970s and early 1980s, COLAs were in the double digits (e.g., 14.3% in 1980, 11.2% in 1981) due to rampant inflation.
- Periods of Low Inflation: More recently, especially in the 2010s, COLAs have been much lower, with some years seeing no increase at all (e.g., 0% in 2010, 2011, and 2016).
- Recent Trends: The past few years have seen higher COLAs, such as 5.9% for 2022 and 8.7% for 2023, driven by a surge in inflation following the pandemic. The 3.2% COLA for 2024 reflected a moderation of inflation.
The projected 2.5% for the 2026 COLA disability falls within the range of more moderate increases seen in recent decades, suggesting a return to more stable, though still inflationary, economic conditions. This historical perspective underscores the dynamic nature of COLA and its direct link to broader economic health, particularly inflation.
Understanding these historical patterns helps beneficiaries set realistic expectations. While a 2.5% increase might not feel as impactful as the larger COLAs of recent years, it’s a positive adjustment that contributes to the long-term sustainability of benefits. It also highlights the importance of personal savings and other income sources to supplement Social Security, especially during periods of lower COLA or unexpected economic downturns.
The history of COLA adjustments also serves as a reminder of the Social Security program’s adaptability. Designed to be a robust safety net, it incorporates mechanisms like COLA to respond to changing economic realities. This flexibility is what allows the program to continue providing essential support to millions of Americans, including those with disabilities, for generations.
Potential Impact on Other Benefits and Programs
The 2026 COLA disability doesn’t just affect your Social Security Disability payment; it can also have ripple effects on other government benefits and programs. This is particularly true for individuals receiving Supplemental Security Income (SSI) or those participating in means-tested programs.
SSI and the COLA
SSI benefits are also subject to COLA, meaning they will also increase by the projected 2.5%. However, SSI has strict income and resource limits. While the SSA usually adjusts these limits upwards to account for COLA, there’s a potential for beneficiaries to be pushed over an income threshold for other state or federal programs if those programs don’t adjust their limits proportionally. This is a critical consideration for SSI recipients, as even a small increase can sometimes jeopardize eligibility for housing assistance, food stamps (SNAP), or Medicaid in certain circumstances.
Medicare Premiums
Another significant factor is Medicare Part B premiums. These premiums are typically deducted directly from Social Security benefits. Historically, a ‘hold harmless’ provision has protected many beneficiaries from seeing their net Social Security payment decrease due to rising Medicare premiums. However, this provision primarily applies if your Part B premium increase would otherwise reduce your net Social Security benefit below the previous year’s level. The 2026 COLA disability will influence how much of an increase in Medicare premiums beneficiaries might absorb.
Substantial Gainful Activity (SGA) Limits
For SSDI recipients, the Substantial Gainful Activity (SGA) limit is crucial. This is the amount of monthly earnings the SSA considers ‘substantial.’ If you earn above this limit (and are not in a Trial Work Period), your disability benefits may cease. The SGA limit is also adjusted annually, often in line with economic indicators, though not directly tied to COLA. However, a general increase in wages and cost of living, which COLA reflects, also influences the SGA limit. Beneficiaries considering returning to work should monitor the updated SGA limits for 2026 to understand how the 2026 COLA disability and other adjustments might affect their work incentives.
State and Local Programs
Many state and local assistance programs use federal poverty guidelines or income thresholds that may or may not be directly tied to Social Security COLA. It’s essential for beneficiaries to check with their local agencies to understand how a 2.5% increase in their Social Security benefits might impact their eligibility for state-specific programs like energy assistance, rental subsidies, or prescription drug assistance. The interplay between federal and state benefit adjustments can be complex and requires careful attention.
In summary, while the 2026 COLA disability is a positive development for most beneficiaries, its broader impact necessitates a thorough review of all benefits received. Proactive communication with relevant agencies can help prevent unexpected changes in eligibility or benefit amounts.
Financial Planning Strategies for Disability Beneficiaries
Even with the projected 2026 COLA disability, effective financial planning remains paramount for individuals receiving disability benefits. Here are some strategies to help you maximize your financial stability:
1. Create and Maintain a Detailed Budget
Knowing exactly where your money goes is the first step. Track all your income (including your disability benefits and any other sources) and expenses. Categorize your spending to identify areas where you might be able to save. A detailed budget will help you understand the real impact of the 2.5% COLA on your disposable income and allow you to adjust for any rising costs not fully covered by the increase.
2. Monitor Inflation and Cost of Living
While COLA aims to offset inflation, it’s a backward-looking measure. Keep an eye on current inflation rates, particularly for essential goods and services that make up a significant portion of your spending, such as groceries, utilities, and healthcare. This awareness will help you make informed spending decisions and adjust your budget proactively, rather than reactively to the 2026 COLA disability.
3. Explore Additional Income Sources (Within Limits)
For SSDI recipients, the SSA has work incentive programs that allow you to test your ability to work without immediately losing benefits. These include the Trial Work Period (TWP) and Extended Period of Eligibility (EPE). For SSI recipients, there are specific rules regarding earned income that allow you to keep a portion of your benefits. Researching these options can provide a vital supplement to your disability payments and help mitigate the effects of inflation not fully covered by COLA. Always be mindful of the Substantial Gainful Activity (SGA) limits, which will also be adjusted for 2026.
4. Build an Emergency Fund
Even a small emergency fund can provide a crucial buffer against unexpected expenses, such as medical emergencies or home repairs. Aim to save at least three to six months’ worth of essential living expenses if possible. Even saving a small amount each month from your 2026 COLA disability increase can make a difference over time.
5. Review and Understand All Your Benefits
As discussed, COLA can affect eligibility for other programs. Regularly review your eligibility for Medicaid, Medicare Savings Programs, SNAP (food stamps), housing assistance, and other state or local aid. Ensure you understand how your increased Social Security income might interact with these benefits. Don’t hesitate to contact program administrators for clarification.
6. Seek Financial Advice
Consider consulting with a financial advisor who specializes in disability benefits or retirement planning. They can offer personalized advice on budgeting, investing (if applicable), and navigating the complexities of government benefits. Many non-profit organizations also offer free or low-cost financial counseling services.
7. Plan for Healthcare Costs
Healthcare costs are a significant concern for disability beneficiaries. Understand your Medicare or Medicaid coverage, including deductibles, co-pays, and prescription drug costs. Factor potential increases in Medicare Part B premiums into your budget, especially in light of the 2026 COLA disability. Explore Medicare Advantage plans or Medigap policies if they align with your needs and budget.
By implementing these strategies, disability beneficiaries can better manage their finances, adapt to changes like the 2026 COLA disability, and maintain a greater sense of financial security.
Advocacy and Future Outlook for COLA
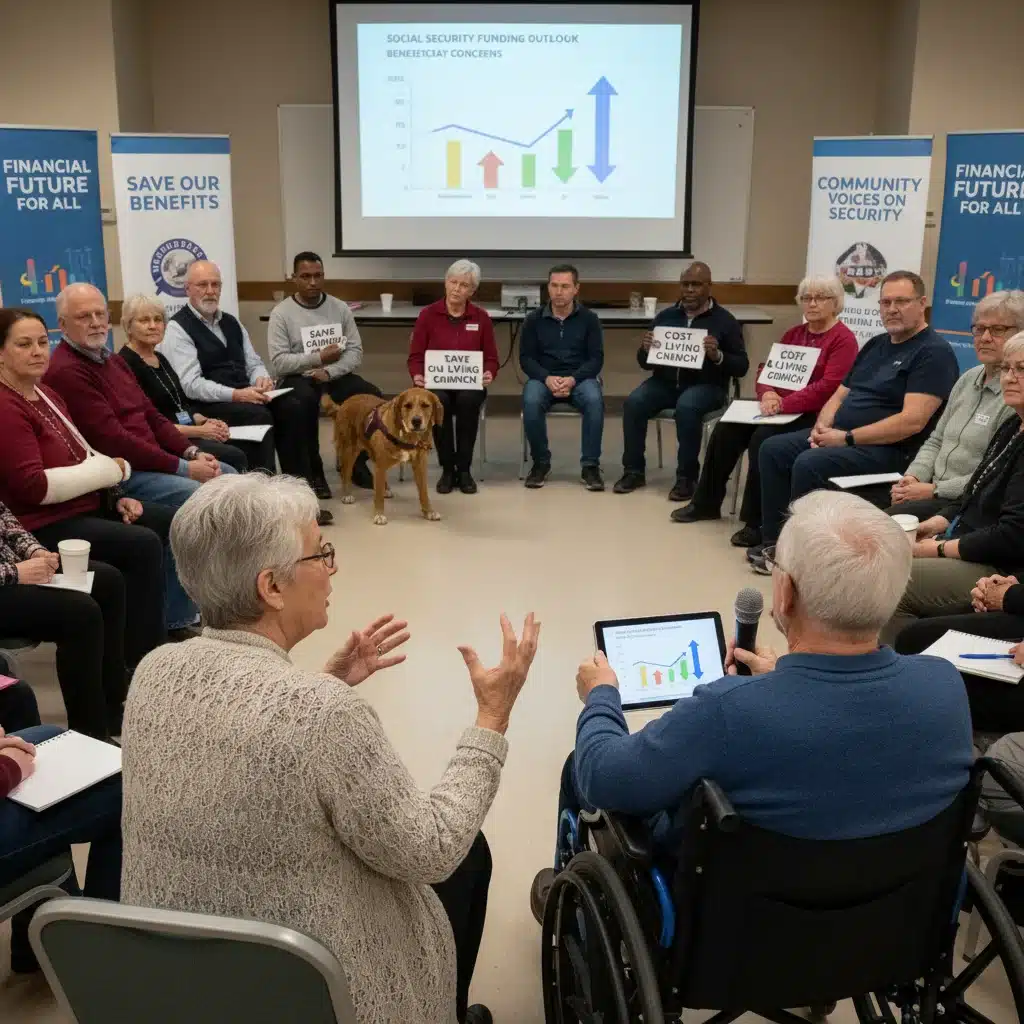
The discussion around COLA, including the projected 2026 COLA disability, often involves broader conversations about the adequacy of Social Security benefits and the future of the program. Various advocacy groups and policymakers regularly debate whether the current COLA calculation method (CPI-W) accurately reflects the cost of living for all beneficiaries, particularly seniors and individuals with disabilities.
Calls for CPI-E
One common proposal is to switch to the Consumer Price Index for the Elderly (CPI-E). This experimental index focuses more heavily on categories like healthcare, which typically consume a larger portion of seniors’ and disabled individuals’ budgets. Advocates argue that using CPI-E would result in higher and more accurate COLAs for these populations, providing a more realistic adjustment to their cost of living. While there’s ongoing debate, a shift to CPI-E for COLA calculation would represent a significant change in how the 2026 COLA disability and future adjustments are determined.
Long-Term Solvency of Social Security
The solvency of the Social Security trust funds is another perennial topic. While COLA directly impacts current beneficiaries, the overall health of the system affects everyone. Discussions around potential reforms, such as adjusting the full retirement age, modifying the taxation of benefits, or changing the COLA formula, are part of this larger conversation. Beneficiaries should stay informed about these policy debates, as they could influence the long-term stability and structure of their benefits, including how future COLAs are applied beyond the 2026 COLA disability.
The Role of Economic Conditions
The future outlook for COLA is intrinsically linked to global and national economic conditions. Factors such as inflation rates, energy prices, supply chain stability, and employment figures all play a role in shaping the CPI-W and, consequently, the COLA. A stable economic environment typically leads to more predictable, albeit possibly smaller, COLA adjustments. Conversely, periods of high volatility can result in larger, but also more uncertain, adjustments.
Staying Informed and Engaged
For disability beneficiaries, staying informed about these discussions and engaging with advocacy efforts can be beneficial. Organizations dedicated to disability rights and senior welfare often provide updates on legislative proposals and economic forecasts that could impact Social Security benefits. Understanding the forces that shape COLA, including the 2026 COLA disability, empowers beneficiaries to be better advocates for their own financial well-being.
Ultimately, while the 2.5% projected COLA for 2026 offers a glimpse into the near future, the broader landscape of Social Security benefits is constantly evolving. Continuous engagement with reliable information sources and proactive financial planning are the best ways to navigate these changes.
Conclusion: Preparing for the 2026 COLA Disability Adjustment
The projected 2026 COLA disability of 2.5% is an important development for millions of Social Security Disability beneficiaries. While the final figure will be announced in October 2025, this estimate provides a valuable opportunity for proactive financial planning. This adjustment is designed to help your benefits keep pace with inflation, ensuring your purchasing power is maintained.
Understanding how COLA is calculated, primarily through the CPI-W, demystifies the process and highlights its direct link to economic realities. While a 2.5% increase may seem modest compared to recent years, it represents a crucial annual safeguard against the erosion of your benefits by rising costs. It underscores the Social Security Administration’s commitment to supporting individuals with disabilities.
Beneficiaries are encouraged to review their personal budgets, consider the potential impacts on other means-tested programs, and stay informed about updated Medicare premiums and Substantial Gainful Activity (SGA) limits. Engaging in sound financial planning strategies, such as budgeting, emergency savings, and exploring work incentives, can significantly enhance your financial security.
Looking ahead, the ongoing dialogue about the COLA calculation method and the long-term solvency of Social Security will continue to shape the future of these vital benefits. By staying informed and understanding the intricacies of the 2026 COLA disability and subsequent adjustments, you can better navigate your financial journey and ensure your benefits continue to provide the support you need.
For the most accurate and up-to-date information regarding your specific benefits and the official 2026 COLA announcement, always consult the official Social Security Administration website or contact them directly.